January 16 , 2025


🏡 Big Ideas, Bigger Headlines, Slower Impact

⚡TL;DR — Quick Takeaways:


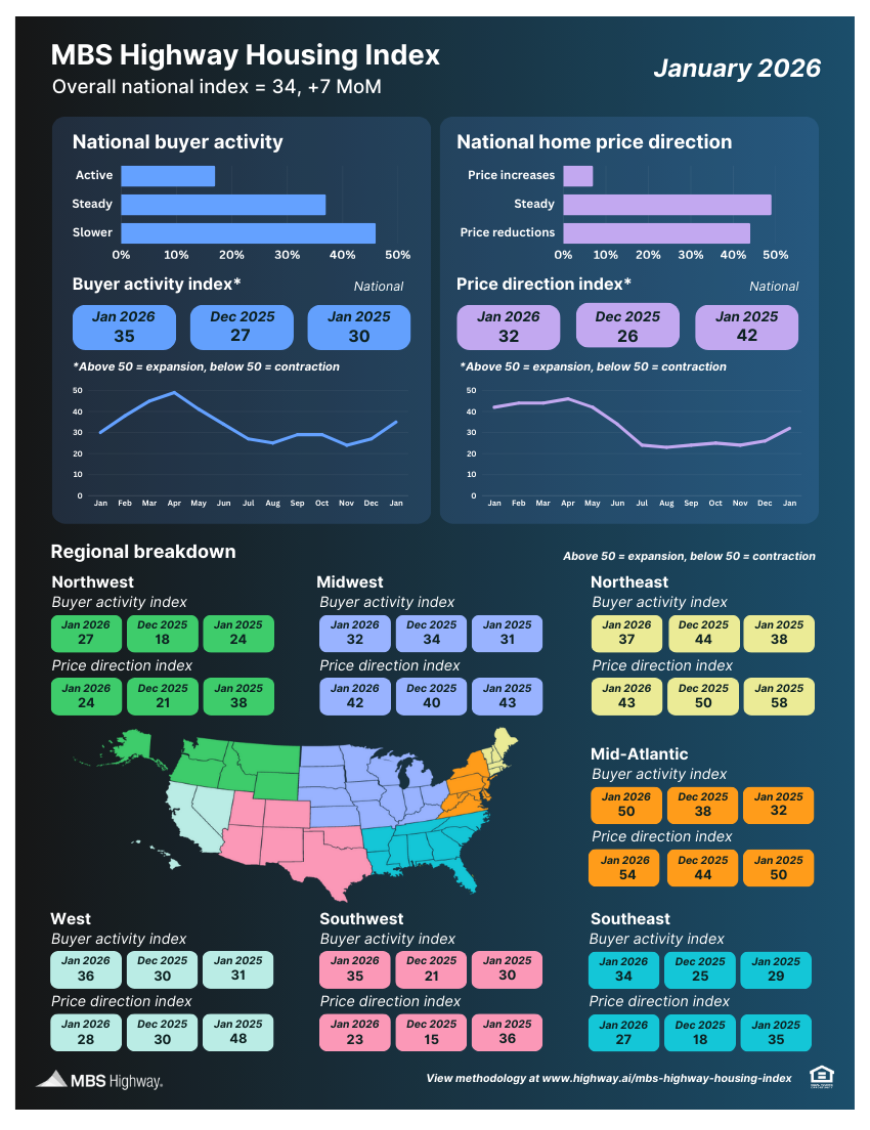
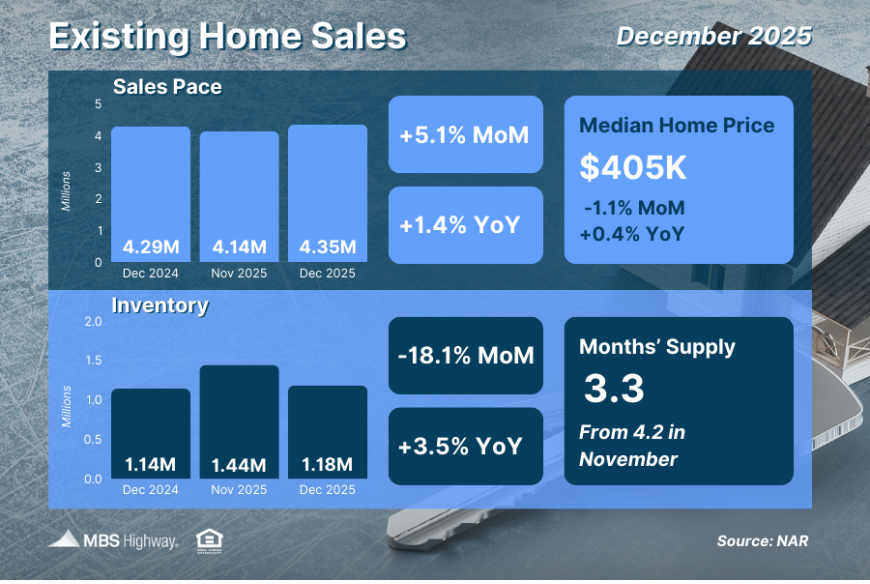
Activity is picking up: Purchase applications jumped 16 percent last week, and existing home sales hit their strongest pace in nearly three years.


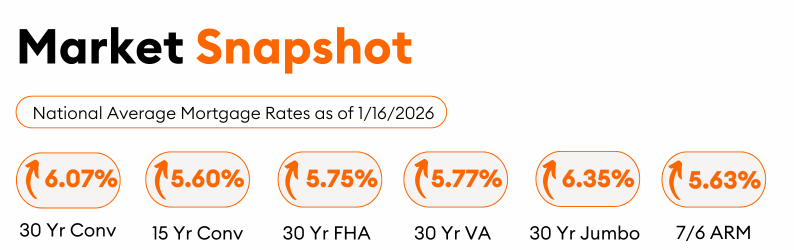
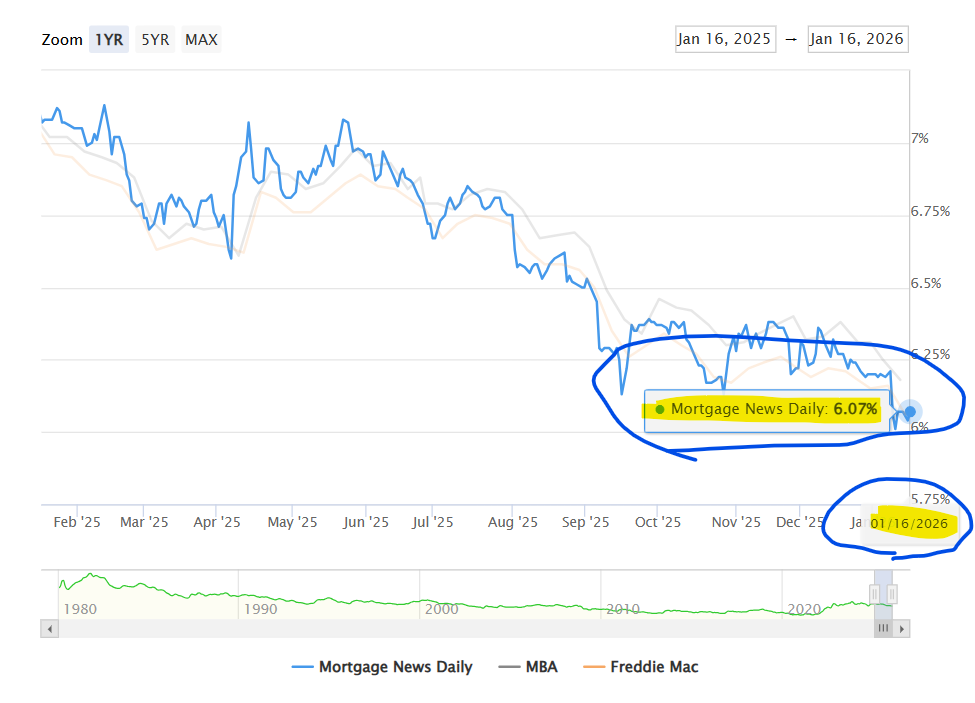
Rates are helping: Mortgage rates in the high 5 percent to low 6 percent range have been enough to pull serious buyers off the sidelines.


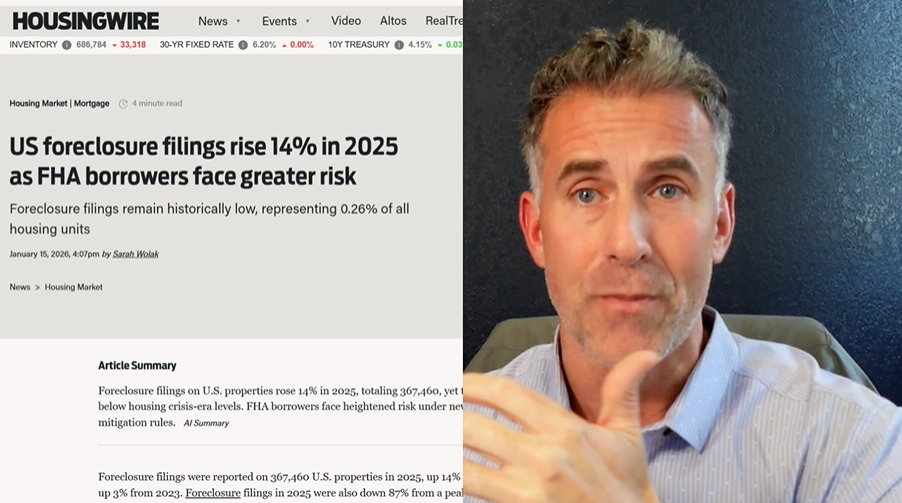
Foreclosure headlines are misleading: Filings rose, but they still represent about 0.26 percent of housing units, roughly one-tenth of 2008 levels. This is normalization, not distress.


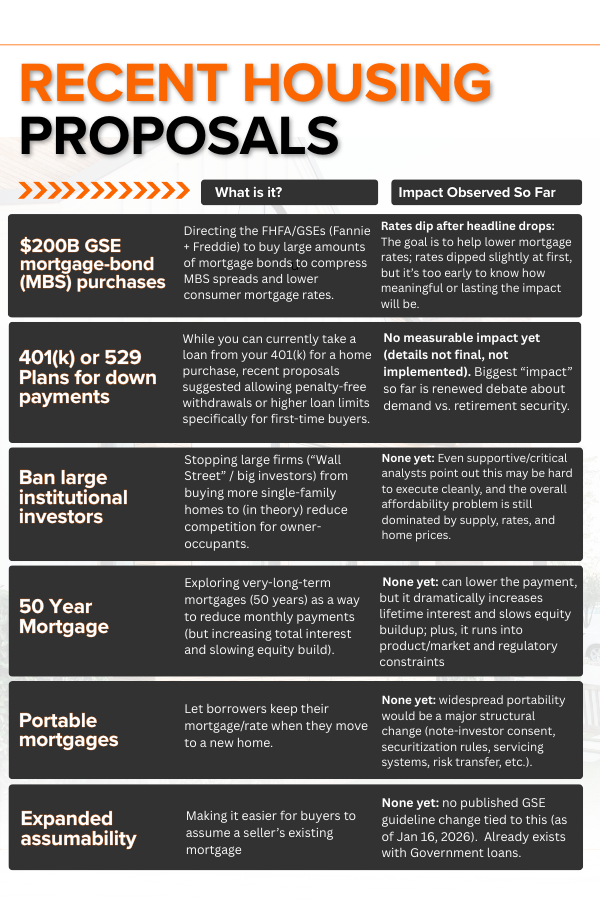
Policy proposals are loud: Market impact is limited so far. The infographic below breaks down what each proposal aims to achieve and the observed impact.


Featured financing solution: Buy Before You Sell can help remove the home-sale contingency, reduce DTI by offsetting the current payment, offer a 0% bridge option, and unlock roughly 70-75% of current home equity.

🗓️ Click here to view the full economic calendar 

Happy Friday!


As we move deeper into January, the "wait-and-see" approach of 2025 is starting to shift. We are seeing a genuine pickup in activity to start the year, with purchase applications jumping last week alone and existing home sales surging to their strongest pace in nearly three years.


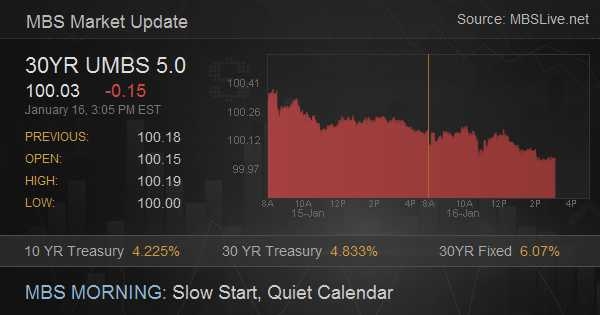
Rate Momentum: Mortgage rates are still hovering near 2–3 year lows (ranging from high-5% to low-6%). This has been enough to pull serious buyers off the sidelines who realize that "perfect" is the enemy of "good."


The Foreclosure Reality: Don't let the scary headlines fool you. While filings are up slightly as the market normalizes, they represent just 0.26% of all housing units—roughly one-tenth of what we saw during the 2008 crisis. This is a sign of a healthy recalibration, not a market crash.


Zooming Out: Policy vs. Reality: There is a long list of proposed "fixes" in the news right now...from 50-year mortgages to banning institutional buyers. While these ideas are making waves, most are still in the early proposal or executive order stages and haven't actually changed the market yet.


401(k) for down payments: One of the most talked-about proposals is allowing buyers to use their 401(k) funds for down payments. Here’s what people often miss: you can already do this. Existing IRS rules already allow for 401(k) loans (up to $50,000) or hardship withdrawals for a primary residence. The new proposals aim to make this "penalty-free" or easier, but the tool is already in your belt. While politicians debate "new" ways to help, as a pro, you can show your clients the tools they already have in their belt.


[See below for the deep dive on how your clients can leverage these accounts today.] 👇

The 401(k) Loan


Most employer-sponsored plans allow participants to borrow against their own balance.


  • Limit: Generally up to $50,000 (or 50% of the vested balance).
  • The Benefit: This is not a withdrawal. It is a loan that the client pays back to themselves, interest and all.
  • Tip: Because it's a loan, it usually isn't taxed as income, and it doesn't trigger the 10% early withdrawal penalty. Plus, the repayment period can often be extended beyond the standard 5 years if used for a primary residence.

The IRA "First-Time" Exception


The IRS defines a "first-time homebuyer" as anyone who hasn't owned a principal residence in the last two years.


  • Traditional IRA: Clients can withdraw up to $10,000 penalty-free to buy, build, or rebuild a home. They will still owe income tax on the amount, but the 10% "early bird" penalty is waived.
  • Roth IRA: Clients can always withdraw their original contributions tax-free and penalty-free for any reason. If they've had the account for 5+ years, they can also pull up to $10,000 of earnings totally tax-free for a home purchase.
  • The Spousal Multiplier: If a couple is buying together, they can each pull $10,000, totaling $20,000 in penalty-free capital.

Foreclosures: The Headline vs. Reality Story


What happened

  • Headlines reported foreclosure filings rose 14% in 2025.
  • Total filings were 367,460 properties, just 0.26% of housing units.
  • Activity remains far below pre-pandemic and crisis levels.
  • FHA borrowers face increased risk due to new loss-mitigation rules.

Why it matters

  • This is normalization, not distress.
  • Strong homeowner equity continues to act as a shock absorber.
  • Media headlines overstated the risk relative to historical context.

Quote to Ponder


"The mind once stretched by a new idea, never returns to its original dimension."


– Oliver Wendell Holmes

Featured Financing Solution

Buy Before You Sell Loan


✅ Eliminate Contingencies.

✅ Remove existing mortgage payment from debt to income ratio to qualify.

✅ 0% Bridge Loan.

✅ Unlock up to 70-75% of the equity in the current home.

Important Reports

Recent Real Estate and Economic News

Slow Start, Quiet Calendar

Last week reinforced the lesson anything can happen in the bond market--even with less than an hour left on an otherwise uneventful day. There's no way to plan ahead for that eternal caveat, so we're ...

Mortgage rates plunge to a three-year low

US borrowers get more relief as rates dive again

More US mortgages now carry 6% rates than pandemic-era lows

Rate lock-in persisted, but a key threshold hints at a slow market reset

Links Worth Saving

📈 Track National Mortgage Rates Real Time

💹 CPI Inflation Calculator

🧮 Mortgage Calculator

📜 Seller Concession Cheat Sheet

🔍Corelogic Intelligence Insights

Joe Jacobs

Mortgage Broker/Owner

1101 College Ave, Ste 215

Santa Rosa, CA 95404

(707) 696 6937

joe@intentionfinancial.net

NMLS 453314


X Share This Email
LinkedIn Share This Email