|
December 18 , 2025
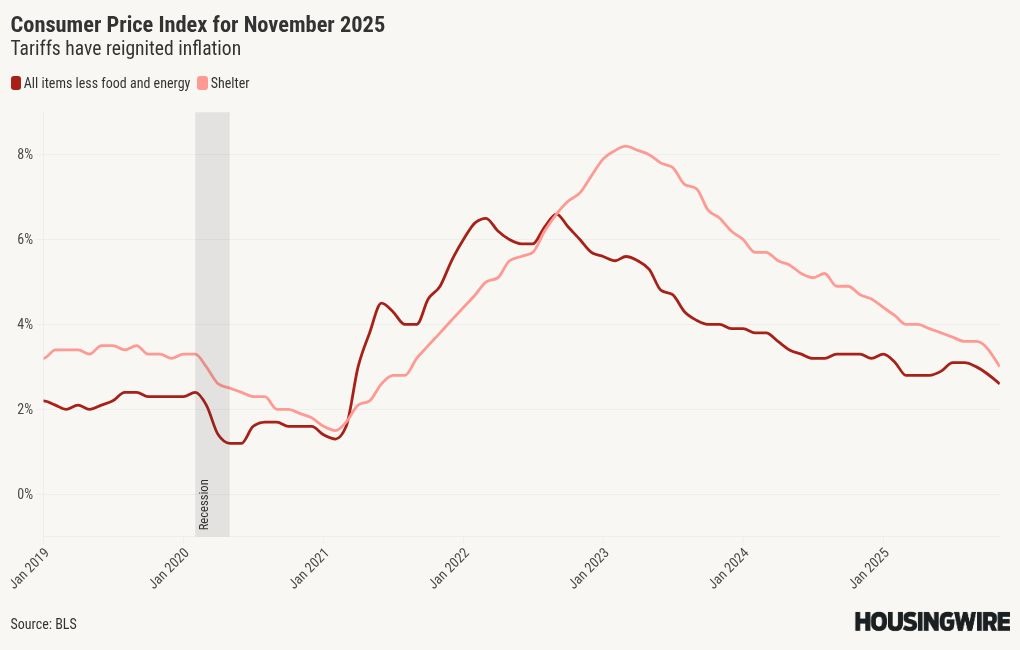
Fed Cuts Rates. Inflation Improved. Mortgage Rates?
| | | | |
|
⚡TL;DR — Quick Takeaways:
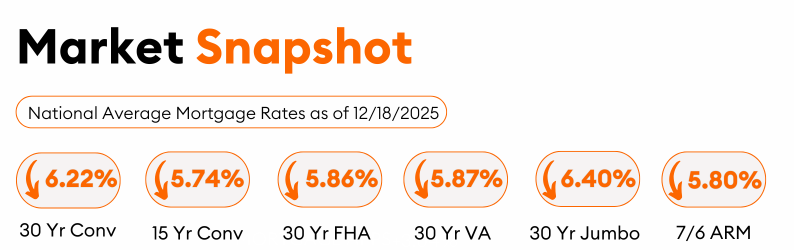
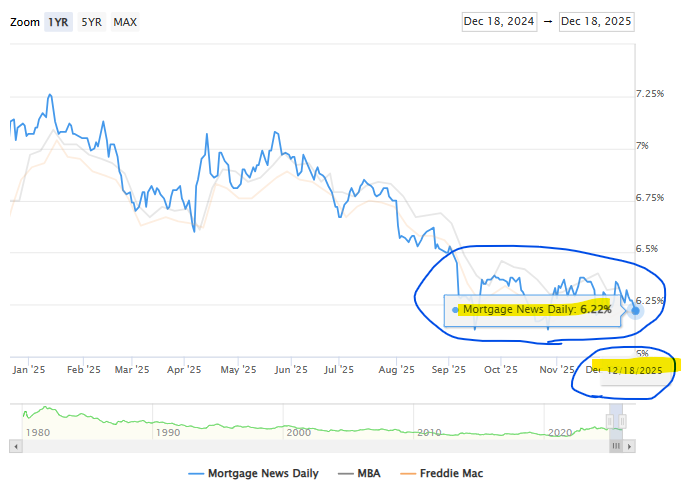
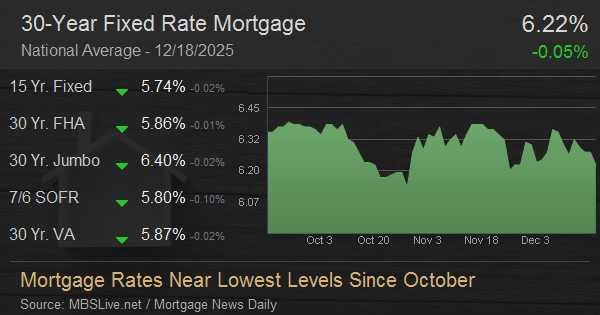
Mortgage Rates: Even after the Fed cut of .25% last week and a softer-than-expected inflation report, we are sitting at 6.22% National Average (Mortgage News Daily) and getting closer and closer to breaking through the 3-Year Low barrier.
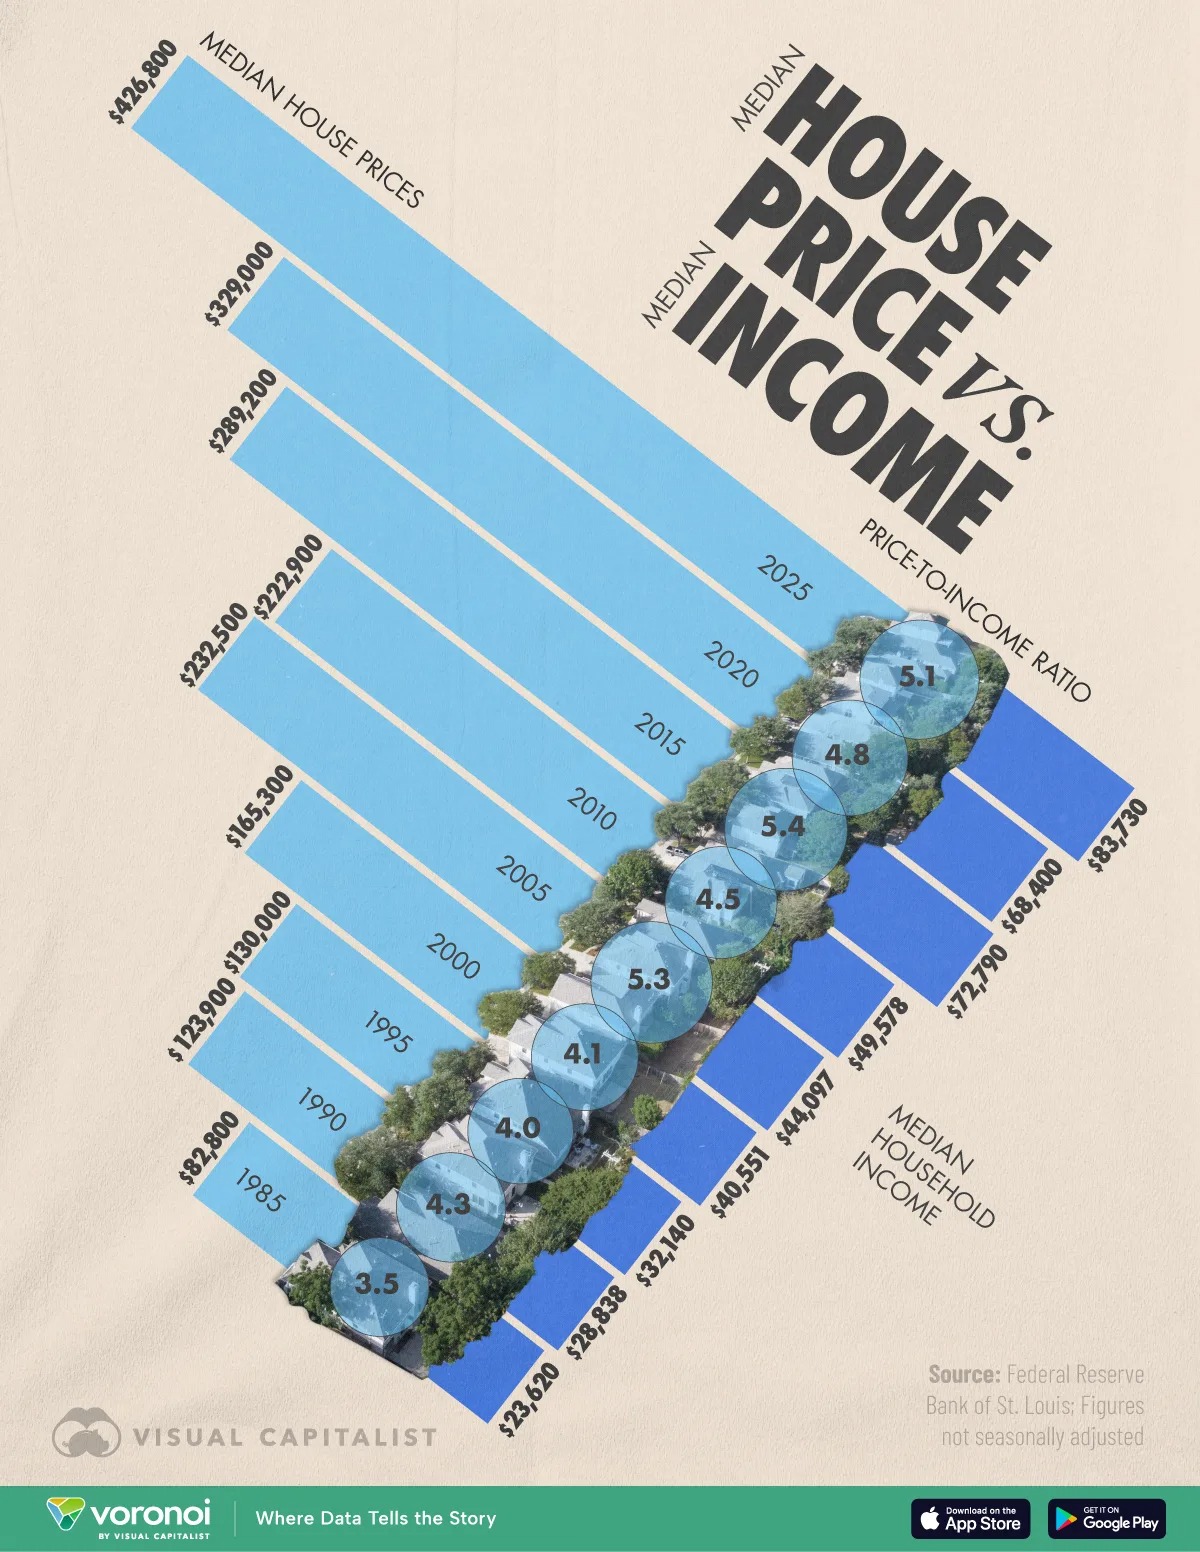
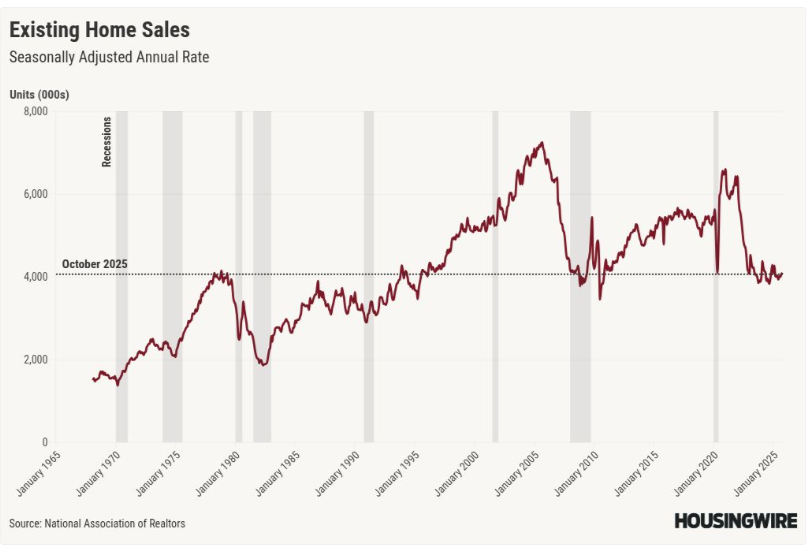
Price-to-Income Reality: The long-term rise in the price-to-income ratio highlights the core affordability challenge, explaining why housing activity has slowed despite stabilizing rates.
Mortgage Rate Forecasts: Most major forecasts expect rates to remain largely flat in 2026, with selective sub-6% windows rather than a sustained downward trend.
Affordability (At the Margins): Affordability is improving incrementally through slower price growth and wage gains, but remains uneven and constrained by structural factors.
Featured Financing Solution: Bank statement loans now allow qualification with as little as one year of self-employment, expanding options for borrowers with non-traditional income.
| | | | |
| |
|
As 2025 comes to a close, I wish you happy holidays and good vibes as you head into the new year. I've received so much positive feedback from those of you who've engaged with this newsletter over the years. It means a lot.
Even if one insight helps you make a distinction for your business or life...it's worth it!
That's why I keep writing these.
Since our last update, mortgage rates have remained relatively stable. The national average was sitting at 6.26% and today we are at 6.22%, bouncing up and down for several weeks, even after the recent Fed cut and a better-than-expected inflation report and slightly. While the day-to-day movement has been modest, the bigger picture matters more: rates are meaningfully better than they were a year ago, when the national average sat around 7.14%.
The housing market is transitioning from crisis management
to systems management.
| |
- Inflation is breaking
- Rates are stabilizing
- Policy frictions are exposed
- Life-driven demand is restarting
- Execution quality now matters more than macro timing
This is not a hype market
This is a professional’s market
As professionals in this market, it’s important that we don’t ignore one critical reality: affordability. When you look at long-term data, like the price-to-income ratio shown in the infographic below, it’s clear that housing affordability is more stretched than it’s ever been. This isn’t a short-term issue tied to one rate cycle; it’s a structural challenge that requires thoughtful planning.
That’s why patience, awareness, and adaptability matter more than ever. Staying in tune with the market and being proactive, not reactive, allows us to help people create realistic, sustainable plans that lead to better, more affordable decisions over time. Strategy, not speculation, is what ultimately sets people up for long-term success in today’s housing environment.
| | | | |
| |
| |
📉 Rates: Stable, Stubborn, but Slowly Improving
Mortgage rates remain stuck in a narrow band around the low-6% range, despite multiple Fed cuts.
Why?
- Mortgage rates follow inflation expectations and bond markets, not the Fed Funds rate directly.
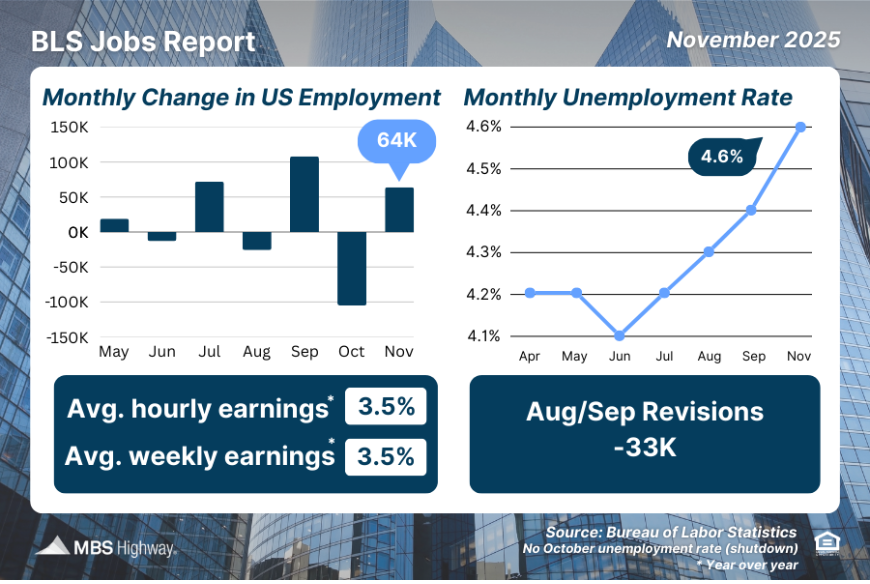
- The Fed is not panicking about jobs data — unemployment at 4.6% is acceptable as long as jobless claims don’t spike.
- Wage growth has cooled, which is exactly what the Fed wanted.
Rate Forecasts
- Most major forecasts (MBA, Redfin, Realtor.com, Wells Fargo) expect flat rates in 2026
- A growing minority (Fannie Mae, HousingWire, Barry Habib, independent economists) sees select sub-6% windows
- Expect volatility inside a flat year, not a straight-line drop
| | | | |
🏠 Inventory & Demand: Life Is Restarting the Market
The biggest shift isn’t macro...it’s human.
Life events are reasserting control
- Marriage, divorce, kids, relocation, downsizing
- ~4 million “missing” transactions from delayed moves
- 52 million Americans now in their 30s
Market reality
- No flood of listings
- No collapse in prices
- More movement, more balance, more negotiation — locally
| | | | |
💸 Affordability Is Improving — But Only at the Margins
Almost every source acknowledges improvement, followed immediately by a caveat.
How often it shows up: Very frequently
- Wages finally outpacing price growth
- Slower home appreciation
- Modest relief from rates
But…
- Improvements are uneven by region
- First-time buyers are still historically constrained
- Policy structures haven’t caught up to price realities
| | | | |
|
Quote to Ponder
"If you focus on the known, you get the known. If you focus on the unknown, you create a possibility."
| | | | |
| |
Featured Financing Solution | | | | |
|
Bank Statement Loans - 1 Year of Self Employment
✅ Bank statement loans allow borrowers to qualify using bank statements for income verification rather than traditional income documents like W-2s and tax returns.
✅ Up to 90% LTV and the down payment can all be a gift.
✅ Minimum FICO 620.
✅ One Year of self employment if previously W-2 in the same line of work.
| | | | |
| |
| |
| |
| |
Recent Real Estate and Economic News | | | | |
Mortgage Rates Near Lowest Levels Since October | Officially, there were 2 days at the end of November where the average lender's 30yr fixed rates were just a hair lower (0.02% difference). Otherwise, today's rates would be the lowest since lat... | | | | | | |
| |
Redfin says pending home sales post steepest drop in 11 months | High rates and holiday caution kept buyers and sellers on the sidelines | | | | | | |
| |
Purchase Applications Fell Last Week in Keeping With Seasonal Patterns - MortgageOrb | Total mortgage application volume fell 3.8% last week, as rates increased, according to the Mortgage Bankers Association's (MBA) Weekly Applications Survey. For the week ended December 12, applications for refinances decreased 4% compared with the previous week but were up 86% compared with the same week one year ago. | | | | | | |
| |
| |
|
Joe Jacobs
Mortgage Broker/Owner
1101 College Ave, Ste 215
Santa Rosa, CA 95404
(707) 696 6937
joe@intentionfinancial.net
NMLS 453314
| | | | |
| |