|
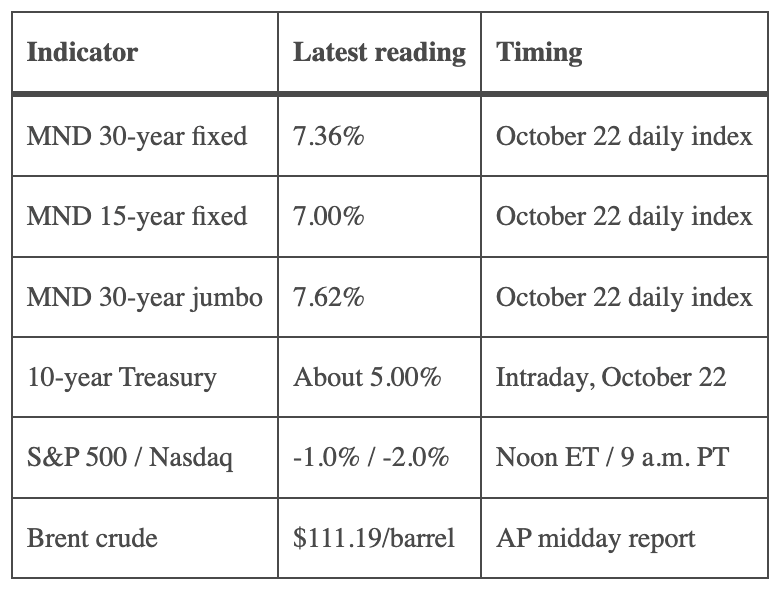
MND's daily 30-year index is down 0.04 percentage point versus Wednesday's final reading. AP reports technology-led stock weakness alongside buying of safer Treasuries. Oil rose 2.2%. Market readings are snapshots, not closing prices.
Why It's Happening
Investors can worry about inflation and seek safety at the same time. Buying bonds pushes their prices higher and yields lower. That can help mortgage pricing even on a day when rising energy costs complicate the inflation outlook.
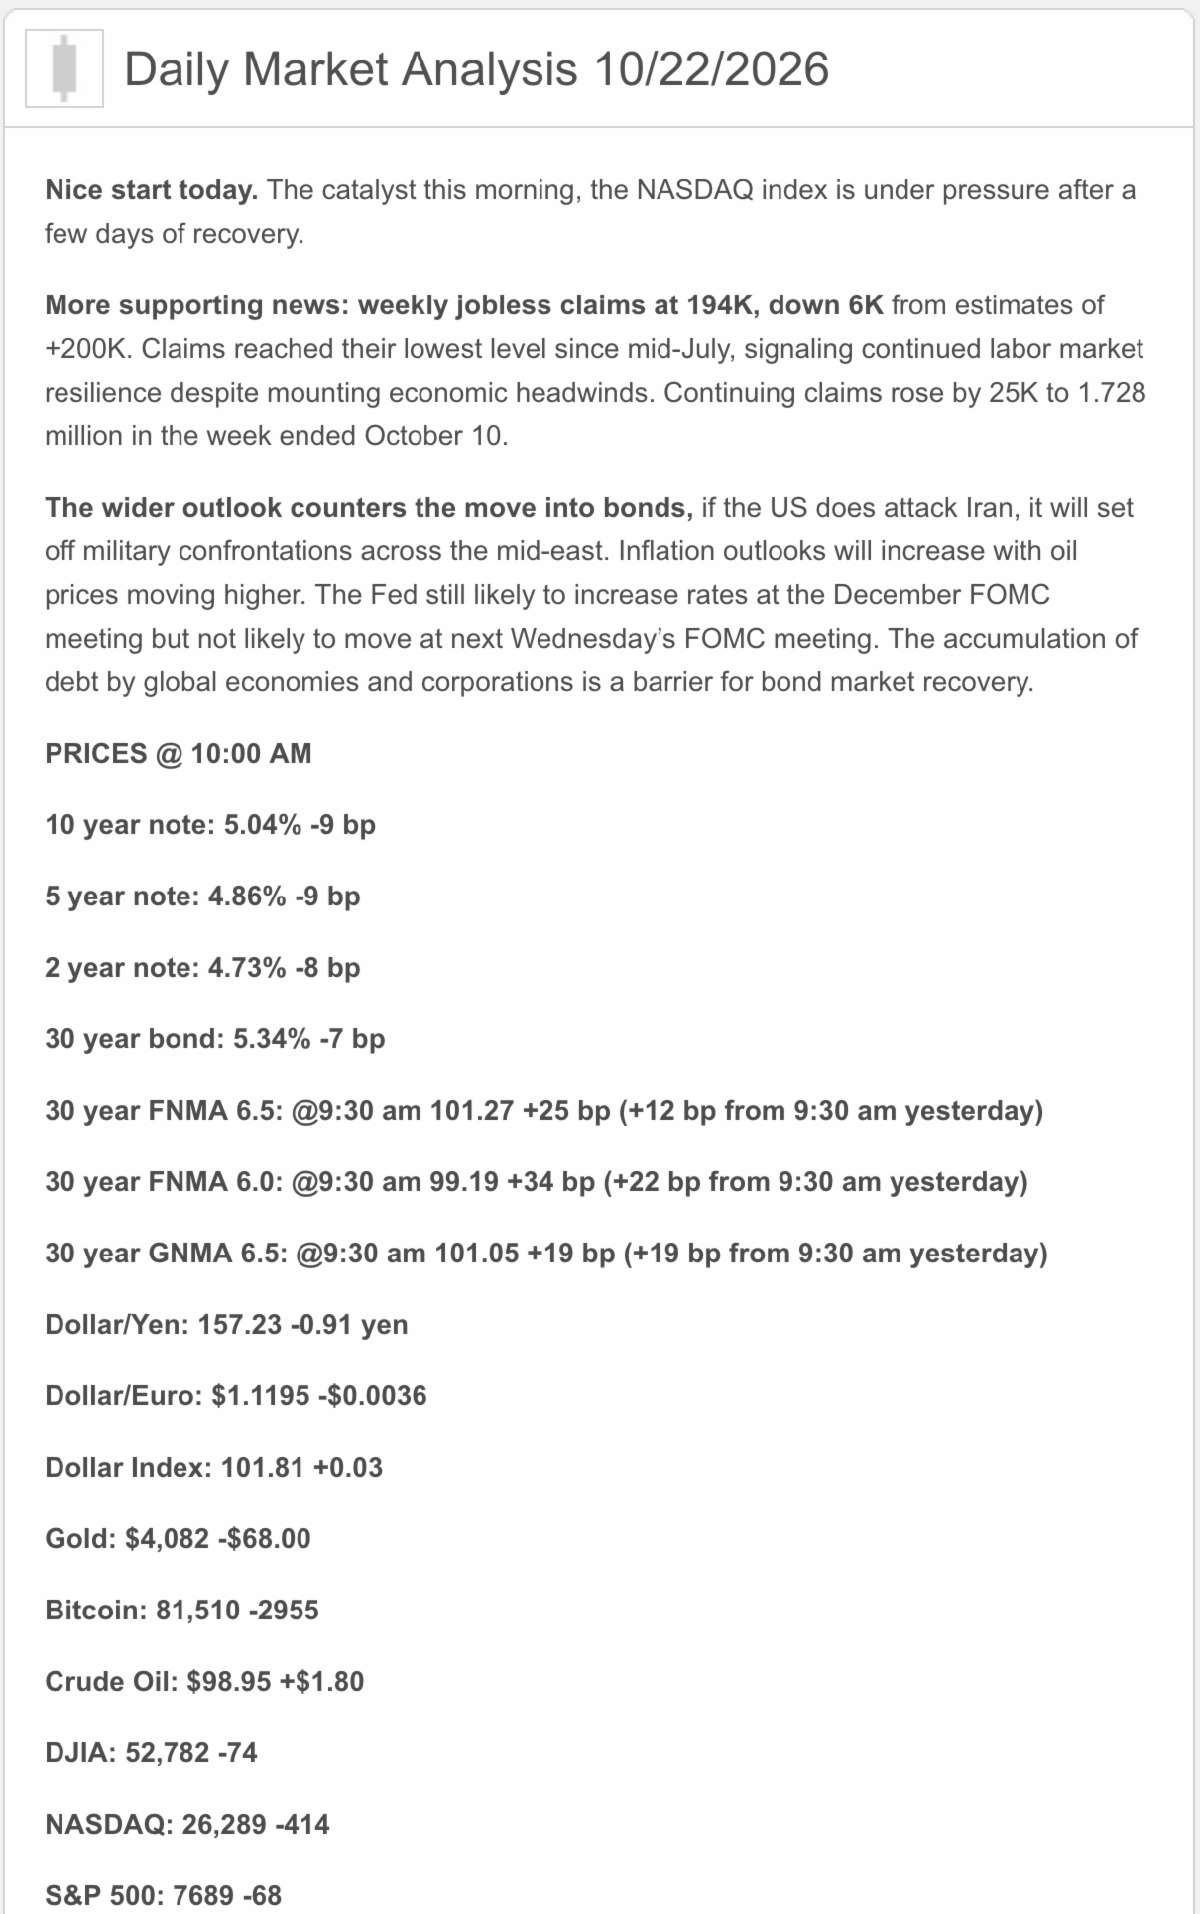
MND's intraday UMBS 6.0 display showed 99.35, up 0.50 price point. These mortgage-backed securities are more directly connected to mortgage pricing than the 10-year Treasury alone. Exact timestamp was not supplied.
Economy: Low Layoffs, Mixed Signals
Initial unemployment claims fell 6,000 to 194,000 for the week ended October 17. Continuing claims rose 25,000 to 1.728 million for the week ended October 10.
My read: employers are holding on to workers, while the rise in continuing claims warrants watching. Low layoffs do not automatically mean easy job hunting—or an imminent Fed rate cut.
Housing: Thursday's Weekly Rate Check
Freddie Mac's newly released 30-year average is 7.32%, down from 7.40%; its 15-year average is 6.68%. This weekly survey covers the prior Thursday through Wednesday, so it differs from today's MND index.
For buyers, the useful question is whether updated pricing meaningfully improves the payment and cash-to-close plan.
Political Backdrop
Reuters reports bipartisan congressional pushback against President Trump's easing of Russia sanctions. Defense and spending legislation after the November 3 election could become a battleground over that policy.
My takeaway: energy policy and geopolitical uncertainty remain relevant to household costs and market volatility. Political headlines are a reason to prepare, not a dependable rate forecast.
What It Means / Lock vs. Float
-
Buyers and agents: Refresh payment worksheets and compare eligible seller credits with a price reduction.
-
Homeowners: Evaluate refinance savings after costs and your expected holding period.
-
Closing within 15–30 days: Maintain a modest lock bias when the payment works. A better bond market is an opportunity to review pricing.
-
More time available: Floating can be reasonable with budget flexibility and a clear lock trigger.
Today's opportunity: use improved pricing to strengthen the plan. Catching the exact bottom remains an unpaid, full-time job.
National rate benchmarks are informational, not personalized offers. Actual pricing depends on credit, equity, loan terms and points.
|