Greetings!

As real estate professionals, we spend a lot of time helping buyers separate market headlines from market reality. Whenever political headlines like the midterm elections collide with fresh macroeconomic prints like the latest U.S. jobs report, our clients naturally wonder what it all means for interest rates and home affordability.


Here is how I am breaking down the current environment for our team at Noble Home Loans, along with the actionable strategies we need to deploy together to keep transactions moving forward. I wanted to share with you today so you can pass along to your team as needed.


Understanding the Short-Term Rate Environment


To set clear expectations with prospective buyers, we need to look past the political commentary and focus directly on the underlying market drivers:


  • The Midterm Election Effect: While political shifts generate heavy news coverage, elections themselves rarely dictate daily mortgage rate movements. What capital markets actually monitor are fiscal policy implications—specifically government spending, deficit forecasts, and Treasury debt issuance. As Congressional dynamics shift, bond markets go through a routine adjustment period, re-pricing yield expectations based on projected fiscal policy rather than political outcomes.
  • The Jobs Report & Inflation Mechanics: Macroeconomic data remains the primary engine driving bond yields. Strong payroll data and sustained wage growth demonstrate economic resilience, but they also apply upward pressure on the 10-Year Treasury yield. When employment numbers beat expectations, bond yields firm up, temporarily limiting any rapid downward momentum in mortgage rates.
  • The Bottom Line for Rates: We remain in a range-bound rate environment. Modest dips in mortgage rates can quickly be offset by resilient economic data. Advising buyers to "wait out the market" for a dramatic drop is not a dependable strategy; helping them take control of their actual monthly payment today is where the real value lies.


Our Action Plan for Real Estate Partners


Instead of trying to time macro market cycles, our joint strategy must focus on structuring deals that solve payment sensitivity directly.


  1. Shift the Conversation to Payment Control: Reframe buyer discussions around total monthly outlay rather than just the headline note rate.
  2. Use Concessions Productively: Show sellers how offering financing concessions attracts active buyers far more effectively than standard price cuts.
  3. Protect Shopping Windows: Deploy upfront rate lock programs so pre-approved buyers can view inventory without worrying about short-term yield volatility.


Key Short-Term Programs to Deploy Today


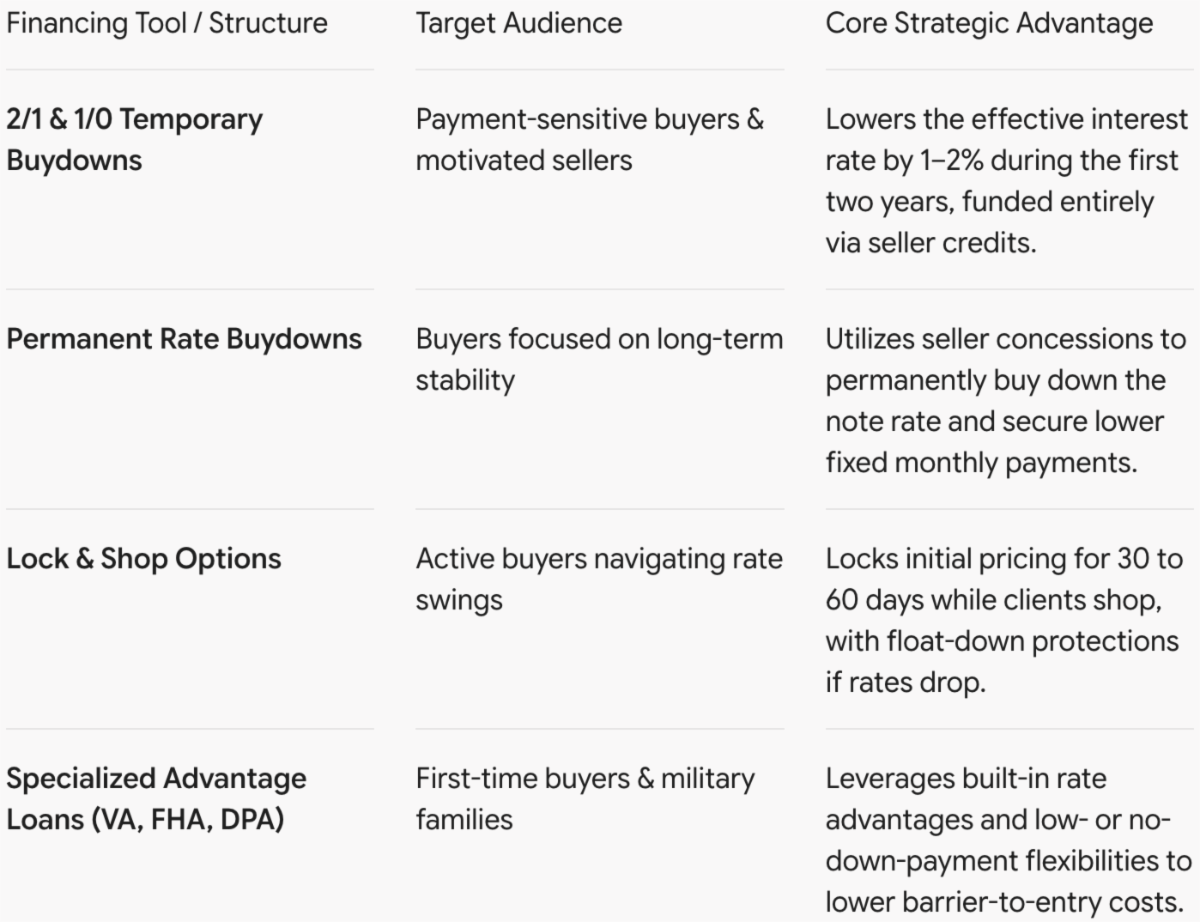
Here are the specific loan structures we are using right now to lower monthly obligations for buyers while keeping sellers satisfied:

How We Plan for These Changes Today


At Noble Home Loans, we are actively supporting our real estate partners with tools designed to close pipeline gaps immediately:


  • Single-Page Multi-Option Side-by-Sides: We provide clean, single-page presentation layouts that compare standard price reductions directly against temporary and permanent rate buydowns. These visual side-by-sides give your sellers clear proof of how concessions preserve their net proceeds while offering buyers significant payment relief.
  • Co-Marketing Outreach: We assist in formatting structured digital communications—using clean client presentation layouts—to educate database contacts on current payment-reduction opportunities.
  • Proactive Pipeline Audits: Our team is reviewing existing pre-approvals to recalibrate purchasing power against shifting Treasury yields and mortgage-backed security spreads, ensuring your active shoppers remain fully qualified.


Don't Forget The December Fed Meeting...

The surprisingly strong October jobs report increased the likelihood of a December Federal Reserve rate hike by signaling that the labor market remains tight and resilient, which can fuel persistent inflationary pressures.Nonfarm payrolls surged by 165,000—more than double expectations—while the unemployment rate edged down to 4.1% and monthly wage growth accelerated to 0.4%.


Robust job growth combined with accelerating wages increases consumer spending power and raises labor costs for businesses, amplifying concerns that inflation could stay above the Fed’s target. Because a sturdy employment sector gives central bankers greater confidence that the economy can absorb higher borrowing costs without triggering a sharp downturn, financial markets quickly repriced the odds of a quarter-point December hike upward. We need to keep that in mind now and prepare accordingly.

Time Is of the Essence


Navigating shifting rate environment cycles requires clear data and practical structuring. I’d welcome the chance to grab coffee and review your current listings, build custom side-by-side buydown sheets for your sellers, or map out co-branded strategies for your active buyer pipeline.


Relying on experienced field experts, brokers, agents, and loan officers working in lockstep, is the single best path to helping clients make informed, confident decisions. As you know, I carefully track these diverging market dynamics so you always have the real-time data, custom loan structures, and co-marketing support needed to educate your database and close more deals. Let’s turn today's market challenges into closed transactions, before the Fed meets in December..


Reach out anytime to review custom financing strategies for your buyers, run hyper-local scenario reports, or schedule a strategy session for your team! I am always here to add value to your day.

Team Noble offers the Rate Guard Protection Program, 2-1 buy downs and other loans designed to help today's homebuyers.


Together, we can help people make informed decisions and become advisors for life. Call me anytime you or your clients have questions. We'll go over different scenarios to help them get into their new home faster.

Please remain safe, stay healthy, and make today great!


Best Regards From Your Hometown Lender,

Brad Malkin, President | NMLS #100539

Noble Home Loans | NMLS #328275

O: 702.932.7503 | M: 702.279.9111

E: brad.malkin@noblehomeloans.com

W: noblehomeloans.com