|
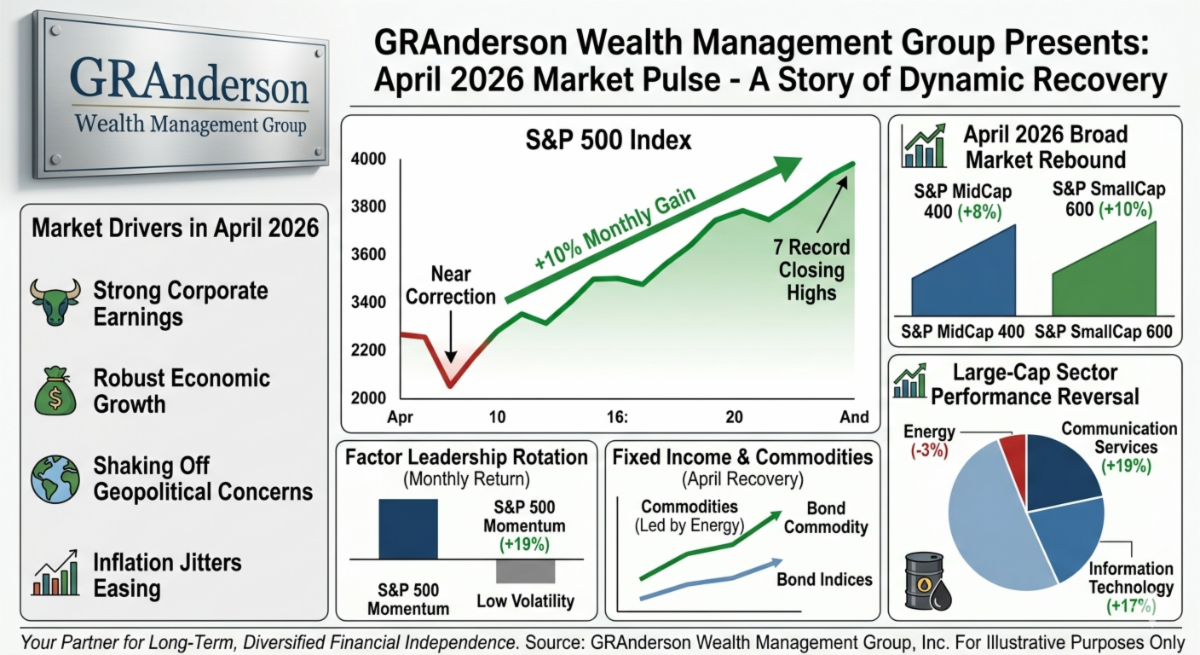
The April rally represented a healthy broadening of the market. Rather than relying solely on the mega-cap tech stocks that dominated the first quarter, the upside extended to mid-size and smaller companies. The S&P MidCap 400® (+8%) and S&P SmallCap 600® (+10%) demonstrated that investor confidence and economic optimism are flowing through the broader economy, signaling that smaller businesses are successfully navigating current interest rate environments.
Leadership among large-cap sectors experienced a distinct shift. The first quarter's laggards became April’s leaders as Communication Services and Information Technology surged 19% and 17%, respectively. This sharp reversal was primarily fueled by strong corporate earnings reports and positive forward guidance from major tech and media companies. Conversely, the S&P 500 Energy sector declined by 3%, taking a temporary step back as oil price fluctuations and sector-specific valuations stabilized after a strong performance run earlier in the year.
The shift in factor leadership highlights a distinct "risk-on" environment. Investors moved aggressively away from defensive, low-volatility strategies and embraced Momentum and High Beta factors. The 19% surge in the S&P 500 Momentum index—the largest since November 2014—shows that market participants are rewarding companies with strong recent price performance, indicating a strong appetite for growth.
See this month's GRAnderson Wealth Management Economic Update for details.
|