|
Monthly Market Update for August 2026: Rising Yields, Strong Earnings, and Trade Uncertainty
September 2026
| | |
Pat McFawn | Financial Advisor - Registered Representative
Dale White | Financial Advisor - Registered Representative
Steve McFawn | Financial Advisor - Registered Representative
| | |
August was another example of the idea that strong markets do not require a picture-perfect backdrop. While there continues to be uncertainty around oil prices, the Fed, new tariffs affecting global trade, and interest rates that are at their highest in decades, many positive factors drove broad market indices higher.
For investors, the key takeaway is that short-term concerns are a normal part of markets. Rather than try to navigate each challenge, history shows that portfolios built around long-term goals are the best way to increase the probability of financial success. With this in mind, what drove markets in August, and what should investors keep in mind as they look ahead?
Key Market and Economic Drivers in August
- The S&P 500, Nasdaq, and Dow Jones Industrial Average rose 2.6%, 3.9%, and 1.3%, respectively, in August. Year-to-date, they have gained 12.3%, 13.5%, and 10.7%, respectively.
- Volatility, as measured by the CBOE VIX index, dropped below the long-term average, ending the month at 16 after climbing as high as 21 the previous month.
- International developed markets returned 1.8% based on the MSCI EAFE Index in U.S. dollar terms, while emerging markets returned 3.2% based on the MSCI EM Index.
- The 30-year Treasury yield reached its highest level since 2007, closing the month at 5.24%. The 10-year Treasury yield ended the month at 4.75%. The Bloomberg U.S. Aggregate Bond Index returned 0.4% for the month.
- Oil prices hovered in a range in August after climbing the previous month. Brent crude closed the month at $90.68 per barrel and WTI near $86.27 per barrel.
- The U.S. Dollar Index fell to 99.43 at the end of August. Gold ended the month at $4,437.38 per ounce while silver rose to $66.58 per ounce.
- The revision to second quarter GDP remained unchanged at an annual rate of 1.5%.
- The July jobs report missed expectations with a decline of -23,000 in payrolls compared to a forecasted gain of 80,000. Unemployment fell slightly to 4.1%.
Long-term yields are near multi-decade highs
| | |
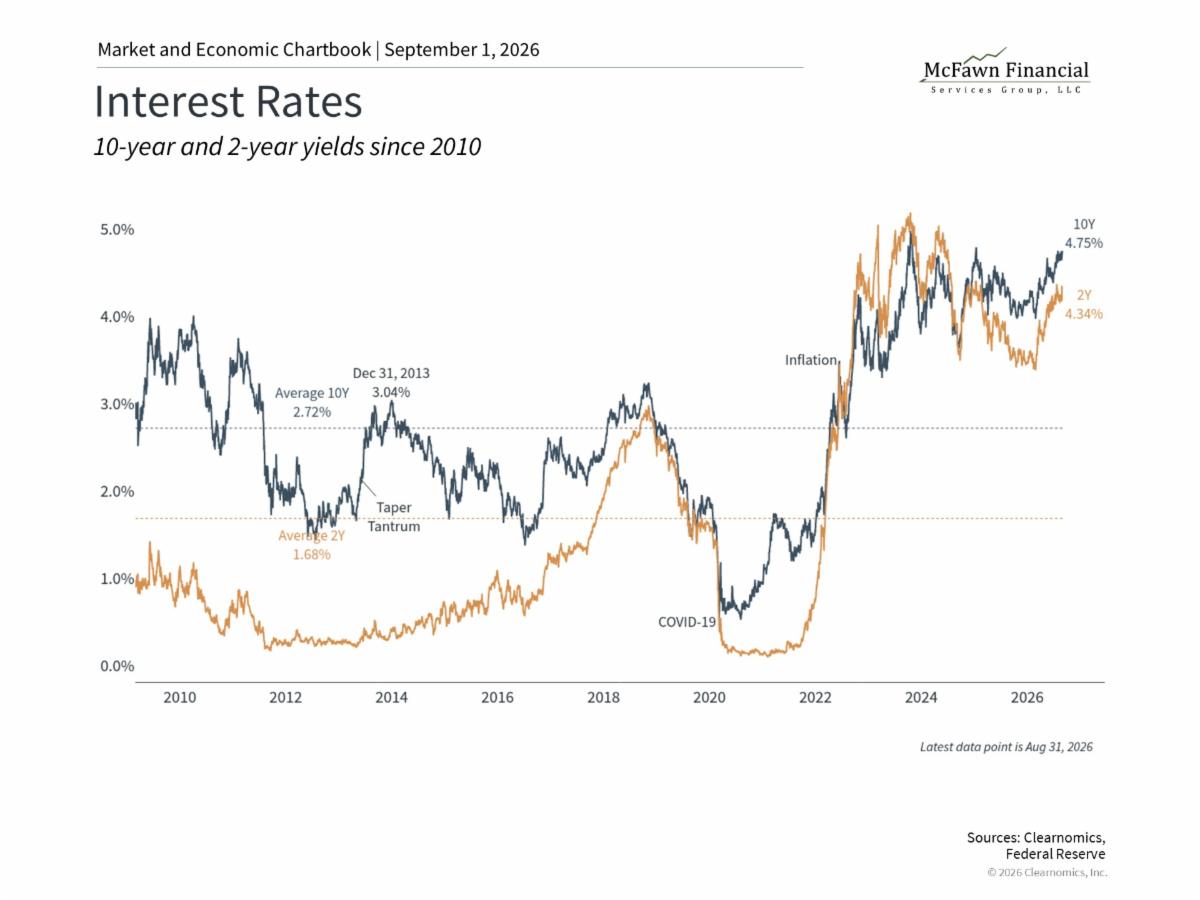
One of the defining features of today's investment environment is that interest rates have remained higher than many expected. The 30-year Treasury yield briefly surpassed 5.3% in August, a level not seen in almost 20 years. Similarly, the 10-year Treasury yield, around 4.8%, is close to its recent peak.1 This is important because, while interest rates can seem technical, they both affect and are a reflection of the economy.
Typically, higher rates are viewed as being negative for markets, but the key is that interest rates can rise for different reasons. While inflation drove rates higher over the past several years, more recent rate increases have occurred because “real yields” have improved. This is another way to say that inflation-adjusted yields are higher, reflecting the fact that the economy continues to be healthy, especially due to strong corporate earnings. In the long run, this is a positive signal for the overall health of the market, which is why interest rates and the stock market are near their peaks at the same time.
Looking forward, higher rates can also be positive for long-term investors because they create income opportunities across bond holdings. Of course, rising interest rates also weigh on the prices of existing bonds. This has caused major bond indices, such as the Bloomberg U.S. Aggregate Bond Index, to remain flat this year. So, it’s important to interpret rising rates in the context of a well-balanced portfolio and relative to financial goals.
That said, inflation still remains higher than consumers and policymakers would like. The headline Personal Consumption Expenditures Price Index, for example, showed that inflation stood at 3.7% year-over-year in July, while core PCE rose 3.3%, both well above the Fed's 2% target.2 At the Fed's annual Jackson Hole symposium in late August, Fed Chair Kevin Warsh signaled that a rate hike could arrive sooner. For this reason, markets are now pricing in at least one rate hike this year, and possibly two by early next year.3
Corporate earnings are delivering broad-based growth
| | |
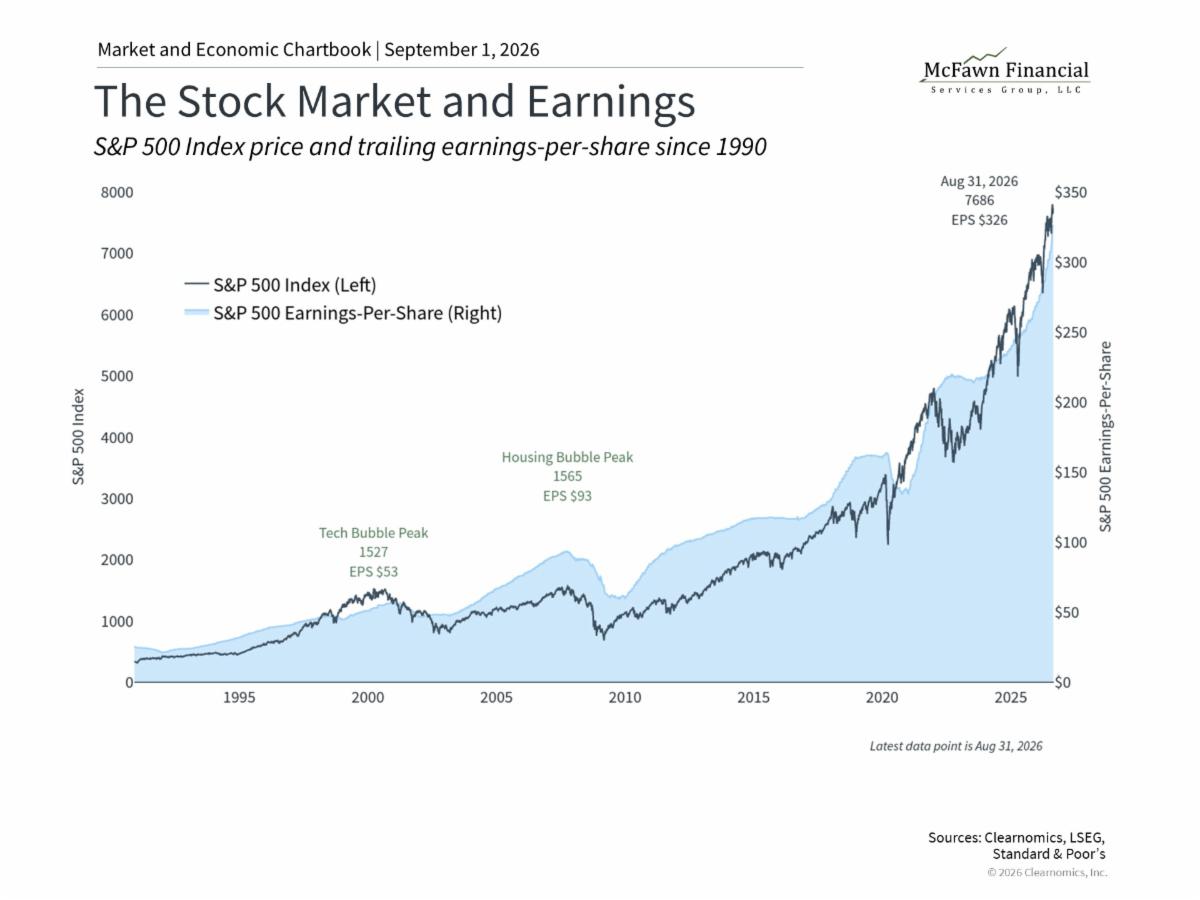
The S&P 500 reached new all-time highs in August, driven largely by strong corporate earnings. Results for the second quarter have come in well above expectations across a wide range of sectors, and consensus estimates now anticipate S&P 500 earnings to reach $349 per share at the end of the year. These same forecasts expect earnings-per-share growth of 15% each of the next two years as well, above the historical average of 7%.4
While these forecasts can change, they reflect growth driven by AI infrastructure buildouts, higher oil prices, and healthy growth across sectors. Specifically, ten of the eleven S&P 500 sectors reported year-over-year earnings growth, with nine reporting double-digit percentage gains. This breadth of earnings growth suggests that the overall economy, not just a narrow group of large companies, is contributing to corporate profitability.5
Strong corporate earnings are one reason that broad stock market valuations have remained steady over the past year. The S&P 500 price-to-earnings ratio has hovered around 20x, which is well above the historical average of 16x, but an improvement from recent peaks. While valuations do not predict what the market will do in the short run, they are important guides to allocating assets in the long run. In an environment of higher valuations, it’s important to stay balanced across sectors, asset classes, and geographies.
Trade tensions are still a source of uncertainty
| | |
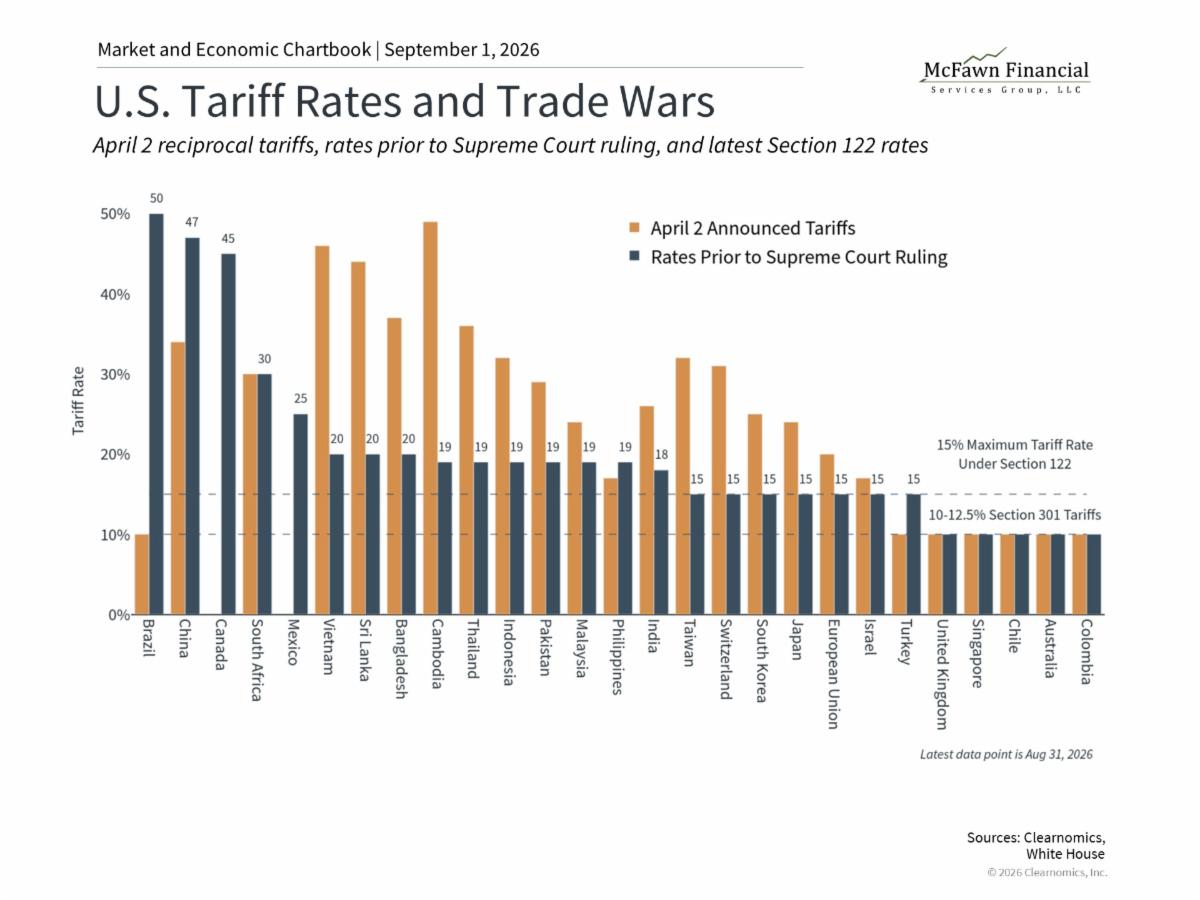
Trade policy returned to the headlines in August as tensions with key trading partners such as Canada escalated. After last year’s “Liberation Day” tariffs were ruled to be illegal by the Supreme Court in February, new tariffs were implemented under different laws such as Section 301 of the Trade Act of 1974. However, those tariffs have now expired, so new ones have been implemented in their place under different trade laws, each with their own set of rules. At the same time, the government is now refunding the original “reciprocal tariffs” to businesses, with $129 billion already accepted for processing by U.S. Customs and Border Protection.6
As has been the case since early last year, the worst-case outcomes that many investors and economists feared have not occurred. This is largely because companies have adapted their supply chains, adjusted pricing strategies, and managed costs in reaction to these tariffs, muting the effect on inflation from higher intermediate prices. Still, tariffs will likely remain a source of uncertainty for global markets in the coming years.
The bottom line? August demonstrated the importance of staying balanced and not overreacting to headlines. Despite periods of volatility, strong corporate earnings and attractive bond yields continue to support long-term portfolios.
| |
References
1. https://home.treasury.gov/policy-issues/financing-the-government/interest-rate-statistics
2. https://www.bea.gov/news/2026/personal-income-and-outlays-july-2026
3. https://www.cmegroup.com/markets/interest-rates/cme-fedwatch-tool.html
4. Clearnomics research and LSEG data as of August 31, 2026
5. https://insight.factset.com/sp-500-earnings-season-update-august-7-2026
6. https://www.cbp.gov/trade/programs-administration/trade-remedies/ieepa-duty-refunds
Index Descriptions
S&P 500
The Standard & Poor’s 500 Index is a capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries.
Dow Jones
The Dow Jones Industrial Average consists of 30 stocks that are major factors in their industries and widely held by individuals and institutional investors.
NASDAQ
The NASDAQ Composite Index measures all NASDAQ domestic and non-U.S. based common stocks listed on The NASDAQ Stock Market. The market value, the last sale price multiplied by total shares outstanding, is calculated throughout the trading day, and is related to the total value of the Index.
MSCI Emerging Markets Index
The MSCI EM (Emerging Markets) Index is a free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of the emerging market countries of the Americas, Europe, the Middle East, Africa and Asia. The MSCI EM Index consists of the following emerging market country indices: Brazil, Chile, Colombia, Mexico, Peru, Czech Republic, Egypt, Greece, Hungary, Poland, Qatar, Russia, South Africa, Turkey, United Arab Emirates, China, India, Indonesia, Korea, Malaysia, Philippines, Taiwan, and Thailand.
MSCI EAFE Index
The MSCI EAFE Index is a free float-adjusted market capitalization index that is designed to measure the equity market performance of developed markets, excluding the US & Canada. The MSCI EAFE Index consists of the following developed country indices: Australia, Austria, Belgium, Denmark, Finland, France, Germany, Hong Kong, Ireland, Israel, Italy, Japan, the Netherlands, New Zealand, Norway, Portugal, Singapore, Spain, Sweden, Switzerland and the UK.
Bloomberg US Aggregate Bond Index
The Bloomberg U.S. Aggregate Bond Index is an index of the U.S. investment-grade fixed-rate bond market, including both government and corporate bonds.
DXY
The DXY is a U.S. dollar index based on a basket of currencies, including the Euro, Yen, Pound, Canadian Dollar, Swedish Krona and Swiss Franc.
| | The information contained in this report does not purport to be a complete description of the securities, markets, or developments referred to in this material. | | |
As always, if you have any questions, please do not hesitate to call us at (248) 619-0090.
This information, developed by an independent third party, Clearnomics, has been obtained from sources considered to be reliable, but Raymond James Financial Services, Inc. does not guarantee that the foregoing material is accurate or complete. This information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. The information contained in this report does not purport to be a complete description of the securities, markets, or developments referred to in this material. This information is not intended as a solicitation or an offer to buy or sell any security referred to herein. Investments mentioned may not be suitable for all investors. The material is general in nature. Past performance may not be indicative of future results. Raymond James Financial Services, Inc. does not provide advice on tax, legal or mortgage issues. These matters should be discussed with the appropriate professional. There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct. Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Bond prices and yields are subject to change based upon market conditions and availability. If bonds are sold prior to maturity, you may receive more or less than your initial investment. Holding bonds to term allows redemption at par value. There is an inverse relationship between interest rate movements and bond prices. Generally, when interest rates rise, bond prices fall and when interest rates fall, bond prices generally rise. Prior to making an investment decision, please consult with your financial advisor about your individual situation. Raymond James is not affiliated with nor sponsors or endorses Clearnomics or any of the aforementioned organizations.
Leading Economic Indicators are selected economic statistics that have proven valuable as a group in estimating the direction and magnitude of economic change. The S&P 500 is an unmanaged index of 500 widely held stocks that is generally considered representative of the U.S. stock market. Inclusion of this index is for illustrative purposes only. Keep in mind that individuals cannot invest directly in any index, and index performance does not include transactions costs or other fees, which will affect actual investment performance.
The Bloomberg U.S. Aggregate Bond Index is a broad-based benchmark that measures the investment-grade, U.S. dollar-denominated, fixed-rate taxable bond market. The MSCI EAFE Index represents the performance of developed markets outside of the U.S. and Canada (Europe, Australasia, and the Far East). The MSCI Emerging Markets Index captures large and mid-cap representation across 24 Emerging Market (EM) countries. The U.S. Dollar Index measures the value of the U.S. dollar relative to a basket of foreign currencies. The Consumer Price Index (CPI) measures the average change over time in the prices paid by urban consumers for a basket of goods and services. It is one of the most widely used indicators for inflation.
| | |
Securities offered through Raymond James Financial Services, Inc. member FINRA/SIPC. Investment advisory services are offered through Raymond James Financial Services Advisors, Inc. McFawn Financial Services Group, LLC is not a registered broker/dealer and is independent of Raymond James Financial Services.
The Dow Jones Industrial Average (DJIA), commonly known as “The Dow” is an index representing 30 stock of companies maintained and reviewed by the editors of the Wall Street Journal.
The Russell 2000 Index measures the performance of the 2,000 smallest companies in the Russell 3000 Index, which represent approximately 8% of the total market capitalization of the Russell 3000 Index.
Bitcoin issuers are not registered with the SEC, and the bitcoin marketplace is currently unregulated. Bitcoin and other cryptocurrencies are a very speculative investment and involves a high degree of risk.
Investing in commodities is generally considered speculative because of the significant potential for investment loss. Their markets are likely to be volatile and there may be sharp price fluctuations even during periods when prices overall are rising.
Gold is subject to the special risks associated with investing in precious metals, including but not limited to: price may be subject to wide fluctuation; the market is relatively limited; the sources are concentrated in countries that have the potential for instability; and the market is unregulated.
Please visit https://www.raymondjames.com/legal-disclosures/social-media-disclaimer-icd for Additional Risk and Disclosure Information. Raymond James does not accept private client orders or account instructions by email. This email: (a) is not an official transaction confirmation or account statement; (b) is not an offer, solicitation, or recommendation to transact in any security; (c) is intended only for the addressee; and (d) may not be retransmitted to, or used by, any other party. This email may contain confidential or privileged information; please delete immediately if you are not the intended recipient. Raymond James monitors emails and may be required by law orregulation to disclose emails to third parties.
Investment products are: Not deposits. Not FDIC or NCUA insured. Not guaranteed by the financial institution. Subject to risk. May lose value.
This may constitute a commercial email message under the CAN-SPAM Act of 2003. If you do not wish to receive marketing or advertising related email messages from us, please reply to this message with "unsubscribe" in your response. You will continue to receive emails from us related to servicing your account(s).
| | | | |