|
| |
|
Lincoln's TermAccel and LincXpress
|
|
Join us
Tuesday, October 11th, 9am PST
for a 30-minute discussion
on Lincoln's TermAccel and LincXpress programs. We will be joined by Jen Burns and Deb Garcia from Lincoln.
The LincXpress Tele-App process offers the opportunity to waive labs for qualifying clients.* That means faster policy issue and a less invasive, easier process for your clients.
Call In #: 888.764.3633
Access Code: 3489003
Click here for additional information.
|
|
|
Underwriting Approvals in 2 days WITHOUT Exams!
|
|
Join us
Thursday, October 20th, 9am PST
for a 30-minute discussion
on John Hancock's revolutionary underwriting process - providing approvals in as little as 2 days! We will be joined by Mike Bellig, National Account VP.
Call In #: 866.578.0783
Meeting Number: 632 498 571
Access Code: JH2016
Click here for a 1 minute teaser video.
|
|
|
AFG Brokerage Announcements
|
|
|
New and Improved Website AND App Coming SOON!
|
|
|
We are excited to announce that in the coming weeks our website, www.afgbrokerage.com will be completely revamped in the coming weeks. We will also be introducing an app for your ios or Android device. Stay tuned for more news!
|
|
|
Have you ever had a client express the need for estate protection, but is unwilling to fully fund a second to die life insurance policy? Zurich has your solution!
Below are 2 illustrations giving your clients affordable options to purchase the coverage they need now while protecting their insurability for the future. We have seen the most traction with this on clients ages 40-60 who may be paying large premiums already on their parent's estate policy leaving them unable to make the required premium payments on a policy for them.
Example
Husband and wife age 50 with a need for $10M of estate life insurance. A fully funded SUL policy would require an annual premium of $62,810. With Zurich you can show your clients 2 additional options:
Option 1: 10 year guaranteed premium. $13,003 annually.
In this example the target premium on either the full pay OR the 2 additional options is $90,723. And with lifetime rolling targets, Zurich makes sure you get paid regardless of the funding choice your clients make!
Reach out to us today for additional details of how you can apply this idea in your practice.
|
|
|
Pension Maximization Opportunities
|
|
|
How to properly design pension maximization cases. During this call we covered:
- How the Pension Max Concept Works
- Pinpoint which Products Work Best
- Insider Tips to Make Your Next Sale!
View a brief video short 2 minute video on Pension Maximization here.
|
|
|
|
Field Underwriting and Cheat Sheets
|
|
|
The Underwriting Services department just audited and updated the underwriting resource library for use on your Q4 cases. Stay on the "straight and narrow" by making sure you are using the most up to date Field Underwriting Guides from the AFGB Partners along with the latest "Cheat Sheets" covering a broad selection of the most common "dings and dents" in a client's medical history.
Field Underwriting Guides
In some cases, there is a clear-cut answer to an underwriting question, and you can find most of those answers in the Core Carrier Field Underwriting Guides listed below. Not sure that the answer to your questions is definitive? Give the AFGB Underwriting Services Team a call, or submit your question via email using the dedicated email inbox:
underwriting@afgbrokerage.com.
What’s included in these Field Underwriting Guides? All of the publicly available information regarding Age and Amount Requirements, Approved Vendors, Preferred Guidelines, Build Charts, and insight into how the Core Carrier views certain medical conditions.
Underwriting Guideline Cheat Sheets
Need a quick answer to how a wide cross section of insurance companies view a specific aspect of a client’s medical, personal or lifestyle history? This collection of Underwriting Cheat Sheets contain clear answers to straightforward questions that we all face on a day in, day out basis. Of course, when you have a unique situation that is not covered by these Cheat Sheets, the AFGB Underwriting Services Team is ready to step in and provide some insight on the more nuanced situation. Reach out to them by phone, or via email at
underwriting@afgbrokerage.com.
|
|
|
Don't Miss Getting Your Standard Clients a Preferred Rate!
|
|
Global Atlantic recently announced a Q4 upgrade program that can automatically take your standard or better clients up one underwriting class. The question that really matters is what this program could mean for your next case? AFGB dug into WinFlex and dialed in some designs to show how this program can deliver huge value from two perspectives: An untouchable price point or a massive advantage in long-term performance that can prevent the IRR degradation that comes with hyper-longevity. Check out the details below.
If you want to see the life insurance industry at its most creative, just look to the 4th quarter as we all push to hit sales goals before the calendar flips. The recently announced upgrade program from Global Atlantic
is a huge opportunity to win cases by delivering a price point that is likely out of reach with a more traditional approach to both underwriting and case design.
The bottom line is simple: Clients who are "cut and dried" risks at Preferred and Standard can access pricing that would normally be far out of reach, so if there's a case that could benefit from a little Q4 creativity, take a look at Global Atlantic, the Lifetime Foundation and the recently launched Upgrade Program.
How significant are the savings?
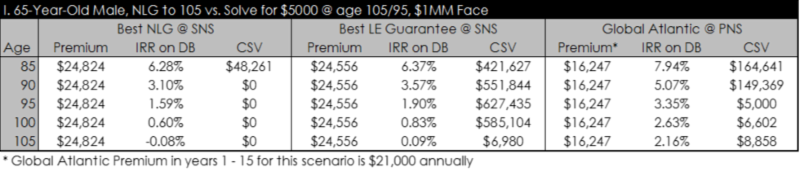
Try IRR's at life expectancy and beyond that are 150 to 200 basis points higher than NLG or even life expectancy guarantee products can offer:
|
|
|
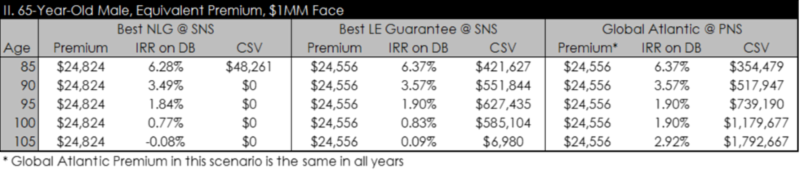
Of course, that's not the only way to look at this program. If, for instance, we simply use an equivalent premium to the other available products, there's a massive cash position and late IRR's that actually increase, perfect for the client that thinks they will live forever:
|
|
|
T
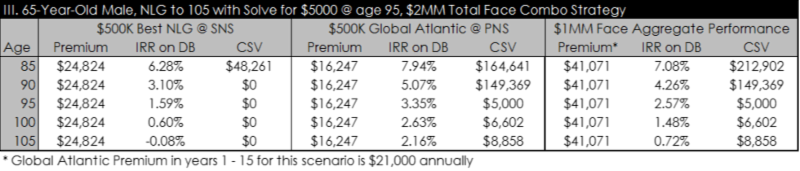
his is such a good deal that it is limited to face amounts of $1MM or less, so for your larger cases, think about giving Global Atlantic the first $1MM. The aggregate performance will still deliver IRR's 70 to 80 basis points higher than a single policy solution:
|
|
|
With savings like this, there has to be a catch, right? The 'trade" here is giving up lifetime guarantees on the full death benefit in exchange for demonstrably superior policy performance.
Call AFG today to quote your next case!
|
|
|
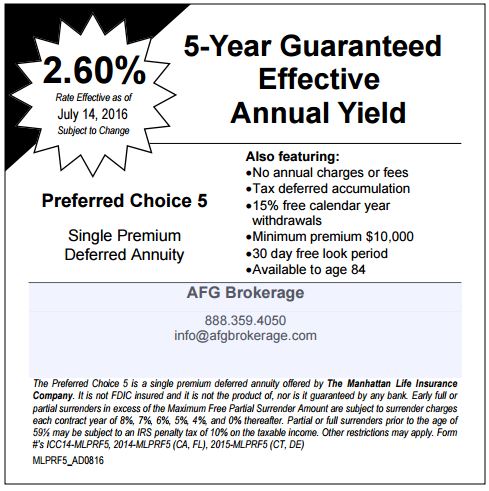
Great Short Term Fixed Annuity Rates!
|
|
|
|
|
Call us today for more information!
|
|
|
Follow us on Social Media!
|
|
|
|
|
|
|
|