|
Fed Watch: September’s Coin Flip
The economy continues to send mixed signals to markets and Federal Reserve policymakers, leaving the path forward from stagnant job growth and above-target inflation unclear.
The July CPI came in as expected, with headline inflation down 0.1 percentage points to 3.4% and core inflation up 0.2 percentage points to 2.5% on a year-over-year basis. June’s headline inflation decline was driven by a short-lived reprieve in oil prices via a 5.7% dip. While inflation remains warm, the labor market is tepid. July nonfarm payrolls declined by 23,000—a downside surprise against an expected 85,000 gain—alongside 100,000 in downward revisions to May and June figures. Although the unemployment rate “improved” to 4.1%, this was again due to a declining labor force participation rate rather than increased hiring.
Economists at major banks disagree on the Fed’s likely path forward, with some predicting hikes and others expecting the Fed to hold steady. CME’s FedWatch tool puts the likelihood of a September rate hike at 64.4%.
Build Now, Bill Later
For the first time on record for non-traded BDCs (business development companies), redemption requests outpaced newly raised capital after bankruptcies tied to alleged fraud and the collapse of a major sector merger. The concerns center on software and technology exposure, where AI-driven disruption is raising questions about previously stable revenue models. Morgan Stanley has estimated that direct lending default rates may climb from 5.6% to 8%, well above the historical average of 2–2.5%.
The Fed’s May Financial Stability Report characterized this risk as limited and manageable but noted that continued redemptions could reduce credit availability for higher-risk borrowers.
Value’s Year, with an Asterisk
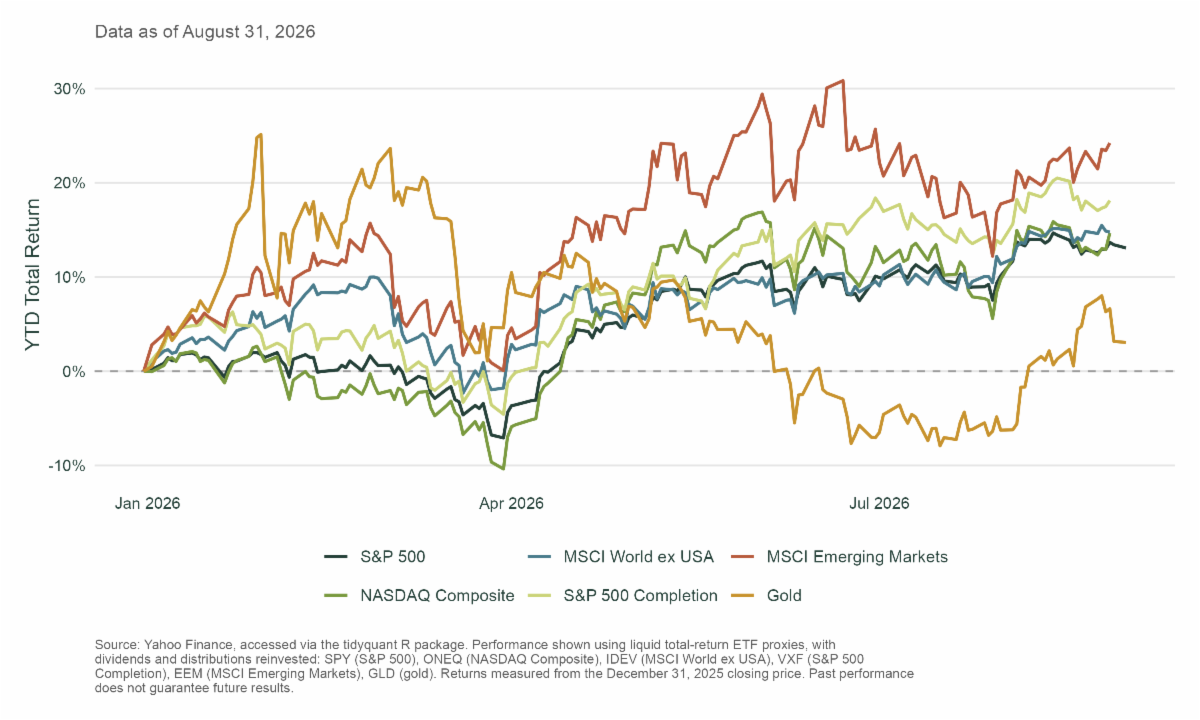
While AI headlines dominated, the Russell 1000 Value Index climbed 21.69% year-to-date against 3.69% for the Russell 1000 Growth Index, marking one of the widest gaps in years. Financials and energy were the strongest sectors pushing returns, helped by strong bank earnings and oil’s 53% run. Value’s shorter-duration profile also holds up better when rates stay elevated. An unexpected inclusion in the index, though, came during June’s Russell reconstitution, where Apple and Microsoft were partially reclassified as Value. Technology now represents 18.6% of the Value index, second only to financials. Buying a Value fund today entails owning more mega-cap tech than investors may realize. The outperformance stands out, but index construction deserves as much attention as the headline gap.
|