For Advisor/Broker Use Only
Not Intended for Distribution to the Public
| |
Indexed universal life persistency risks abound: Don’t repeat the misestimations of the past!
(10 Minute Read)
This article highlights the growing risks associated with indexed universal life (IUL) policies that do not have a secondary guarantee (a.k.a. "No Lapse Guarantee) —many of which are flying completely under the radar of policyowners. As cap rates have declined and index option costs have risen, the actual performance of these policies has begun to significantly lag behind original projections. This gap is especially dangerous in IUL policies that rely on non-guaranteed elements and assumed policy behaviors—such as ongoing premium payments or policy loans—that may no longer be sustainable in today’s environment.
The article warns that declining performance can quietly erode cash value, reduce flexibility, and lead to unexpected lapses or surrenders. In some cases, policyowners may no longer be able to access loans they were counting on or may be forced to inject additional premium just to keep the policy in force. These risks underscore the critical need for regular, detailed performance evaluations of permanent life insurance policies to ensure they are still aligned with expectations—and that the strategy remains viable.
| |
When Planning Software Falls Short: Rethinking Long-Term Care Assumptions
(5 Minute Read)
Most financial planning software uses national, median long-term care (LTC) costs to model future expenses. While that may be adequate for broad planning, it creates a critical blind spot when advising high-net-worth individuals and families for a simple reason: They are unlikely to choose “median” care.
| |
When Emotions Override Planning: The Cost of Declining Insurance After a Spouse's Rejection
(2 Minute Read)
Applying for life insurance or long-term care (LTC) insurance as a married couple is a responsible step toward securing financial stability. However, an all-too-common scenario unfolds when one spouse is declined coverage. The declination is often taken personally, sparking frustration. In solidarity, the insurable spouse may also choose to walk away. This article adds perspective on the true cost of walking away.
| |
12 States With the Highest Average Estate Tax Payments
(5 Minute Read)
A recent analysis by ThinkAdvisor ranks the 12 states with the highest average federal estate tax payments—and the results might surprise you. While these numbers reflect federal taxes only (not state estate or inheritance taxes), they paint a clear picture of where the IRS is collecting the most per taxable estate. If you work with affluent clients or family-owned businesses, this article is worth a review.
| | |
Why are Performance Evaluations of Permanent Life Insurance Policies Critically Important?
-
Most permanent life insurance policies rely on various non-guaranteed assumptions.
-
Unfortunately, these assumptions are often overly optimistic, resulting in plans underperforming unbeknownst to the policyowner.
-
A Performance Evaluation can confirm the stability of the insurance carrier and uncover opportunities to reduce premiums, increase the death benefit, improve policy guarantee, and prevent policies from lapsing!
Three Simple Steps to Add Value:
Step 1: Communicate the Importance
Use our Client Explanation Document to help clients understand why policy reviews are critical.
Step 2: Streamline the Review Process
Clients complete a secure intake form, providing policy details for analysis.
Step 3: Deliver Clear, Actionable Insights
We assess policy performance, identify risks, and present options to ensure their coverage aligns with long-term goals.
| |
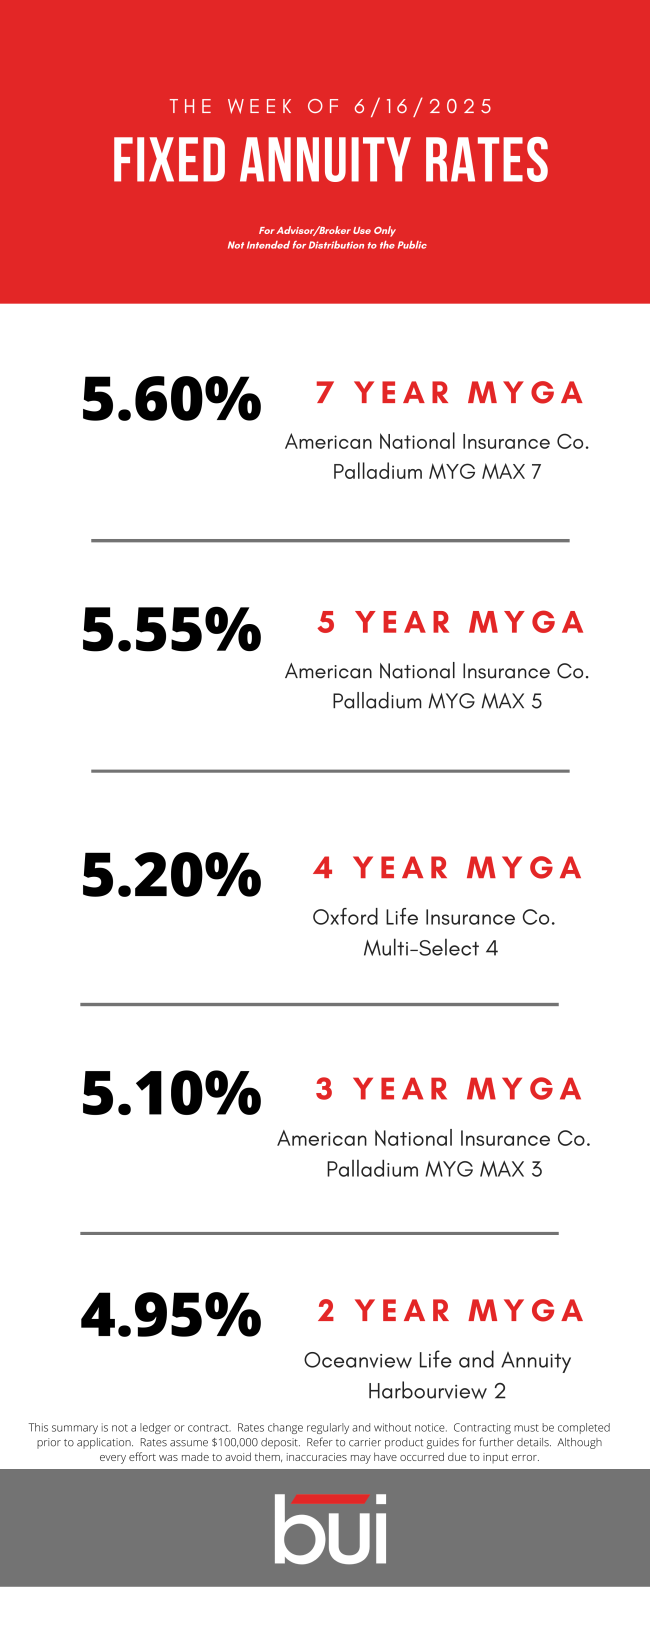
| | Multi-Year Guarantee Annuity (MYGA) Rates | Click here to enter your client’s parameters and access BUI’s online MYGA rate sheet (log-in required). | |
Rates are Decreasing - Be on Alert!
After several months of steady interest rate increases, multi-year guarantee fixed annuity interest rates have been fluctuating. To meet your clients’ interest rate expectations, it is imperative that applications and carrier-specific training is “in good order” prior to submission and that advisors are mindful of the “rate lock” period. Unlike some aspects of insurance underwriting where there may be flexibility, the rate lock date is non-negotiable and insurance carriers will not make exceptions.
| | | | Product availability and pricing changes occur frequently. If you have an illustration over 30 days old, we strongly encourage you to update the illustration before applying for coverage. Please bookmark BUI News to stay up to date on product changes. | | | | |
Update to BUI's Secure Email System
BUI has enabled "Enforced TLS Encryption" on all email services. Transport Layer Security (TLS) is a protocol that encrypts the transmission of emails, making them secure from unauthorized access during transit. By enforcing TLS encryption, it helps to ensure that all emails sent and received through our system are encrypted, protecting sensitive information and maintaining compliance with industry best practices. We believe this change will not only help to maintain the highest level of protection of sensitive data, but also improve the experience of exchanging emails with the BUI team.
| | | | |
Updated Term Rates
Select-a-Term is repriced in all states, excluding New York. Please note that this update only affects the AG products and does not include the US Life products.
| | | | |
Updated Pricing
John Hancock has updated their pricing for both Protection Term and John Hancock Vitality Term. The updates include an average premium decrease of approximately 13% between ages 35-60 for face amounts under $2M, and in some cases up to 40%
| | | | |
Banner & William Penn
Notification of Rate Change
Banner Life and William Penn have new OPTerm level term rates effective 5/8/2025 for existing OPTerm Level Premium Plans and Term Riders.
The rate change applies to level term premiums only; not applicable to post-level term premiums.
The new level term premium rates contain a mix of increases and decreases.
Transition Rules: Normal transition rules will apply; the prior rate scale will be honored until 6/7/2025 (30 days after the Effective Date).
| | | | |
Lincoln AssetEdge® SVUL now available in California
Effective June 2, 2025, Lincoln AssetEdge® SVUL will be available in California.
Lincoln WealthBuilder ECV IUL Now Available
Lincoln’s newest indexed universal life insurance product is available May 12, 2025, subject to state availability.
Lincoln WealthBuilder ECV IUL, the second product in Lincoln’s Elite IUL Portfolio. Lincoln WealthBuilder ECV IUL is life insurance built for growth and designed for high early cash value to help clients meet their financial obligations, such as premium financing and business insurance needs while funding life insurance.
With the introduction of WealthBuilder ECV IUL, Lincoln will sunset new sales of WealthAccumulate® 2 IUL. For states that are available at rollout there is a 90-day transition period which begins on May 12, 2025, and ends on August 10, 2025.
AssetEdge® VUL (2025) now available in California
As of April 14, 2025 Lincoln's AssetEdge® VUL (2025) is available in California. This product will replace Lincoln AssetEdge® VUL (2022).
MoneyGuard Fixed Advantage Product Update
Lincoln Financial Group will implement structural and pricing changes to Lincoln MoneyGuard Fixed Advantage® with the launch of Lincoln MoneyGuard Fixed Advantage® (2025).
- New Point of Claim payment option (indemnity option): Clients choose to receive LTC benefit payments through Reimbursement (receipts required; direct billing and direct deposit available) or Indemnity (monthly payments; no bills or receipts required) at time of first claim. Note: If electing the indemnity option, the benefit amount is limited to 80% of the LTC Maximum Monthly amount
- New Life and LTC premium split reporting: The owner will see one billed premium; for reporting purposes there will be a split between Life and LTC premiums to allow for tax deductibility potential for the portion of premiums identified as long-term care coverage.
- New Increases for Specified Amount will be allowed: Allows for the flexibility to potentially increase benefits post issue.
- Pricing impact: Overall, the pricing for MoneyGuard Fixed Advantage (2025) will be consistent with the current MoneyGuard Fixed Advantage offering
- Most design offerings will see minimal pricing differences ranging from -1% to +1%
- The design offerings featuring 5% compound inflation will see an average increase of 9%
| | | | |
Mass Mutual is introducing new UL Guard and SUL Guard products, designed for clients who want permanent life insurance and low-cost permanent death benefit. Policies will be issued through C.M. Life Insurance Company for all jurisdictions except New York, where MassMutual will be the issuing company.
The new UL Guard and SUL Guard products offer:
• A no-lapse guarantee up to a lifetime
• Improved no-lapse guarantee pricing from their previous products in single-pay and short-pay case designs for target issue ages ranging from 45-75
Illustrations for the new products will become available on June 1, 2025, and the first day to submit applications for the new products is July 19, 2025.
| | | | |
IUL Policy Fee Increase
Effective June 1, 2025, Easy Solve and Target premiums for Index Universal Life Express will be adjusted to reflect a IUL policy fee increase.
This policy fee increase will apply to all United IUL policies, in force and new business, effective June 1, and includes Income Advantage IUL, Life Protection Advantage IUL, Professional Advantage, AccumUL Answers and IUL Express.
Transition Rules
IUL Express applications with an illustration created prior to June 1st must be signed and submitted by May 31st. Please note that all in-progress e-applications must also be submitted by this deadline to prevent potential additional requirements.
Additionally, applications with illustrations generated prior to June 1st and submitted on or after June 1st will require a new revised illustration and must be resubmitted.
| | | | |
Changes to Compensation on Internal Replacements and Exchanges
The following changes to Compensation on Internal Replacements and Exchanges became effective March 3, 2025.
Compensation on Policy Replacements and Exchanges
- Full compensation will be paid on new premium.
- Full compensation will be paid on the cash value transferred in an internal exchange only if:
- The new policy is in the CareMatters series of products and the existing Nationwide life policy has been in force for 10 or more years, or
- The new policy is any other Nationwide life product (not including the CareMatters series of products) and the existing Nationwide life policy has been in force for 13 or more years.
- No compensation will be paid on the cash value transferred in an internal exchange if:
- The new policy is in the CareMatters series of products, and the existing Nationwide life policy has been in force for less than 10 years, or
- The new policy is any other Nationwide life product (not including the CareMatters series of products) and the existing Nationwide life policy has been in force for less than 13 years
- The compensation option will be the same option that was elected for the original contract, when applicable.
- For Nationwide life products that offer the Enhanced Commission Target Premium (CFP), internal replacements and exchanges will not be included in accumulated premium used to qualify for enhanced CTP.
Compensation on Term Policy Conversions
- For conversions in year 1, the original Nationwide term policy is cancelled. Full compensation chargeback occurs. The entire premium is transferred to the new Nationwide life policy. Full compensation is paid on the new Nationwide life policy.
- Conversions after year 1 may be eligible for a conversion credit, depending on the age and the type of the Nationwide term policy.
- Conversion credits, if applicable, are commissionable. For conversion to Nationwide universal life, compensation on the conversion credit from the converted Nationwide term policy is payable at the first year excess of the target rate.
- Normal chargeback rules will apply on the existing Nationwide life policy.
| | | | |
Term Product Change
For clients age 65 and above, Principal’s term insurance now requires a minimum face amount of $1 million. However, it is understood that certain situations, such as buy-sell arrangements, may require lower face amounts. For these cases, Principal has an exception process in place to accommodate clients' specific needs.
Principal Financial Group is two weeks behind on contracting due to volume. Today, the carrier is working on contracting received on May 16th.
Updated Term Rates
Effective April 21, Principal® Term (10-, 15-, 20-, and 30-Year) has been updated for new-issue policies in approved states.
- Rates are updated with a mix of decreases and increases across ages and face amounts.
- The minimum face amount for issue ages 66+ has been increased to $1 million.
- New York has approved Term 2023 (04/2025 on quoting systems).
| | | | |
Classic Choice Term Rate Update
Protective has released their latest rate update for the Classic Choice Term products.
| | | | |
Prudential VUL Protector Update
As of June 23, 2025, Prudential’s VUL Protector product will be updated with more No-Lapse Guarantee choices, an updated investment menu, and new pricing to help clients balance protection and growth.
New No-Lapse Guarantee (NLG) options: The 2025 VUL Protector® has a 5-year NLG that’s included in the base policy and three new optional riders, available for an additional charge, that extends NLG protection up to age 90 or up to lifetime.
A refreshed investment menu: Clients can continue to choose from a broad array of underlying investment options for the potential to grow cash value with more options, including:
• More index fund options
• Target date funds that can align to various case designs
• Defined outcome and protected equity options that emphasize downside market protection.
| | | | |
SecureCare UL Rate Change (CA)
New rates for SecureCare™ Universal Life (UL) (only available in California) went into effect April 7. All pending applications that have an effective date on or after April 7, 2025 will automatically be eligible for and receive the new pricing. Policies that have already been issued, paid and/or are in-force are not eligible for the new rates.
| | | | |
SwiftTerm Rate Update
Symetra has released their latest rate update for the Symetra SwiftTerm products.
| | Thank you for your continued partnership! | | |
BUI
11433 Olde Cabin Road
Third Floor
St. Louis, MO 63141
314-392-2841
800-645-2841
FAX 314-392-2842
www.buiusa.com
| | | | |