BLUME'S BULLS & BEARS
By: Jake Blumenthal
April 12th, 2024
#18
| |
|
This week, markets slightly moved downward following a highly volatile period. The narrative echoed that of the previous week: discussions fluctuated between the possibility of rate cuts and their absence. On Wednesday, the Consumer Price Index (CPI) surged above expectations, only for the Producer Price Index (PPI) to fall below projections. For clarity, CPI assesses inflation from the consumers' perspective, while PPI examines it from a producers' standpoint. A lower-than-expected PPI may imply that producers are not facing significant cost pressures, potentially signaling a slower rise in consumer prices in the near future.
We had a few big banks and financial institutions report Friday morning. All 4 beat on the top and bottom lines, but the stocks had mix results. JPM and WFC were cautious about Net Interest Income, Citi was a tad more optimistic. BlackRock had another strong quarter and steady inflows.
This week Piper Sandler released its 47th semi-annual "Taking Stock with Teens" survey. Key highlights include:
- In Footwear, Nike retained its position as the preferred brand, with notable price target upgrades from BofA. New Balance is gaining market share, likely attributed to its athlete partnerships, including Kawaii, Jamal Murray, Tyrese Maxey, and Cameron Brink.
- In Cosmetics, ELF Beauty dominates the minds of teenagers, while LVMH's Sephora store leads in its segment, possibly due to its new partnership with Kohl's.
- In Fast Food, Chick-Fil-A maintains its dominance with a 16% market share, with McDonald's rising to the second spot followed by Chipotle. Raising Cane's witnessed a significant surge in rankings.
- In Snacking, Campbell Soup's "Goldfish" emerged as the favorite snack, followed by Pepsi's "Lays" and Kellogg's "Cheez-It".
- Lastly, Celsius energy drink commands a considerable market share among teenagers at 17%, surpassing its global share of 12%. While Monster and Red Bull are fading in younger generations. Starbucks continues to maintain a dominant presence in the minds of teens as well.
| |
Hot Topic:
"AZ: Navigating Chips, Borders, and Government Debt"
| |
|
The big news this week was Taiwan Semiconductor being awarded $6.6 billion by the government to expedite and complete the construction of at least one chip plant here in Arizona. The plan is to have one plant operational by late 2025 (although it's doubtful) and another by 2027/2028.
This brings the total investment by TSMC to roughly $65 billion for these plants. To put it into perspective, each plant will require 35 tons of steel for construction, 1,200 multi-million-dollar tools, and 1,500 pieces of utility equipment. Additionally, it's estimated to create thousands of jobs. To meet their targets, they'll likely need at least 6,000 construction workers.
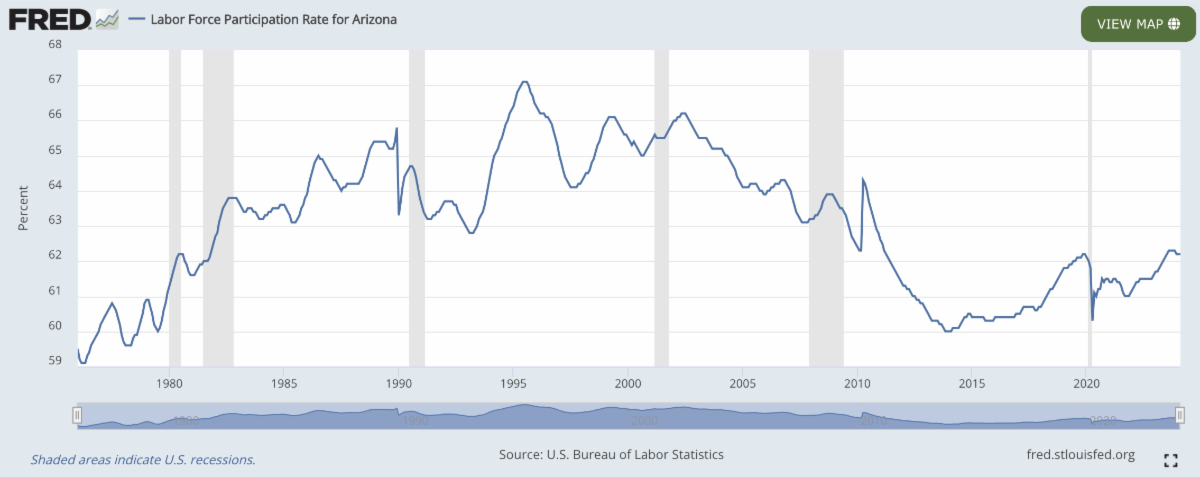
This leads me to a hot topic. Regardless of political views, this situation presents a challenge. There's a significant shortage of physical and trade workers like construction workers, handymen, plumbers, electricians, etc. There is an estimated shortage of 300,000 trade-qualified workers and counting. TSMC has already faced delays due to a lack of workers, and I believe it's likely to happen again.
As much as some may not like to hear it, I believe we will source these workers from immigration ("Open" Border), likely due to an economic agenda. It seems to be the only logical solution given the circumstances. Where else would we get this many workers?
One of, if not, the most realistic ways to address our U.S. debt problem is to grow out of it. This means our GDP will have to increase drastically, probably exceeding our 3% target for a few years. This could lead to economic growth, increasing GDP, and reducing the debt-to-GDP ratio, even if the absolute debt level remains steady or grows at a slower pace.
You might wonder how we can grow our way out of debt. Well, one strategy is for the U.S. to become a chip-producing powerhouse. The current goal is for 20% of all chips to be produced in the U.S. by 2030. It's an ambitious target, but it could ignite growth and innovation in technology and AI. However, we have to get there first and that starts with building these multi-billion dollar factories.
Ultimately, these chip plants are beneficial for the U.S., especially Arizona. They'll turn Phoenix and surrounding areas into booming hubs for the next decade (expect cost of living to increase). While development will take time and the stocks may not see immediate cash flow, the long-term prospects are promising.
|  | |
|
Next week, I anticipate volatility to continue. Following the recent turbulent inflation data and with earnings season now in full swing, I expect the market to exhibit significant fluctuations. One day, a company may indicate positive signals about the economy and consumer behavior, only for another company to raise concerns the next day regarding spending and demand.
The other big developing story is a potential attack from Iran on Israel. This could happen any day now (allegedly) and affect supply chains, specifically oil and its prices. This could be a good time to be overweight energy/oil again. Iran has also come out and said if the U.S. continues to help Israel avert attacks and defend the country, the U.S. will soon be a target too. A story to continue to watch.
Earnings To Watch:
- Monday - Goldman Sachs & Charles Schwab
- Tuesday - United Health Care, Johnson & Johnson, Bank of America, Morgan Stanley
- Wednesday - ASML, Abbott Laboratories, Prologis, Crown Castle, Kinder Morgan
- Thursday - Taiwan Semiconductor, Netflix, Super Micro, D.R Horton
- Friday - Procter & Gamble, American Express, Whirlpool
Earnings season will be in full swing next week with a packed lineup of companies reporting.
Monday and Tuesday kick off with the remaining banks. My focus will be on Schwab and Morgan Stanley. Have Schwab's debt issues been resolved? Is Morgan Stanley seeing any improvements in capital markets? Additionally, I'll be monitoring UNH on Tuesday, given its 15% YTD decline. While I'm not expecting a stellar quarter, I see potential value in the stock, especially if it drops closer to $400—a historically strong and resilient company.
On Wednesday, I'll be keeping an eye on ASML to gauge their ability to meet demand amidst supply challenges. I'll also be interested in how the new US factories impact the company. Prologis is another one to watch for updates on warehouse occupancy rates and cash flow.
Thursday marks the busiest day for earnings. I anticipate high demand for TSMC, likely accompanied by the familiar narrative of demand outstripping supply. I'm curious to hear their plans for the US factories they intend to build. Netflix is a highlight for me, as expectations are high for the company, especially with potential boosts in cash flow and subscribers from password crackdowns and ad-sponsored plans. Remember, they want people to use the ad tier plan, it is more profitable for them. A significant miss on subscriber growth could lead to a substantial drop (roughly 10%) in the stock. Super Micro is another one to watch closely, as I expect significant movement, the direction is uncertain.
To wrap up the week on Friday, PG warrants attention to gauge consumer preferences between premium and generic brands. American Express will provide insights into the debt levels and spending habits of higher-end segments like businesses and HNWI.
| |
 | 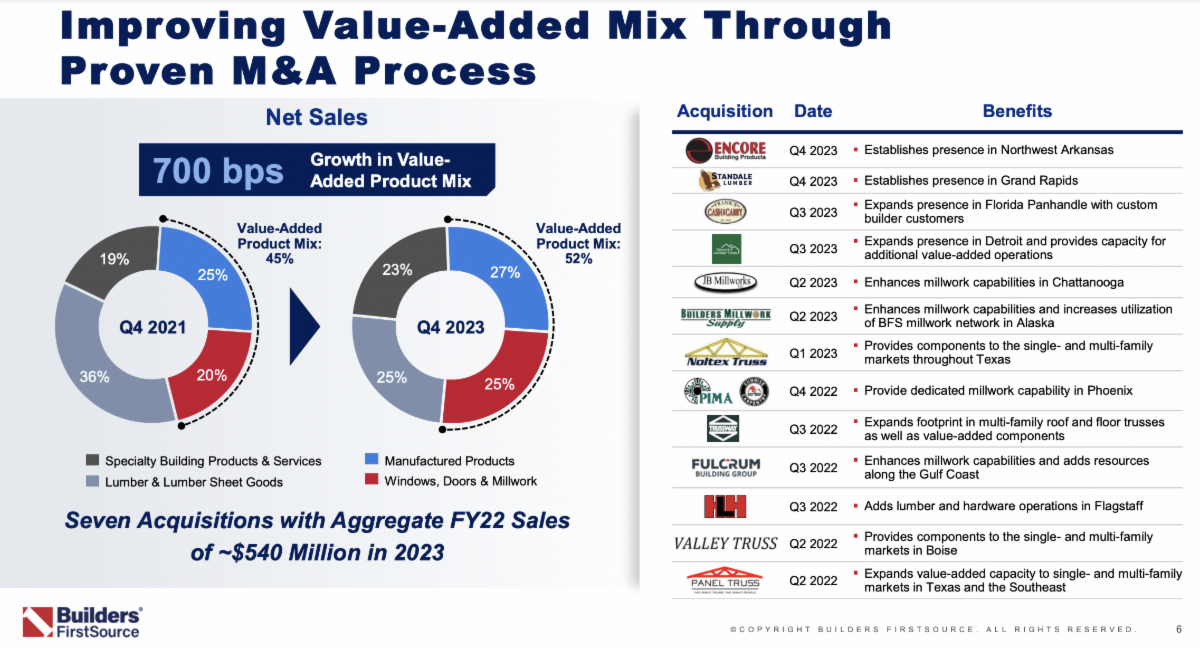 | Builders FirstSource (BLDR) - One of my favorite industrials beyond the main players (CAT & DE) is BLDR. It was recently added to the S&P 500 in December 2023 and has seen tremendous growth over the past year, with a 110% increase on a one-year chart. The stock has recently retraced 13% from its peak just below $215 to its current level of $187. I view this pullback as a potentially excellent opportunity to consider purchasing the stock. With a lower valuation, steady growth, and a market cap of just $22 billion, there appears to be ample room for further advancement. BLDR holds the distinction of being the largest U.S. supplier of building products, prefabricated components, and value-added services to professional builders for new residential construction and repair and remodeling projects. They offer customers a comprehensive homebuilding solution, encompassing manufacturing, supply, delivery, and installation of a wide range of building materials. Considering the allocation of funds from the government's Industrial Innovation Act aimed at developing cities and states nationwide in the coming years, I anticipate BLDR will be a clear beneficiary of this initiative.
Constellation Brands (STZ) - For those seeking diversification, a new consumer staple stock, or simply a way to invest in the alcholic beverage industry due to personal enjoyment, look no further. As I mentioned last week, STZ stands out as my preferred alcoholic beverage company, and they recently reported earnings. Their performance was nothing short of phenomenal, with the stock reaching a new all-time high. In the fiscal year, their beer business experienced a 9% growth, and they anticipate similar high single-digit growth in FY 2025. Moreover, they delivered operating cash flow at the upper end of their guidance, while free cash flow surpassed expectations, all while maintaining disciplined capital allocation strategies. Additionally, they raised their dividend by 13%, signaling their commitment to shareholder returns and positioning themselves as a potential dividend aristocrat in the future. STZ's Mexican beer portfolio, which includes Corona, Modelo, and Pacifico, continues to drive growth and profitability, and I anticipate this trend will persist. Consider taking a closer look at STZ; it's undoubtedly a top consumer staple stock worth considering.
GitLab Inc. (GTLB) - I'm continuing my trend of highlighting new, under-covered, and untraditional AI plays in the market. This week, I want to discuss GTLB because I've been seeing a little more chatter on the street about the stock and a couple of price target upgrades to $70 per share from Wells Fargo, Raymond James, & KeyBanc. The stock currently trades in the high $50s. GitLab Inc. is the provider of The DevSecOps Platform, a single open-source application that enables organizations to deliver better and safer software faster. In simpler terms, every company needs to be great at developing, securing, and deploying software. GTLB makes that process easy and automated. GTLB's sales grew roughly 37% last year, and they expect high 20% growth for at least the next three years. They achieved their first year of non-GAAP profitability last fiscal year and expect earnings to grow even faster than sales in the coming years. They boast insane gross margins (89%), and operating and net income margins will only improve as they shift their focus from growth to efficiency down the road. The multiple is undeniably high (241x 2025 P/E), but if growth goes as expected, they trade at just 61x 2027 P/E. The anticipated growth justifies GTLB's premium valuation, but any sign of slowing growth could cause the stock to drop rapidly. I've started watching the stock more frequently and would be more interested in buying in the low $50s or under. For now, I'm just observing. However, I do find the increasing attention this company is attracting on the street interesting. At just over a $9 billion market cap, there's certainly a lot more room for this company to grow if its products are as good as some are making them sound.
| * Disclaimer - It's important to highlight that, on occasion, I may have existing positions in the stocks I highlight in my newsletter. This disclosure aims to be transparent about potential conflicts of interest. Although I strive for unbiased analysis, my ownership of certain stocks may influence those that I highlight. Rest assured, my commitment to providing well-researched insights remains unchanged. | |
|
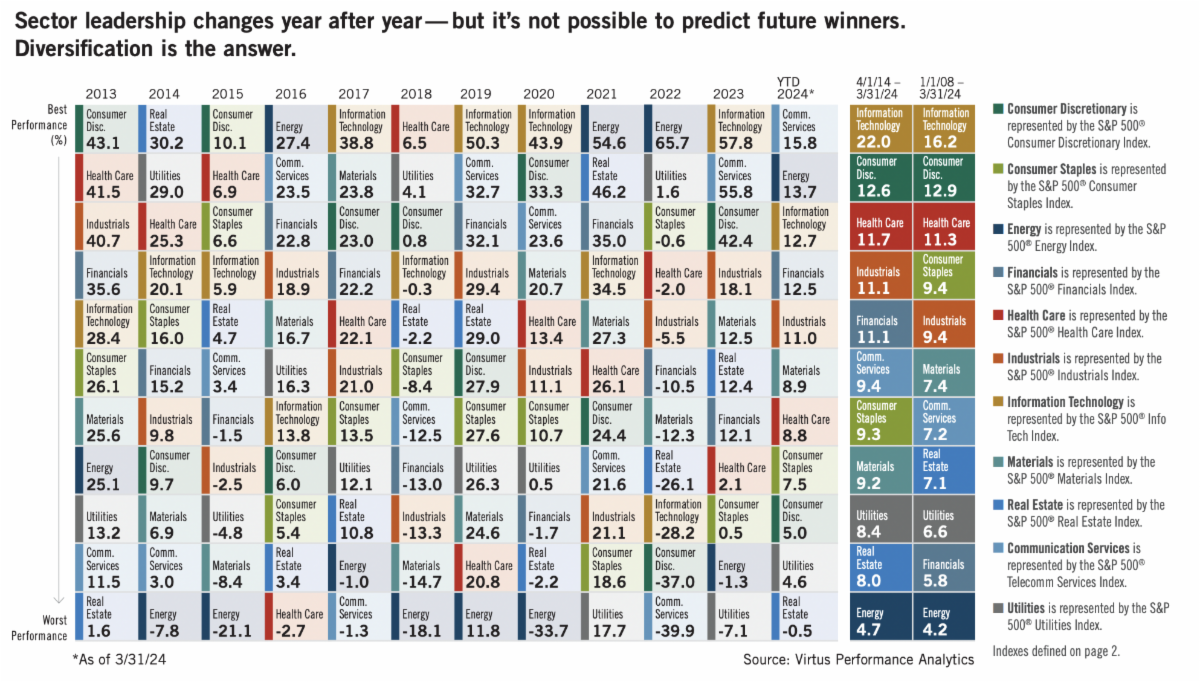
This is one of our favorite charts to look at and share here at Meridian. Often referred to as a sector quilt chart, or you may hear some (including me) call it a jelly bean chart. Come on, tell me it doesn't look... Nevermind.
Anyways, this chart came out less than 2 weeks ago when Q1 ended on March 31st. It puts into perspective how each market sector has fared YTD in 2024 so far and how they performed over the last 10+ years. The two columns on the far right show the average performance for each sector over the last 10 years and how they performed before the great financial crisis till now.
Then from the third column on the right, we get YTD performance followed on the left for how each sector did in the past 10 years. There is one thing that really stood out to me on this chart that I wanted to note.
If you look at YTD, two of the top three performers (1 & 3) are Communication services (basically Tech) and information technology. Communication services did slightly better on this chart because it tracks the XLC where META and Alphabet make up 45% of the fund. Anyways, the second top-performing sector is energy. Why this stood out to me is if you look at the chart over the past 10 years, we have never had information tech and comm services in the top 3 performing sectors while energy excels in performance too.
What this tells me is potentially one sector may have to give. Energy has been doing really well because oil prices have been steadily creeping back up eyeing that $100 a barrel target. That's good for energy stocks which may cause the sector to do well, but that could mean inflation creeps back up, rates stay higher, and we see technology start to fall back down. Vice versa, oil prices could come back down and energy stocks may pull back as cash flow would not be as high as if oil prices rise. Oil prices coming down could lead inflation to pull back and bring back into question more rate cuts which could help tech, especially non-profitable tech companies.
The correlation between energy stocks and Tech stocks is definitely something I will be keeping my eye on in Q2 and for the rest of the year.
| |
|
In Weekend Favorites, I share my thoughts on events I'm attending, the new series I'm planning to marathon, the movie I'm dying to see, restaurant craving to taste, trend that ticks me off, or the big game I won't miss.
First up, UFC 300 is finally here, and man, it's going to be epic. This card is stacked with more current and former champs than we have ever seen before. There are so many matchups that could go either way, it's bound to be thrilling. A few picks I'm rooting for: Charles 'Do Bronxs' Olivera to pull off an upset, Gaethje to take down Holloway in what's sure to be a battle, and Pereira to catch Jamal 'Sweet Dreams' Hill slipping and send him to dreamland. I'm counting down the hours! Plus they announced fight bonuses will be 6x bigger, fighters will be swinging for the fences... Can not wait!!
Next, Arizona's Country Thunder kicks off in Florence from Thursday, April 11th to Sunday, the 14th. While I'm a bit bummed to miss out on the festival, I have to admit, the lineup this year doesn't quite have me jumping out of my seat. Sure, I'd love to catch Jelly Roll on Saturday performing my two favorite songs 'Son of a Sinner' and 'Need a Favor', but beyond that, the other performers just don't have me all that excited. Who schedules a start on a Thursday, anyway? Seems like they are missing out on a day of great headliners. Then you would think Friday brings some bigger names, but nope. Maybe I'm just biased towards the new up-and-comers and top acts, but hey, Country Thunder out west deserves nothing but the best, right? I guess I'll have to wait for next year's lineup to really get excited.
Lastly, I wanted to recommend Amazon Prime's new comedy movie 'Ricky Stanicky' for some late-night laughs. It features an all-star lineup of actors including John Cena, Zac Efron, Andrew Santino, and more. The plot is clever, and we all wish we had a friend like Ricky Stanicky. Give it a chance!
Enjoy your weekend, everyone!
| |
To learn more about Jake and what the Meridian Team can offer you, use the links below! | |
|
To read more of Jake's Analysis on Seeking Alpha where he shares his thoughts, opinions, stock ratings, and price targets on different stocks and ETFs, use the link below! | |
Sources:
- https://www.blackrock.com/us/financial-professionals
- https://app.koyfin.com/home
- https://seekingalpha.com/
- https://www.cnbc.com/
- https://ir.gitlab.com/
- https://www.virtus.com/our-thinking/insights?
- https://investors.bldr.com/overview/default.aspx
| |
Disclaimer:
Jake Blumenthal is a Registered Investment Advisor and Portfolio Analyst with Meridian Wealth Management, a SEC Registered Investment Advisor. The views and opinions expressed in the following content are solely those of Jake Blumenthal and do not necessarily reflect the views and opinions of his employer, Meridian Wealth Management. The content provided is for informational purposes only and should not be considered as financial advice or a recommendation to engage in any investment or financial strategy. Readers are encouraged to conduct their own research and consult with a qualified financial professional before making any investment decisions. Meridian Wealth Management does not endorse or take responsibility for any content shared by Jake Blumenthal outside of his official duties at the company.
| | | | |