Mortgage rates have eased a bit after hitting a recent high. This morning’s inflation report was hotter than expected, but after an early increase, my pricing is slightly better than yesterday’s close. The odds of a Fed rate hike jumped from about 20% to 50%. That may sound like bad news, but if the Fed can get inflation under control, it could help mortgage rates come down over time.
The Fed doesn’t directly set mortgage rates.
Lower inflation is the key to lasting improvement.
Today’s recovery is encouraging, but it’s still early.
TRUE - INDEPENDENT - MORTAGE BROKER
Rates as of [Wednesday October 14, 2026]
UNDERWRITING FEE WAIVED ON ALL SCENARIOS!!!
LOAN PROGRAM
RATE
APR/POINTS
30 YEAR FIXED
7.375%
7.57% / 0.482
15 YEAR FIXED
6.625%
6.930% / 0.757
FHA 30 YEAR FIXED
6.750%
7.644% / 0.630
VA 30 YEAR FIXED
6.500%
6.863% / 0.989
JUMBO 30 YEAR FIXED
7.000%
7.118% / 0.618
*APR=Annual Percentage Rate. Assumed 760 credit score, OR/WA purchase. Rates include pricing up to a 1% loan fee. Based on $600,000 purchase price with 20% down. FHA APR based on $600,000 purchase price with 3.5% down includes MI. VA with 0% down & 2.15% Funding Fee. Jumbo loan based on $1,125,000 sales price with 20% down/780 credit score. Rates are subject to change during the loan term. That change can increase or decrease your monthly payment. See Hood River Mortgage Group for details. Rates are subject to change without notice.
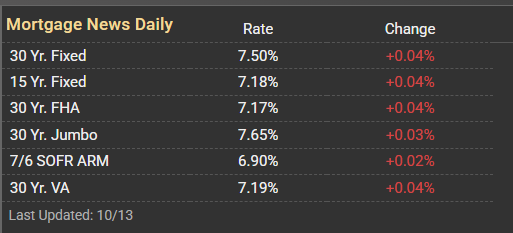
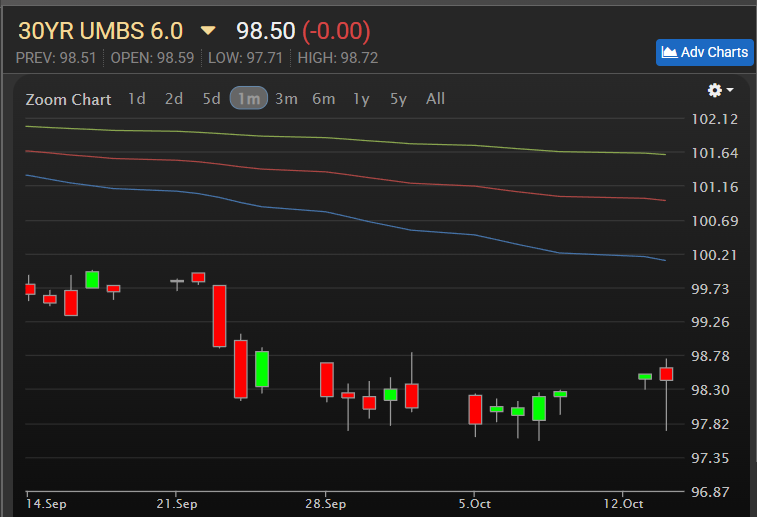
PUBLISHED NATIONAL AVERAGE RATES Mortgage backed securities chart
How Mortgage News Daily Calculates These Rates
Averages are based on actual rate sheets from a variety of wholesale, correspondent and retail lenders, using a consistent “top-tier” borrower scenario. Rates are updated daily as market pricing changes.
The typical scenario assumes:
780 FICO
75% LTV / 25% down
30-year fixed conventional conforming loan
Top-tier agency pricing
No unusual or program-specific pricing adjustments
Actual mortgage pricing can vary based on credit, down payment, loan amount, property type, loan program, points and other factors.
📈 Reading the MBS Chart
MBS prices and mortgage rates generally move in opposite directions.
MBS price ↑ = Good for mortgage rates — pricing improves, which can lead to lower rates.
MBS price ↓ = Bad for mortgage rates — pricing deteriorates, which can put upward pressure on rates.
The one-month chart helps show the overall trend rather than focusing on any single day.
When MBS prices are trending higher, that’s generally a positive sign for mortgage rates.
When prices are trending lower, rates are typically facing upward pressure.s are typically facing upward pressure.
This Week’s Program Highlight: HomeReady & Home Possible
“Only 3% Down? Don’t Overlook These Conventional Options.”
Think beyond FHA! Fannie Mae’s HomeReady and Freddie Mac’s Home Possible programs offer eligible buyers a path to homeownership with as little as 3% down.
Program Highlights:
Low down payment: As little as 3% down.
Competitive interest rates and potential pricing advantages
Mortgage insurance: Potentially favorable MI options, depending on the borrower and loan scenario.
Income-based eligibility: Designed to help eligible low- to moderate-income borrowers.
Conventional financing: An alternative to FHA worth comparing.
Flexible funds: Gift funds and eligible assistance programs may help cover upfront costs.
Have a buyer who thinks they need more money down? HomeReady or Home Possible may be worth a look. I’m happy to compare the options and see which program fits best.
Give me a call and let's see !
Income limits and other eligibility requirements apply.
Have First Time Home Buyers?
Ask me about my Oregon Housing Down Payment Assistance Programs
Mortgage Strategy Tips:
Encourage buyers to compare multiple lenders—rate quotes don’t require multiple full applications.
Mortgage brokers can’t mark up government loans (VA, FHA, USDA), making them especially competitive.
Proactively review past clients for refinance or cash-out opportunities.
Ask about DSCR and non-QM options for investor clients.