Two of California’s worst wildfires in 2018 cost Allstate Corp. a half-billion dollars, but the insurance conglomerate was able to give investors some reassuring news: It had already shrunk its footprint in California by half, creating a buffer of sorts against future losses. Earlier this year, however, Allstate told California regulators it planned to expand its homeowners’ coverage throughout the state — taking on new customers for the first time in nearly 15 years. “We’ve been there for Californians throughout the wildfires by paying thousands of insurance claims and we extended our coverage offerings this year to help alleviate the homeowners’ insurance availability crisis,” the company said in a statement to The Sacramento Bee.
After the mega-disasters of 2017 and 2018, insurance carriers dropped tens of thousands of homeowners in the Sierra foothills and other fire-prone areas of California, forcing policyholders into a costly, state-mandated insurance pool. Customers who were paying, say, $2,000 a year for coverage are now paying twice or three times as much. Now, however, something is stirring in what Allstate once dubbed “catastrophe-prone California.” Following four years of turmoil, traditional insurance companies are inching their back into wildfire country.
Armed with higher rates — and better information about the risks from mega-fires — they’re beginning to underwrite policies in areas they’d been abandoning. While the state-run insurance pool, the California FAIR Plan, is still taking on new customers, its rate of growth is slowing down.
One big company, CSAA Insurance Group, has promised not to drop any more customers through the end of 2023. Several major carriers are offering discounts to encourage homeowners to install fire-resilient roofs, clean the brush from their yards and take other safety measures.
Bottom line: A crisis that’s plagued rural California is starting to moderate.
“There are little green sprouts, I would say, coming up,” said Amy Bach, executive director of United Policyholders, a consumer advocacy group based in San Francisco. “We are starting to see a little loosening in the underwriting.”
The crisis is far from over. On Wednesday, California’s insurance commissioner prohibited insurance companies from dropping nearly 210,000 homeowners in areas affected by this year’s wildfires, another in a series of orders aimed at easing a shortage of affordable coverage in fire-prone areas. The moratorium requires insurers to retain these policyholders for a year and covers people who live near some of the largest wildfires of 2021, including the KNP Complex in Sequoia National Park.
Nevertheless, despite the ever-increasing risk of wildfires from climate change and other factors, California has lately become a better place to do business.
Companies have been getting rate increases from the state Department of Insurance — at the same time that claims for wildfire damages have declined significantly. Even last year, when more acres burned in California than ever, the damage to buildings wasn’t nearly as bad as during 2017 or 2018 and insurers made money on homeowners’ coverage, according to Department of Insurance data.
What’s more, companies have decided they can’t simply ignore California, where homeowners’ insurance is a $9 billion-a-year business.
“What I’m sensing from the insurance companies is that it’s very hard to say no to the largest insurance market in the nation,” said Attila Toth, chief executive of Zesty.ai, a Bay Area tech company that’s partnered with Farmers Insurance Group to analyze risk and expand coverage. “Many of them are now saying, ‘How do I write business but in an intelligent way?’ ”
SOME INSURERS STILL LEAVING WILDFIRE ZONES
That sentiment is by no means universal; some companies are still retreating from California’s fire zones as quickly as they can.
Take Chubb Group, a global property-casualty insurer with offices in Zurich, New York and elsewhere. In late October the company, which specializes in covering California high-end homes, said it’s dramatically reducing its customer base in wildfire areas, even places where the risk is considered moderate. “Someone else will have the pleasure of writing that business, unfortunately,” Chief Executive Evan Greenberg told investment analysts.
Greenberg said Chubb has been unable to get rate increases large enough to justify the risk. Other industry executives agree: While premiums have risen in the past couple of years, they’re still too low to spark a wholesale return to fire-prone communities.
“If you let me charge a premium level to support those higher losses, I can go into those higher risk areas,” said Rex Frazier, president of the Personal Insurance Federation of California, which lobbies for several major carriers.
Generally speaking, insurance premiums are a reflection of past experience. Frazier said insurers want the California Department of Insurance to adopt a “catastrophe model” for setting premiums — a system that leans more heavily on models that predict future risk.
It’s a controversial idea. Bach, the consumer advocate, some catastrophe models could be useful — but also might be used by companies to exaggerate the risk they face. Insurance Commissioner Ricardo Lara isn’t yet sold on it.
“Commissioner Lara’s top priorities are making insurance easier for consumers to find and afford,” said his spokesman, Michael Soller. “He has not seen compelling evidence yet that complex catastrophe models can serve that purpose.”
Soller said the market is getting healthier, and “we’re seeing the first positive movement in many years on insurance being more available.” But he acknowledged: “The job is not done.”
On that point, the industry agrees.
Conditions are improving, but “it’s probably coming too slowly for people on the FAIR Plan,” Frazier said. “There’s still some distance between here and there.”
A CALIFORNIA HOMEOWNER’S INSURANCE WOES
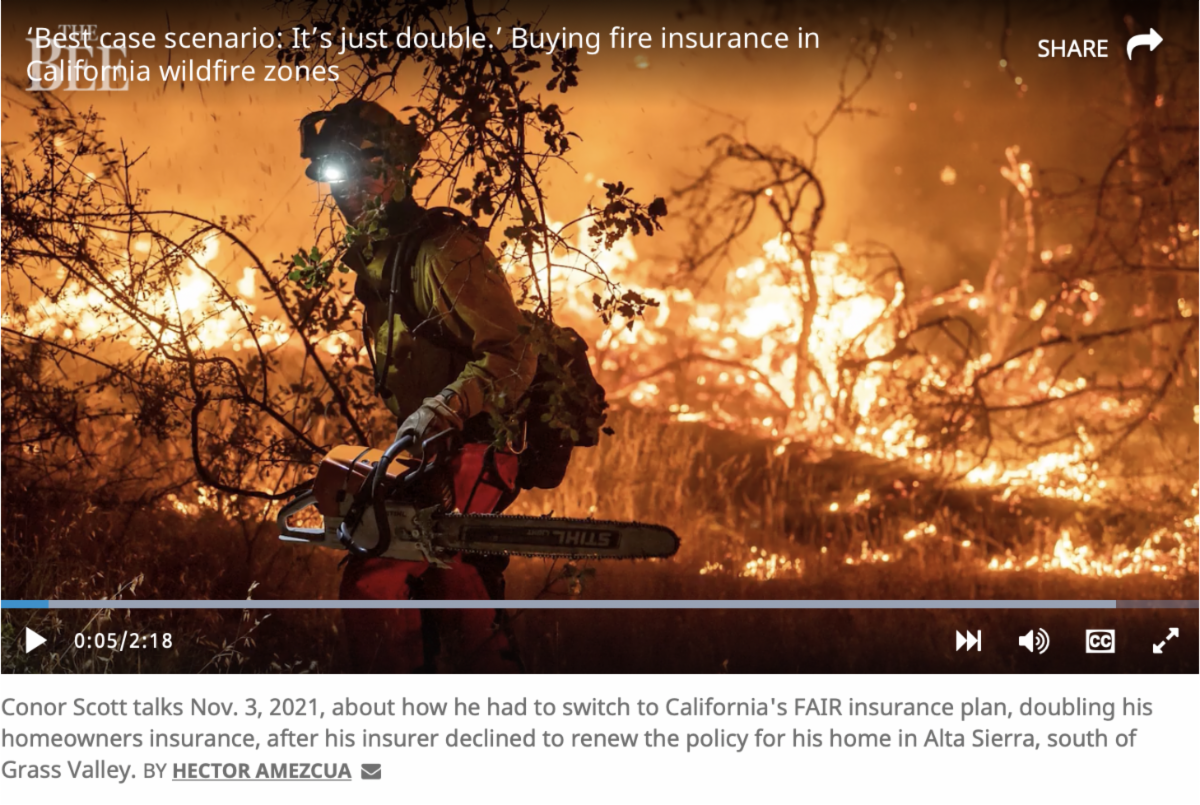
The situation certainly isn’t improving quickly enough for Conor Scott.
He found out in late June that his carrier, Grange Insurance Association of Seattle, wasn’t going to renew the homeowners’ policy on his ranch-style home in the woodsy Alta Sierra area south of Grass Valley.
“Your property does not meet our wildfire eligibility,” the letter from Grange said.
The experience left him feeling helpless.
“It just feels like it’s a broad brush, it’s happening to everyone,” said Scott, 29, who’s lived in his home for two years. “It’s intimidating. Insurance companies are huge. “
Like thousands of rural Californians, he wound up on the FAIR Plan, the state’s “insurer of last resort,” an entity created by the Legislature to guarantee coverage to Californians after the riots and brush fires of the 1960s. State officials say its enrollment jumped from around 140,000 homeowners in 2018 to more than 200,000 last year — and that’s in spite of a series of moratoriums imposed by Lara. The moratoriums force insurers to retain customers for one year if they live near an area hit by a recent big wildfire.