|
Part II: Putting It Together — Three Case Studies
The accounts described in Part I are most useful when you can see how they work together for a real family.
The three scenarios below all share a common profile: the couple is married and filing jointly. Spouse 1 works for a company that offers both a 401(k) plan and an HSA-eligible High-Deductible Health Plan. Spouse 2 earns income as an independent contractor. And in each case, the couple is targeting retirement savings equal to 10% of their gross household income.
The income level, age, and proximity to retirement vary meaningfully across the three scenarios — and so does the optimal strategy.
Scenario 1: Building the Foundation
25 Years from Retirement • Household Income: $225,000 • Savings Target: $22,500
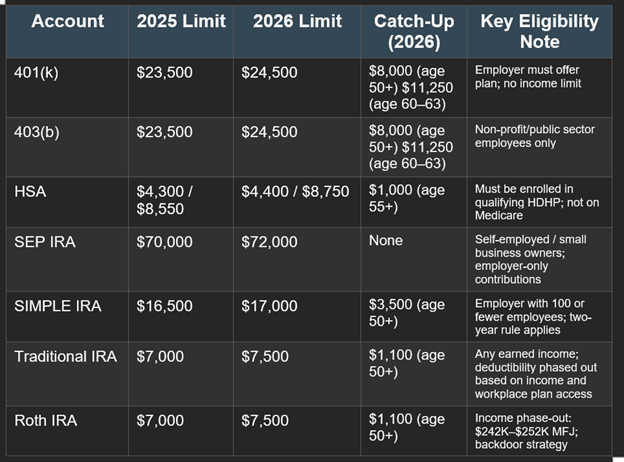
The income picture. Let’s assume Spouse 1 earns $150,000 in W-2 income, and Spouse 2 earns $75,000 as an independent contractor. The couple files jointly with a combined MAGI of $225,000 — which sits comfortably below the 2026 Roth IRA phase-out threshold of $242,000. That is an important and somewhat time-sensitive window: both spouses are eligible for direct Roth IRA contributions, and at age 40 they have 25 years or more for those contributions to compound entirely tax-free.
Spouse 1 — Roth 401(k) and HSA. Spouse 1 does not need to max out the 401(k) to hit the household savings target — but the type of contribution matters. Because they have 25 years until retirement and are still in a moderate tax bracket, the Roth 401(k) is the preferred vehicle: contributions are after-tax today, but every dollar of growth over the next quarter-century and into retirement will be completely tax-free at withdrawal.
The HSA deserves equal emphasis. With a 25-year time horizon, the HSA should be thought of not as a medical spending account, but as a stealth retirement account with a triple tax advantage. If the couple enrolls in a qualifying HDHP and maximizes the family HSA contribution of $8,750, and pays their current medical expenses out of pocket, those dollars can grow tax-free for decades and eventually can be used tax-free for healthcare in retirement — when medical costs tend to be at their highest.
Spouse 2 — Roth IRA. For Spouse 2, the most straightforward path is a direct Roth IRA contribution. At $225,000 combined income, they qualify. The maximum contribution in 2026 is $7,500, and like the Roth 401(k) for Spouse 1, the 25-year compounding window makes the Roth treatment highly attractive. If Spouse 2 is looking to save more, a SEP IRA offers significant additional capacity — up to approximately 20% of net self-employment income, or roughly $14,000–$15,000 in this income range.
However, SEP IRA contributions are pre-tax and add to traditional IRA balances, which creates future RMD obligations. For a 40-year-old, building Roth assets now is generally the stronger long-term choice.
Reaching the $22,500 target:
-
Spouse 1, Roth 401(k): $6,250
-
Family HSA: $8,750
-
Spouse 2, Roth IRA: $7,500
-
Total: $22,500
Key insight. This couple is in a genuinely fortunate position: high enough income to save meaningfully, but still within the Roth IRA eligibility range. As income grows over the coming years, Roth IRA access may phase out, making direct contributions unavailable. Building future tax free assets aggressively now — in the 401(k), the Roth IRA, and the HSA — is a strategy that will pay dividends for decades.
Scenario 2: The Final Push
5 Years from Retirement • Household Income: $500,000 • Savings Target: $50,000
The income picture. Let’s assume Spouse 1 earns $300,000 in W-2 income, and Spouse 2 earns $200,000 as an independent contractor. Both are in the 60–63 age window. The combined MAGI of $500,000 places them well above the Roth IRA income limit — direct Roth IRA contributions are not available. However, the heightened catch-up contribution limits available to the 60–63 age group, combined with the SEP IRA’s generous ceiling, give this couple significant tax-advantaged savings capacity.
Spouse 1 — 401(k) super catch-up and HSA. At age 62, Spouse 1 is squarely in the super catch-up window. The maximum employee deferral in 2026 is $24,500, and the super catch-up for ages 60–63 is $11,250 — for a total employee contribution of $35,750. Add the family HSA contribution of $8,750 plus the age-55+ HSA catch-up of $1,000, and Spouse 1 alone accounts for $45,500 in tax-advantaged contributions.
There is an important planning note here: because Spouse 1 earned more than $150,000 in FICA wages in the prior year, the SECURE 2.0 Roth catch-up rule applies. All catch-up contributions to the 401(k) — the full $11,250 — must be made as Roth (after-tax).
This means no immediate deduction on the catch-up amount, but those dollars will grow and be withdrawn completely tax-free. Given that this couple is likely to be in a high tax bracket throughout retirement, this is not necessarily a disadvantage — but it does affect current-year cash flow planning and should be incorporated into the tax projection for the year.
Also worth noting: with only five years remaining before retirement, HSA contributions should continue to be maximized — but the couple should be aware that HSA contributions must stop when Spouse 1 enrolls in Medicare. If retirement coincides with Medicare enrollment, the HSA contribution window closes.
Spouse 2 — SEP IRA and backdoor Roth. With $200,000 in gross self-employment income, Spouse 2’s SEP IRA capacity is substantial. After the self-employment tax deduction, net self-employment income is approximately $186,000, and 20% of that produces an allowable SEP contribution of roughly $37,000. This provides a powerful pre-tax deduction on a significant portion of Spouse 2’s self-employment income.
At this income level, a direct Roth IRA contribution is not available — but the backdoor Roth strategy may still be viable. The mechanics involve making a non-deductible $7,500 contribution to a traditional IRA and immediately converting it to a Roth IRA.
The key consideration here is the pro-rata rule: if Spouse 2 has other pre-tax IRA balances (such as from a prior rollover), the conversion will be partially taxable. If the SEP IRA holds significant pre-tax assets, the backdoor Roth becomes considerably less attractive — this is a scenario that warrants careful tax modeling before proceeding.
Reaching the $50,000 target. The remarkable thing about this scenario is that Spouse 1’s contributions alone — $45,500 — nearly cover the entire household savings target. Adding even a modest SEP IRA contribution from Spouse 2 easily surpasses $50,000.
-
Spouse 1, 401(k) base deferral: $24,500
-
Spouse 1, super catch-up (ages 60–63, Roth): $11,250
-
Family HSA (+ age-55 catch-up): $9,750
-
Spouse 2, SEP IRA: $4,500 (minimum to reach target)
-
Total: $50,000
Key insight. This couple’s actual tax-advantaged savings capacity far exceeds their 10% target. The SEP IRA alone could shelter an additional $30,000+ of self-employment income. In the five years before retirement, maximizing pre-tax deductions now — while simultaneously building Roth assets through the mandatory Roth catch-up — positions the couple with diversified tax exposure in retirement. That tax diversification, between taxable and tax-free income sources, will give them meaningful flexibility to manage their tax bracket after they stop working.
Scenario 3: Extending the Runway
Spouse 1 Retired • Spouse 2 Still Working • Household Earned Income: $75,000 • Savings Target: $7,500
The income picture. This scenario is different in kind from the first two. Spouse 1 is retired — perhaps drawing from a pension or investment portfolio — and has no earned income. Spouse 2 is still working as an independent contractor, earning $75,000. The household’s total earned income — the figure that governs retirement account eligibility and contribution limits — is Spouse 2’s $75,000 alone.
The couple’s combined MAGI is well below the Roth IRA income phase-out threshold, which means both Roth IRA strategies and Roth conversions carry a favorable tax cost.
Spouse 1 — The spousal IRA. Although Spouse 1 has no earned income of their own, a spousal IRA allows Spouse 2’s earned income to fund a contribution on Spouse 1’s behalf. As long as the couple files jointly and Spouse 2 has sufficient earned income, Spouse 1 can contribute up to $7,500 — or $8,600 with the catch-up if age 50 or older — to either a traditional or Roth IRA in their own name.
At the income level in this scenario, a Roth IRA is the recommended choice for Spouse 1. The current tax rate is likely lower than it will be if and when larger RMDs kick in from pre-tax accounts. Every dollar contributed to the Roth IRA now will grow and be withdrawn tax-free. There are no RMDs on a Roth IRA during the account owner’s lifetime, which provides additional planning flexibility.
The Roth conversion opportunity. This scenario also presents one of the most powerful Roth conversion windows available: the period after one spouse has retired but before RMDs begin and Social Security is claimed at its full level.
If Spouse 1 has significant pre-tax balances in a former employer’s 401(k) or in traditional IRAs, the gap years of early retirement — when taxable income is lower — are an ideal time to convert portions of those accounts to Roth IRAs. For a more detailed discussion of this strategy, including the interaction with Social Security and Medicare premiums, please see our April 2026 article on Roth conversions.
Spouse 2 — SEP IRA and Roth IRA. Spouse 2 has two natural vehicles: a SEP IRA for the immediate tax deduction on self-employment income, and a Roth IRA for tax-free future growth.
The maximum SEP contribution here is approximately 20% of net self-employment income — roughly $14,000 at this income level. Since the household savings target is $7,500, Spouse 2 does not need to maximize the SEP IRA; instead, the question is how to split the contribution between tax-deferred (SEP) and tax-free (Roth).
If Spouse 2 is enrolled in a qualifying HDHP and is not yet on Medicare, an individual HSA contribution of $4,400 (plus $1,000 if age 55 or older) is also available, offering additional tax-advantaged capacity.
Reaching the $7,500 target:
-
Spouse 1, spousal Roth IRA: $7,500 (or $8,600 with catch-up)
-
Spouse 2, Roth IRA: Additional $7,500 if desired (funded by Spouse 2’s earned income)
-
Spouse 2, SEP IRA: Optional — for additional tax deduction on self-employment income beyond the 10% target
To meet just the $7,500 target, the simplest path is a single spousal Roth IRA contribution for Spouse 1. But this couple has the capacity to do considerably more if they wish — and given the favorable income level and tax environment, doing more in Roth form is likely to serve them well.
Key insight. This scenario illustrates something that surprises many clients: a retired spouse can still build retirement savings, as long as the other spouse has earned income and the couple files jointly.
The spousal IRA is underused and underappreciated. Combined with the Roth conversion opportunity that retirement creates — often a multi-year window of lower taxable income before RMDs and Social Security crowd the picture — this couple has the tools to meaningfully strengthen their tax position in retirement, even on a modest income.
Closing Thoughts
The 2026 contribution limit increases are welcome news — they give savers a bit more room. But the greater opportunity lies in understanding how these accounts work together. A 401(k) and an HSA and a Roth IRA and a SEP IRA are not competing options. For the right family, they are complementary layers of a single, coherent strategy — each account doing a specific job, in a specific tax “bucket,” for a specific purpose.
The right combination for your family depends on your income, your employment situation, your age, your proximity to retirement, and your tax picture today versus what you expect it to be in the future. There is no one-size-fits-all answer — which is exactly why we model these decisions individually, account by account, year by year.
If you have not recently reviewed how your current contributions are structured, or if your situation has changed — a new job, a shift to self-employment, a spouse entering or leaving the workforce, or an approaching retirement — this is an ideal time for a conversation. We are here to help you make the most of every dollar you put to work for your future.
The Real Cost of Switching Majors
Choosing a major at the age of 17 or 18 is usually not easy – and switching majors in college is common. In fact, most students change their major two to three times before graduating.
While this is sometimes necessary and a healthy way to explore interests, families are often unaware that it can have a major impact on graduation date and overall cost. It is usually not a consideration in the planning process for college financing prior to choosing a college.
The potential increase in cost may not be a reason to dismiss the thought of changing majors especially if it will truly be a better path for the student. However, it is wise to anticipate the potential changes in cost and time to graduation.
Here is what to consider when talking about potential major changes.
Lost Time- Extra Semesters
This can be the biggest factor in changing majors. Adding extra semesters involves more cost.
Many majors have different core requirements and sequences of courses. Switching into a specified major such as nursing, engineering, or education for example requires foundational courses that are often different for each. Changing to a very different major can create the need for:
- An additional semester
- An additional full year
- Sometimes certain courses are only offered one semester per year
We all know college costs are high, and an extra semester can cost anywhere from $12,000-$25,000 or possibly much more depending on the school.
Losing Credit for Courses Already Taken
Families often assume that if a student stays at an institution, prior coursework will apply to a change in major, but that is not always the case.
A change in major can cause:
- Electives that no longer satisfy major requirements
- Lost credit toward major prerequisites
- Credits that count toward graduation, but not the new degree
Program GPA Requirements
Many competitive majors require higher GPAs for admission to the program and if admission is delayed, students may not be able to enter the program later, or may be required to retake courses or take courses that do not count toward graduation.
Effects on Scholarships and Financial Aid
Some scholarships are tied to:
- Being in a specific major
- Taking a minimum number of major-related credits
- Tuition waivers- tied to majors
- Departmental Awards- tied to majors
Emotional Impact: Pressure, Stress and Confidence
Considering the financial impact matters of course, but there are the emotional impacts on the student to consider:
- Exploring career options in high school
- Getting involved as a volunteer or in a program or business that you are interested in
- Speaking to adults in your family and friend circle who work in your desired profession
- Consider self-interests and not just popular majors
- Your first year in college- find a great advisor and take advantage of their expertise and advice
All this information is not to say that switching majors is a sign of poor planning or failure, but rather to encourage consideration early in the process to help avoid some of the potential challenges and costs later.
The bottom line is that with the significant investment in a college education it is important for students to be in a major that will help them lead a successful and happy career after graduation.
More Than Enough
Even if you think of yourself as having "enough" rather than "more than enough," if you are spending at a conservative rate from your savings, the reality is that you may well be unlikely to deplete your assets during your lifetime. Which means that, financially speaking, "enough" might turn out to be "more than enough.”
In More Than Enough: A Brief Guide to the Questions That Arise After Realizing You Have More Than You Need, author Mike Piper provides a framework for how to approach the “problem” of having more financial resources than you may need.
Topics include:
- Do you have more than enough?
- Who gets the money?
- Talking with your kids and other heirs
- Giving and spending during your lifetime
- Learning to spend and give more
The value in Piper’s short book is not that it provides an answer key for solving the more-than-enough “problem”. Instead, for those who have saved well and lived within their means, it poses questions for self-reflection and introduces ideas that individuals may wish to consider in conjunction with their advisors, including tax professionals, estate planning attorneys, and financial planners.
Piper is a Missouri Licensed CPA, and the author of several personal finance books and the blog Oblivious Investor.
|