|
Latest Maritime News
4 November 2026
| |
Oil Prices Fall on US Midterm Results & Uncertainty Over Iran Conflict
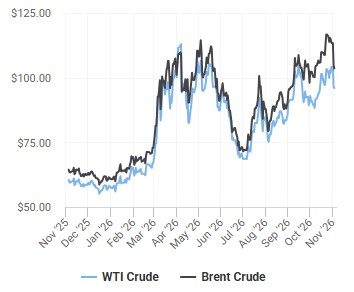
WTI crude is approximately US$94.91 per barrel, down US$1.18, or 1.23%, from Tuesday’s official settlement of US$96.09. Oil is moving lower as investors assess the implications of the U.S. midterm elections and uncertainty surrounding the conflict with Iran.
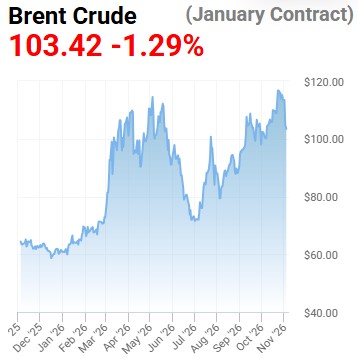
Brent crude is approximately US$101.85 per barrel, down US$1.75, or 1.69%, from Tuesday’s settlement of US$103.60. The international benchmark is extending its decline after closing at a nearly four-week low Tuesday. Continue reading here (Source: EnergyNow).
| |
Hormuz Standoff Leaves Both Sides With Economic Pain
As US President Donald Trump threatens renewed attacks against Iran, Tehran’s intermittent strikes on commercial vessels have left the two sides locked in a painful economic standoff.
For Iran, the US blockade of its oil exports has snuffed out a key part of its military funding and severely hobbled the $300 billion economy, with only a tiny fraction of the prewar 2 million barrels per day are leaving the country via land routes. Continue reading here (Source: gCaptain).
| |
Baltic Dry Bulk Index Sinks to Lowest Level in Weeks As Every Segment Tumbles
The Baltic Exchange's main sea freight index fell to its lowest level in more than two weeks on Tuesday, pressured by weaker rates across all vessel segments.
The main Baltic index was down 58 points, or 2.19 per cent, to 2,590 points — its lowest since October 19. Continue reading here (Source: Baird Maritime).
| |
Why Container Rates Are Climbing Despite Cooling Demand
Container freight rates climbed on major Asia-Europe and trans-Pacific routes last week despite signs of cooling demand, as congestion and canceled sailings supported prices.
Carriers’ accelerating return to the Red Sea is reshaping shipping schedules, analyst and SONAR data contributor Freightos (NASDAQ: CRGO) said in an update, while a potential strike at Los Angeles-Long Beach adds another source of uncertainty for cargo owners. Continue reading here (Source: Freight Waves).
| |
Global Shipbuilding Orderbook Breaks 2008 Record With Output Heading for New Peak
The global shipbuilding orderbook has surpassed its pre-financial crisis record, with the world’s yards set to eclipse their previous production peak next year and expand output still further in 2028.
New figures from Clarksons Research put the backlog at 226.1m compensated gross tonnes (cgt) in October, edging past the September 2008 record of 225.5m cgt. Worth approximately $700bn, the orderbook has grown 24% in the past year and is triple its 2020 level. Continue reading here (Source: Splash247).
| |
Alternative-Fuel Ship Orders Outpace Port Bunkering Infrastructure
Alternative-fuel vessel orders are outpacing the development of the port infrastructure needed to support them, according to a new global study by Lloyd’s Register (LR), highlighting a growing gap between ship capability and fuel availability.
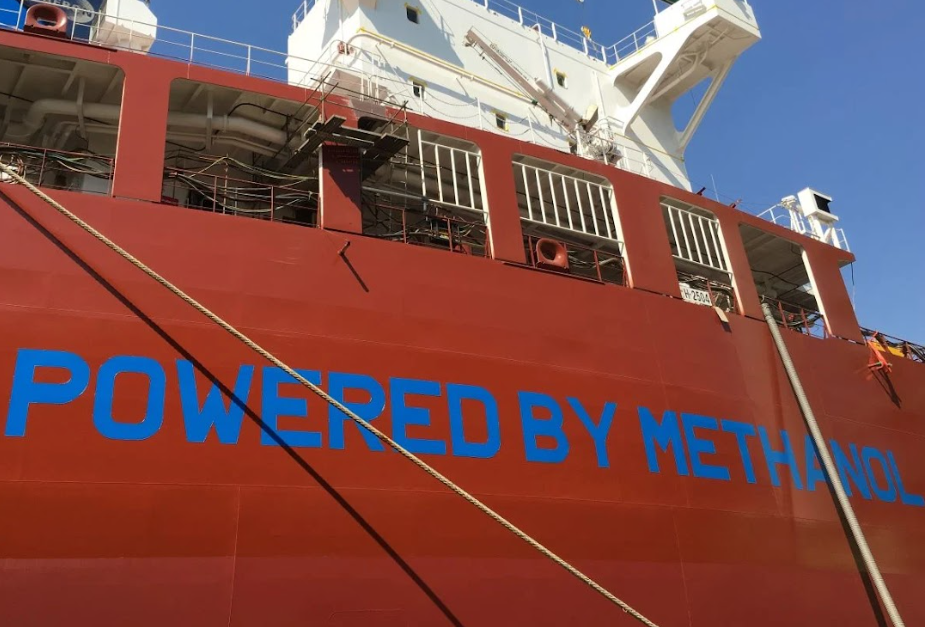
LR’s new Fuel for Thought: Ports report finds that 1,942 alternative-fuel-capable vessels were on order in January 2026, with alternative-fuel ships representing 47% of global orderbook tonnage, according to Clarksons Research. Yet readiness differs sharply by fuel: LNG bunkering was available at 222 ports, compared with just 25 actively offering methanol, while the first commercial ammonia bunkering operation, at Ulsan in South Korea, was completed only in April 2026. Continue reading here (Source: Lloyd's Register).
| |
Long Beach & Los Angeles Ports Study LNG and Methanol As Cleaner Marine Fuels
The ports of Long Beach and Los Angeles have issued a joint report identifying promising cleaner marine fuels for oceangoing vessels and setting out steps to encourage their use at the busiest port complex in the United States, according to the Port of Long Beach. The Clean Marine Fuel Feasibility Assessment, carried out under the ports’ shared Green Shipping Corridor work, examined which fuels the shipping industry calling at the ports is most likely to adopt, how much local demand could develop and what infrastructure would be required. Continue reading here (Source: Global Trade).
| |
Shipping Community Issues Clear Call for IMO Regulation to Turn First-Mover Action Into a Global Transition
Global leaders from across the maritime value chain met in Shanghai this week for the Global Maritime Forum Annual Summit 2026, where much of the discussion centred around the future of shipping’s energy transition.
With the International Maritime Organization’s (IMO) Net-Zero Framework facing a pivotal point in December, the Summit provided a timely opportunity for decision-makers to engage in crucial conversations about the industry’s green transition. By the end of the two days, a clear message emerged that IMO regulation will be essential to accelerating that transition, with many participants voicing support. Continue reading here (Source: Cyprus Shipping News).
| |
Current Price Indications
*Prices are indications only.
| | |
Bangkok, Thailand
HSFO 3.5% (IFO-380cst): N/A
VLSFO 0.5%: USD910/MT
MGO (DMA): USD1,395/MT
| | |
Busan, South Korea
HSFO 3.5% (IFO-380cst): USD925/MT
VLSFO 0.5%: USD1,000/MT
MGO (DMA): USD1,285/MT
| | |
Callao, Peru
HSFO 3.5% (IFO-380cst): N/A
VLSFO 0.5%: USD950/MT
MGO (DMA): USD1,790/MT
| | |
Hong Kong
HSFO 3.5% (IFO-380cst): USD980/MT
VLSFO 0.5%: USD1,020/MT
MGO (DMA): USD1,345/MT
| | |
Houston, TX, USA
HSFO 3.5% (IFO-380cst): USD600/MT
VLSFO 0.5%: USD825/MT
MGO (DMA): USD1,385/MT
| | |
Kaohsiung, Taiwan
HSFO 3.5% (IFO-380cst): USD1,000/MT
VLSFO 0.5%: USD1,055/MT
MGO (DMA): USD1,400/MT
| | |
Long Beach/Los Angeles, CA, USA
HSFO 3.5% (IFO-380cst): USD905/MT
VLSFO 0.5%: USD1,085/MT
MGO (DMA): USD1,625/MT
| | |
Manta, Ecuador
HSFO 3.5% (IFO-380cst): USD770/MT
VLSFO 0.5%: USD965/MT
MGO (DMA): USD1,860/MT
| | |
New York Harbor, NY, USA
HSFO 3.5% (IFO-380cst): USD650/MT
VLSFO 0.5%: USD860/MT
MGO (DMA): USD1,525/MT
| | |
Panama Canal
HSFO 3.5% (IFO-380cst): USD750/MT
VLSFO 0.5%: USD895MT
MGO (DMA): USD1,488/MT
| | |
Singapore
HSFO 3.5% (IFO-380cst): USD910/MT
VLSFO 0.5%: USD1,010/MT
MGO (DMA): USD1,275/MT
| | |
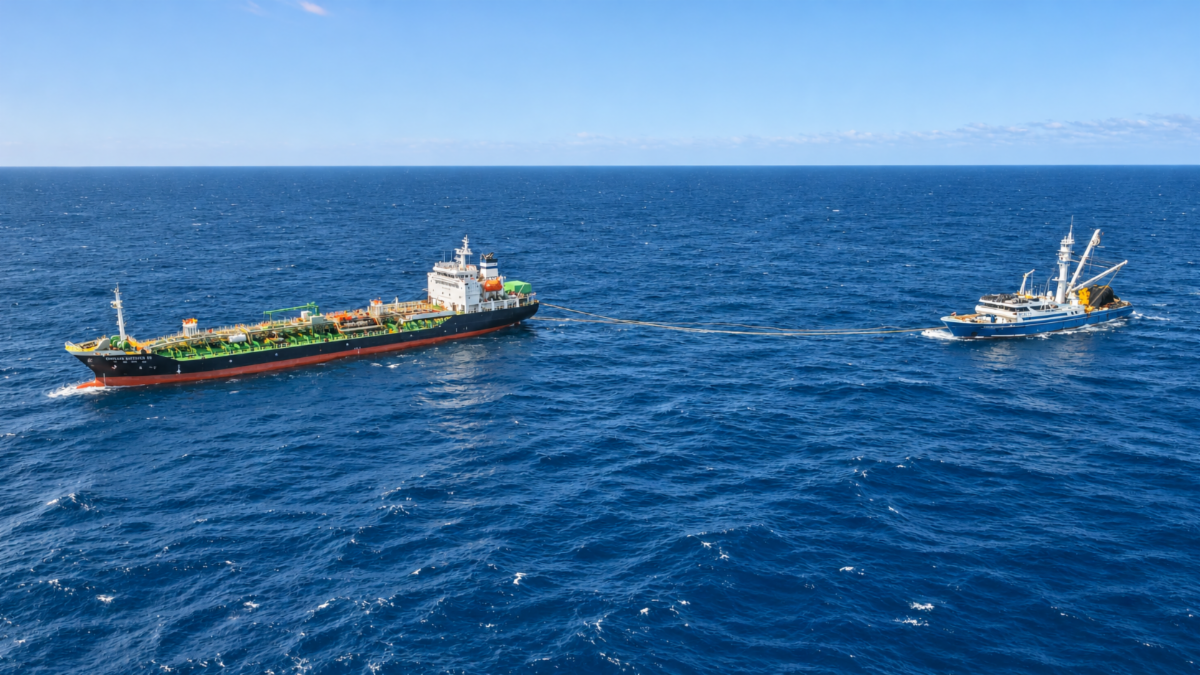
Clipper Oil provides a weekly update on the latest locations of high-seas/offshore fuel tankers operating across the Pacific Ocean and worldwide.
To view the latest positions of our high-seas tankers, please click here.
To be added to our weekly high-seas tanker email distribution list, please click here.
| |  | | | |
Worldwide Wholesalers of
Marine Fuels & Lubricants
| | |
USA Headquarters
2488 Historic Decatur Rd
Suite 250
San Diego, CA 92106 USA
Tel: +1-619-692-9701
| | | |
Singapore Office
3 Coleman Street
#03-24 Box #8
Singapore 179804
Tel: +65-3129-1232
| | |
bunkers@clipperoil.com
www.clipperoil.com
| | | | |