December 11, 2023

We Are Moved Into Our New Space!


Last Wednesday we moved into our new space, Suite 210 of the same building we have been in for over 15 years! We still have some boxes to unpack, pictures to hang and are waiting for the remaining furniture. We are getting to know the Avior Tax Team and look forward to working with them.


We have rebranded to Avior Wealth Management and Tax Services. We have updated our new website and email addresses to reflect the re-brand. The LifeStage emails will redirect to our new Avior addresses.


Check out the following: 

  • Our new updated website www.aviorwealthmncom.
  • Emails from us will now have our first name.last name@avior.com (bruce.kuehl@avior.com) as the domain. We will continue to get emails with the old domain @lifestagewealth.com, so do not worry if you use the old address, it will still get to us.       


To ensure you continue to receive our emails please take the following action:

  • Update your contacts with my our avior.com email address to prevent them from being sent to your spam folder.
  • Ensure that your systems include ‘avior.com’ on your allow list where applicable (e.g., email filtering and spam systems).


New office, new name, new tax services and same great staff! We look forward to hosting an open house in the new year once we are settled in!

The Markets

Still exceeding expectations.


Last week, the United States Treasury market rallied. Yields fell and bond prices rose as some bond market investors enthusiastically embraced the idea that the Federal Reserve will soon change course. Michael Mackenzie and Rich Miller of Bloomberg explained:


“Softening inflation and employment data in the past month have convinced investors that the Federal Reserve is done raising interest rates and ignited bets that cuts of at least 1.25 percentage points are in store over the next 12 months. Treasury yields, which touched highs of 5% as recently as October, have declined sharply, with the U.S. 10-year benchmark sliding more than three-quarters of a percentage point.”


Bond investors were hoping that last week’s unemployment report would show jobs and wage growth slowing in November. Instead, employers added more jobs than expected (199,000 jobs vs. 180,000), and the unemployment rate fell to 3.7 percent.


On Friday, the Treasury market reversed course. Yields on long and short-term Treasury bonds rose sharply and prices fell, reported Karishma Vanjani of Barron’s.


The employment report also showed that average hourly earnings increased in November – rising 4 percent year-over-year. Wages have risen faster than inflation for seven months, reported Sarah Foster of Bankrate. However, many workers are still feeling a pinch. 


“While inflation has come down, broadly speaking, prices have not. There is a kind of continuing, virtual sticker shock that continues to weigh on the minds and pocketbooks of consumers that is meaningful,” according to Senior Bankrate Economic Analyst Mark Hamrick.


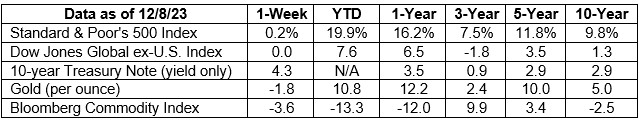
Last week, the Standard & Poor’s 500 Index gained for the sixth consecutive week, according to Bloomberg, and yields on most maturities of U.S. Treasuries moved higher.

american-flag-building.jpg

Americans Agree On Some Things

The Old-Age, Survivors and Disability Insurance (OASDI) program plays a significant role in the lives of many Americans. In 2022, it provided monthly benefits to 51 million retired workers and their dependents, 9 million disabled workers and their dependents, and the dependents of 6 million deceased workers.


In 2022, the program spent $1.24 trillion and took in $1.22 trillion. From here on out, the program’s spending is expected to exceed its funding. Under current assumptions, the trust fund will be depleted by 2034 – unless something changes.


An issue brief from the American Academy of Actuaries (AAoA) stated, “If Congress has not acted by 2034, we will be faced with an automatic 20% cut in benefits to people already receiving benefits, the need to immediately increase Social Security taxes by 25%, or some combination of cuts in benefits and increases in taxes.” The AAoA discussed options for keeping Social Security solvent, including:


  • Increase the payroll tax rate by 25 percent. Currently, the payroll tax rate is 15.3 percent on up to $160,200 of a workers’ income. The worker pays half, and the employer pays half. This would cover 100 percent of the 2034 shortfall.
  • Raise or eliminate the wage limit ($160,200 in 2023). This would cover 36 percent to 78 percent of the 2034 shortfall.
  • Increase Social Security’s investment income by investing a portion of the money raised through taxes in equities.
  • Tax Social Security benefits similarly to the way pensions are taxed. This would cover 8 percent of the 2034 shortfall.
  • Reduce benefits for higher income recipients who are not yet eligible for benefits. This would cover 10 percent or less of the 2034 shortfall.
  • Raise the retirement age for future recipients. If normal retirement age is raised to 69 by 2034, it would cover about 10 percent of the shortfall.


Many Americans are concerned about the future of Social Security. According to a survey conducted by Republican firm North Star Opinion Research, Democratic firm Global Strategy Group, and the nonpartisan Peter G. Peterson Foundation:


  • 97 percent of Democratic participants and 97 percent of Republican participants want Congress to “reform Social Security and ensure it’s available for current retirees and younger generations.”


It’s uncertain whether Congress will address Social Security funding before automatic cuts take place. If you would like to talk about the role of Social Security in your retirement plan, please get in touch.

thinking_girl_idea.jpg

Weekly Focus - Think About It


“If it's your job to eat a frog, it's best to do it first thing in the morning. And if it's your job to eat two frogs, it's best to eat the biggest one first.”

—Mark Twain, writer and humorist

Bruce Kuehl | 763.542.8884 | bruce.kuehl@avior.com

Investment management and financial planning services offered through Avior Wealth Management, LLC a registered investment advisor. Investments involve varying degrees of risk and there can be no assurance that the future performance of any investment or investment strategy will be profitable or equal past performance results. All investments subject to loss including the loss of principle. Nothing contained herein should be construed as tax advice. Specific, individual tax questions should be asked of your CPA or accountant.