|
Market Navigator for the Quarter Ending December 31, 2025
Presented by Austin Fearon
December was a mixed month for markets due to a late month sell-off. Despite the volatility to end the period, 2025 was still a strong year for investors, as most major stock indices notched double-digit returns for the year. Looking ahead, continued economic growth and market appreciation are expected in 2026.
1. Beyond the Headlines: Mixed December Caps Off Strong Year
2. Falling Interest Rates: Stocks and Bonds Benefit
3. Economic Report Updates: Solid Growth with Potential Risks
4. Looking Ahead: Continued Growth and Appreciation
Beyond the Headlines: Mixed December Caps Off Strong Year
December closed out 2025 on a muted note for U.S. stocks. The Nasdaq slipped modestly, while the S&P 500 and Dow Jones Industrial Average posted small gains. Despite this quiet finish, the full-year picture was far more encouraging: all three major U.S. indices delivered double-digit returns, supported by resilient corporate earnings and easing financial conditions.
The S&P 500 gained 0.06 percent in December, 2.66 percent in the fourth quarter, and 17.88 percent for the year. The Dow was up 0.92 percent in December, 4.03 percent for the quarter, and 14.92 percent for the year. Finally, the Nasdaq Composite lost 0.47 percent in December but gained 2.72 percent for the quarter and 21.14 percent for the year.
These strong results were driven by healthy fundamentals. Earnings growth remained impressively resilient in 2025, and this is expected to continue into 2026. Average earnings growth for the S&P 500 was more than 15 percent in the third quarter, which was more than double analyst estimates. Technical factors were supportive as well, with all three indices finishing the year well above their respective 200-day moving averages.
International stocks outperformed their domestic counterparts for the month and year. Developed and emerging markets both rallied in December, capping off a strong year for international investors. The MSCI EAFE Index gained 3.00 percent for the month, 4.86 percent for the quarter, and an impressive 31.22 percent for the year. The MSCI Emerging Markets Index did even better, up 3.02 percent for the month, 4.78 percent for the quarter, and 34.36 percent for the year. Foreign stocks were supported by a weaker dollar and renewed investor appetite for international companies throughout the year, as well as solid technicals.
Falling Interest Rates: Stocks and Bonds Benefit
Fixed income investors enjoyed a strong year as falling interest rates boosted bond prices. The Bloomberg U.S. Aggregate Bond Index fell 0.15 percent in December but gained 1.10 percent in the fourth quarter and a strong 7.30 percent for the year.
Even high yield did well, driven by tightening credit spreads. The Bloomberg U.S. Corporate High Yield Index gained 0.57 percent in December, 1.31 percent in the quarter, and a strong 8.62 percent for the full year.
The 10-year Treasury yield dropped from 4.57 percent at the start of the year to 4.17 percent by year-end, while short-term rates followed suit. This falling rate environment was driven in part by three Federal Reserve rate cuts in the final months of the year, as policymakers shifted focus toward supporting employment amid signs of labor market cooling. Looking forward, markets expect to see between two to three additional rate cuts in 2026; however, the timing on any potential cuts remains uncertain.
The Takeaway
· Bond returns were positive for the quarter and year, supported by falling interest rates.
· Investors and economists expect to see between two to three interest rate cuts in 2026.
Economic Report Updates: Solid Growth with Potential Risks
We continued to receive sporadic economic data releases in December as multiple federal agencies struggled to resume their regular schedule of updates following the conclusion of the federal government shutdown earlier in the fall. The updates that we did receive largely showed signs of continued economic growth.
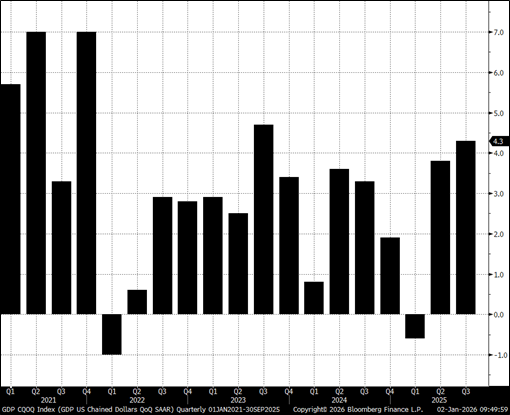
The highlight was the first look at GDP growth in the third quarter, which came in well above expectations. As seen in Figure 1, the 4.3 percent annualized growth rate marked the best quarter for economic growth in more than two years. Encouragingly, personal consumption growth was a major driver of overall economic growth in the quarter.
Figure 1: GDP U.S. Chained Dollars, Quarter over Quarter, Seasonally Adjusted Annualized Rate, January 2021–Present
|