|
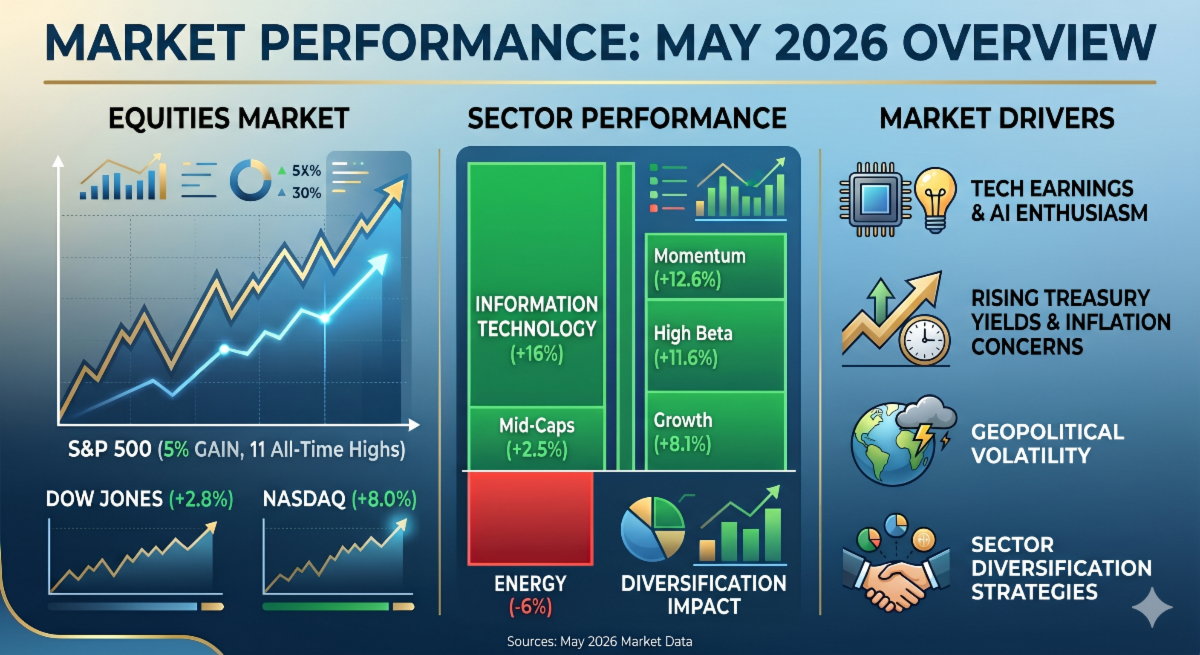
While the broader market indices celebrated consecutive months in plus territory, the internal dynamics of May revealed a highly concentrated market environment. The "Great Rotation" into smaller companies that we highlighted earlier this year took a temporary breather, as mid- and small-cap equities lagged behind their large-cap peers.
The S&P MidCap 400® posted a modest gain of 2%, while the S&P SmallCap 600® rose just 1%. These segments faced distinct headwinds, weighed down by persistent inflation worries and climbing Treasury yields.
Sector performance remained heavily polarized as investors shifted their focus squarely back to previous leaders:
Information Technology Surge: The tech sector was the ultimate standout leader, surging an incredible 16% over the month—notably becoming the sole sector to outperform the broader S&P 500.
Energy Slump: In a sharp reversal of its strong first-quarter run, the Energy sector declined by 6% as global oil prices slumped.
From a factor perspective, Momentum, High Beta, and Growth retained their dominant spots at the top of the leaderboard. The outperformance of the S&P 500 Momentum index—heavily driven by the rally in mega-caps and tech—was particularly notable, bringing its year-to-date gains to an impressive 27%. Check the details in the upcoming Monthly Economic Update to see how these factors are influencing your portfolio's trajectory.
See this month's GRAnderson Wealth Management Economic Update for details.
|