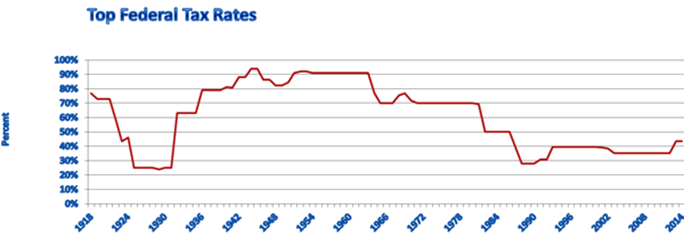
Trying to tax impact future distributions is speculative because there are so many unknown variables. Looking back at the history of tax rates from 1913 – 2014, there have been numerous changes in tax rates. Other changes have also occurred in capital gains rates, AMT, personal exemptions, and the taxation of Social Security. Currently, the top marginal tax rate is 39.6%, but that is subject to change in the future.
Certainly, the tax consequences to each party should be taken into consideration in equitable distribution, so that neither party gains an unfair advantage. But unless the distributions are subject to payment or liquidation in the short term, an accurate calculation is almost impossible to do with any precision because there are so many unknown variables.
Let’s look at a short-term example: Don and Mary have $25,000 of joint credit card debt that they agree to pay off. Neither party has excess cash, so it is decided that Mary will assume the debt and use a portion of Don’s 401K that she will be awarded to pay off the debt. Mary is 50 years old and in the 25% tax bracket. She will be able to avoid the 10% early withdrawal penalty if the money is withdrawn directly from the employer plan; however the distribution will still be subject to the 20% IRS mandatory tax withholding by Don’s employer.
Mary needs to remove $31,250 from the retirement plan assets she is awarded to net the $25,000 for the credit card payoff. This is an additional $6,250. A tax calculation can be performed to determine Mary’s effective tax bracket for the year (which will be lower than her marginal tax rate). She may not owe any additional tax, and could even receive credit if her effective tax bracket comes in below 20%.
Because this transaction will occur within a few months after the divorce and all the variables are known, it would be prudent to tax effect this portion of the 401K plan to cover the tax implications of the withdrawal.
Let’s look at a long-term example: Mary will be awarded the marital residence with an equity valuation of $280,000, and in exchange, Don will retain one of his retirement accounts. Don is age 54 and in the 35% tax bracket. He feels that he should receive a greater amount of retirement assets to offset the projected cost of the unpaid taxes from that account. Based on an estimated effective tax bracket of 27%, Don is suggesting that the retirement assets he receives be tax adjusted to $383,000.
Don plans to continue working until age 65, which means he will not begin to take distributions, nor pay taxes on this account for another 11 years. He should benefit from continued tax-deferral and accumulation of growth on the investments in this account. So the ultimate value of this account to produce future income may well exceed the costs associated with taxes that will be utimately paid. There are also other unknown variables which cannot be predicted such as: what tax bracket Don will be in when he begins to withdraw funds; the annualized rate of return on the assets; the impact of current/future inflation rates; and the ability to stretch withdrawals over a number of years, allowing for the continued growth on the account.