The-Lead-Left-logo-with-PC_Newsletter image

PDF | Research | Week of January 29, 2024

Quote of the Week

“For the last 24 months, there has been a disconnect on valuation expectations between buyers and sellers. There is now a real sense of pragmatism setting in.”

– Anna Skoglund, head of financial and strategic investor group, EMEA,

Goldman Sachs.


New: Private Capital Call Podcast


Episode 3: Mickey D. Levy, Macro Economist

"I believe the U.S.’s favorable characteristics will lead it forward and I remain positive." - Mickey D. Levy

Listen Now

Four for ’24 (Last of a Series)

all-bong-L2oedF1AsH8-unsplash-scaled image

4. Next Gen Private Capital: Financing technologies, the next phase of applications.


In the absence of fully functioning public markets during the Fed’s intense anti-inflation campaign, liquidity was drained, not just from the economy but from bank reserves, trading desks, CLO formation and retail fund flows. Of course, this was in addition to the decades-long effort by regulators to discourage banks from holding leveraged loans on their balance sheets. 


The result was the steady disintermediation of buyout financings away from broadly syndicated loan and high-yield bond markets to private credit managers. There issuers had the benefit of quick execution without relying on a syndication process and price certainty with managers holding (not distributing) debt. Simultaneously investors enjoyed the higher premiums, better protections, tighter terms, and consistent returns afforded by less correlated assets. 


Lower interest rates will likely create better conditions for liquid loans as the improved equity arbitrage for CLOs supports more vehicle formation. It’s a fairly typical feature of the cycle to then have banks invade the higher end of the middle market, borrowers with Ebitda below $100 million, with higher leverage, unitranche, cov-lite structures, and tighter pricing...

Read More

Chart of the Week

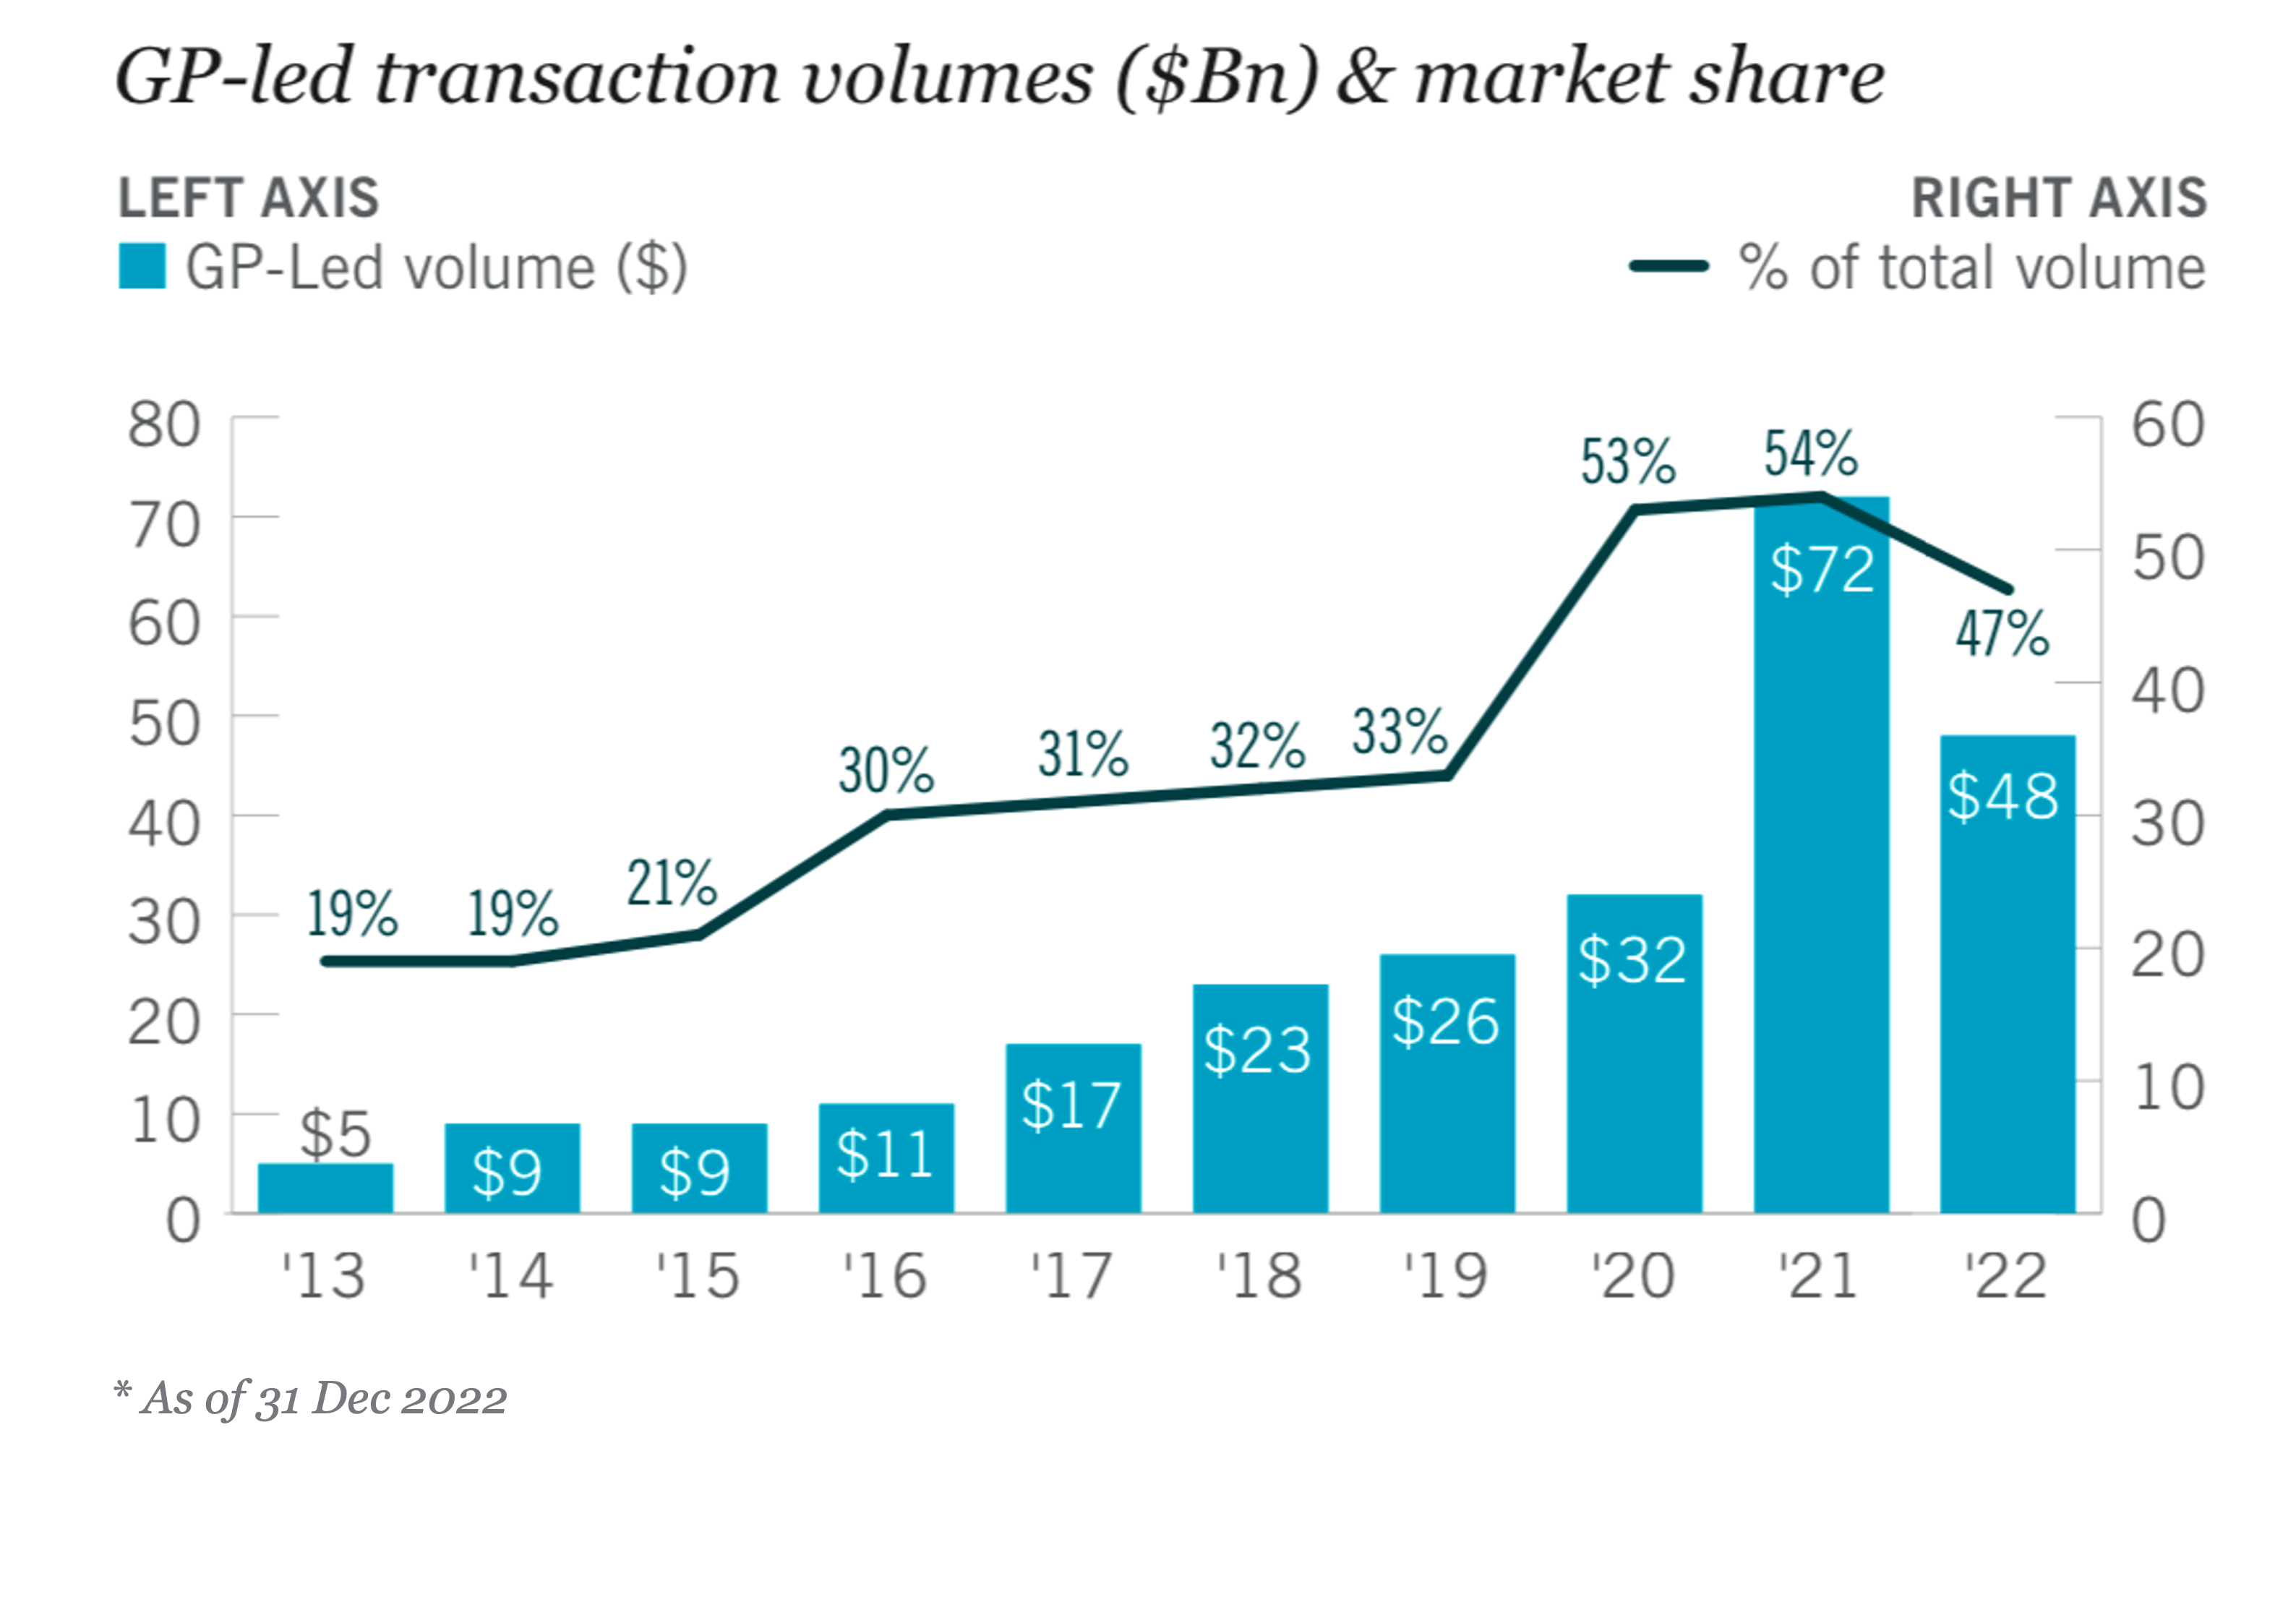
Primary in the Secondaries

The share of GP-led equity secondaries has peaked relative to LP-leds.

CTW-0129 image

Source: Jefferies

(Past performance is no guarantee of future results.)

February 6 & 7, 2024

Encore at the Wynn in Las Vegas, NV

SFNet’s Asset-Based Capital Conference 2024

Doing What We Do Best

Learn More

#SFNetABCC24

Lead with Your Left

 
30-DAY FREE MEMBERSHIP


Join the leading voice of the middle market. Try us free for 30 days.
Learn More
 

Stat of the Week

Jan-29-2024-Stat-edited image

Loan Stats at a Glance 

PitchbookLCD-Logo-for-newsletter image
LCD-24-01-29-1024x486 image

Contact: Ryan Brown / PitchBook LCD

PDI Picks

Life after the fundraising slump

PDI-0129-1024x697 image

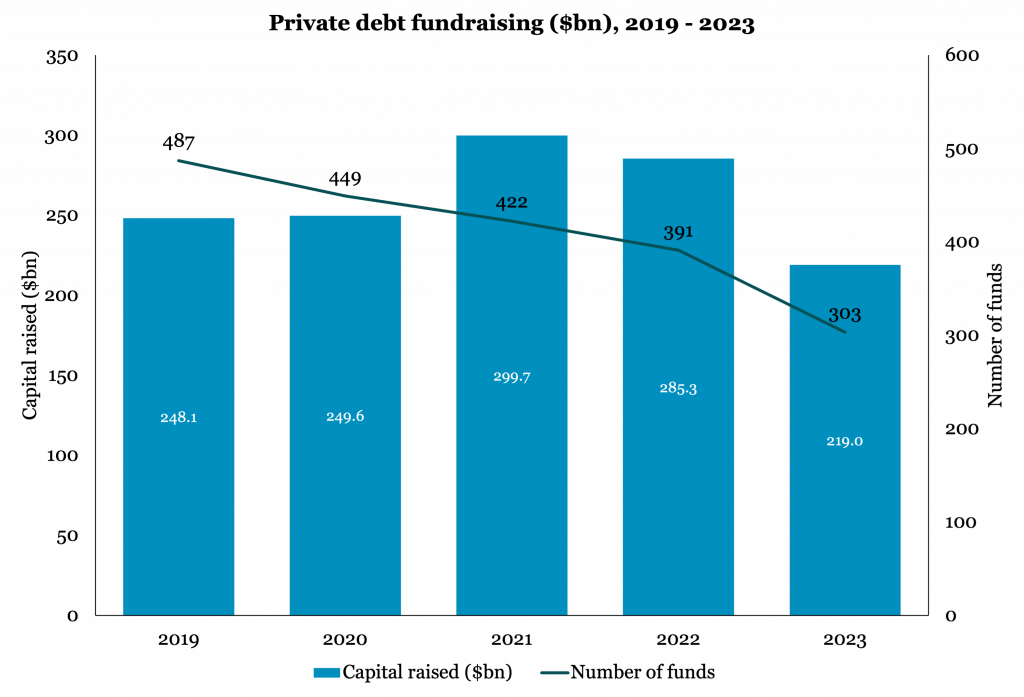
All private markets, including private credit, experienced a tough 12 months on the fundraising trail in 2023. Hopes are higher for the year ahead. 

The fundraising figures are in for full-year 2023 and they reveal a drop in global private credit capital accumulation to just $219 billion, the lowest amount seen in a PDI Fundraising Report since 2016 when $180 billion was raised. The number of fund vehicles raised fell to 303, the lowest figure seen since 2012...

Read More

Leveraged Loan Insight & Analysis

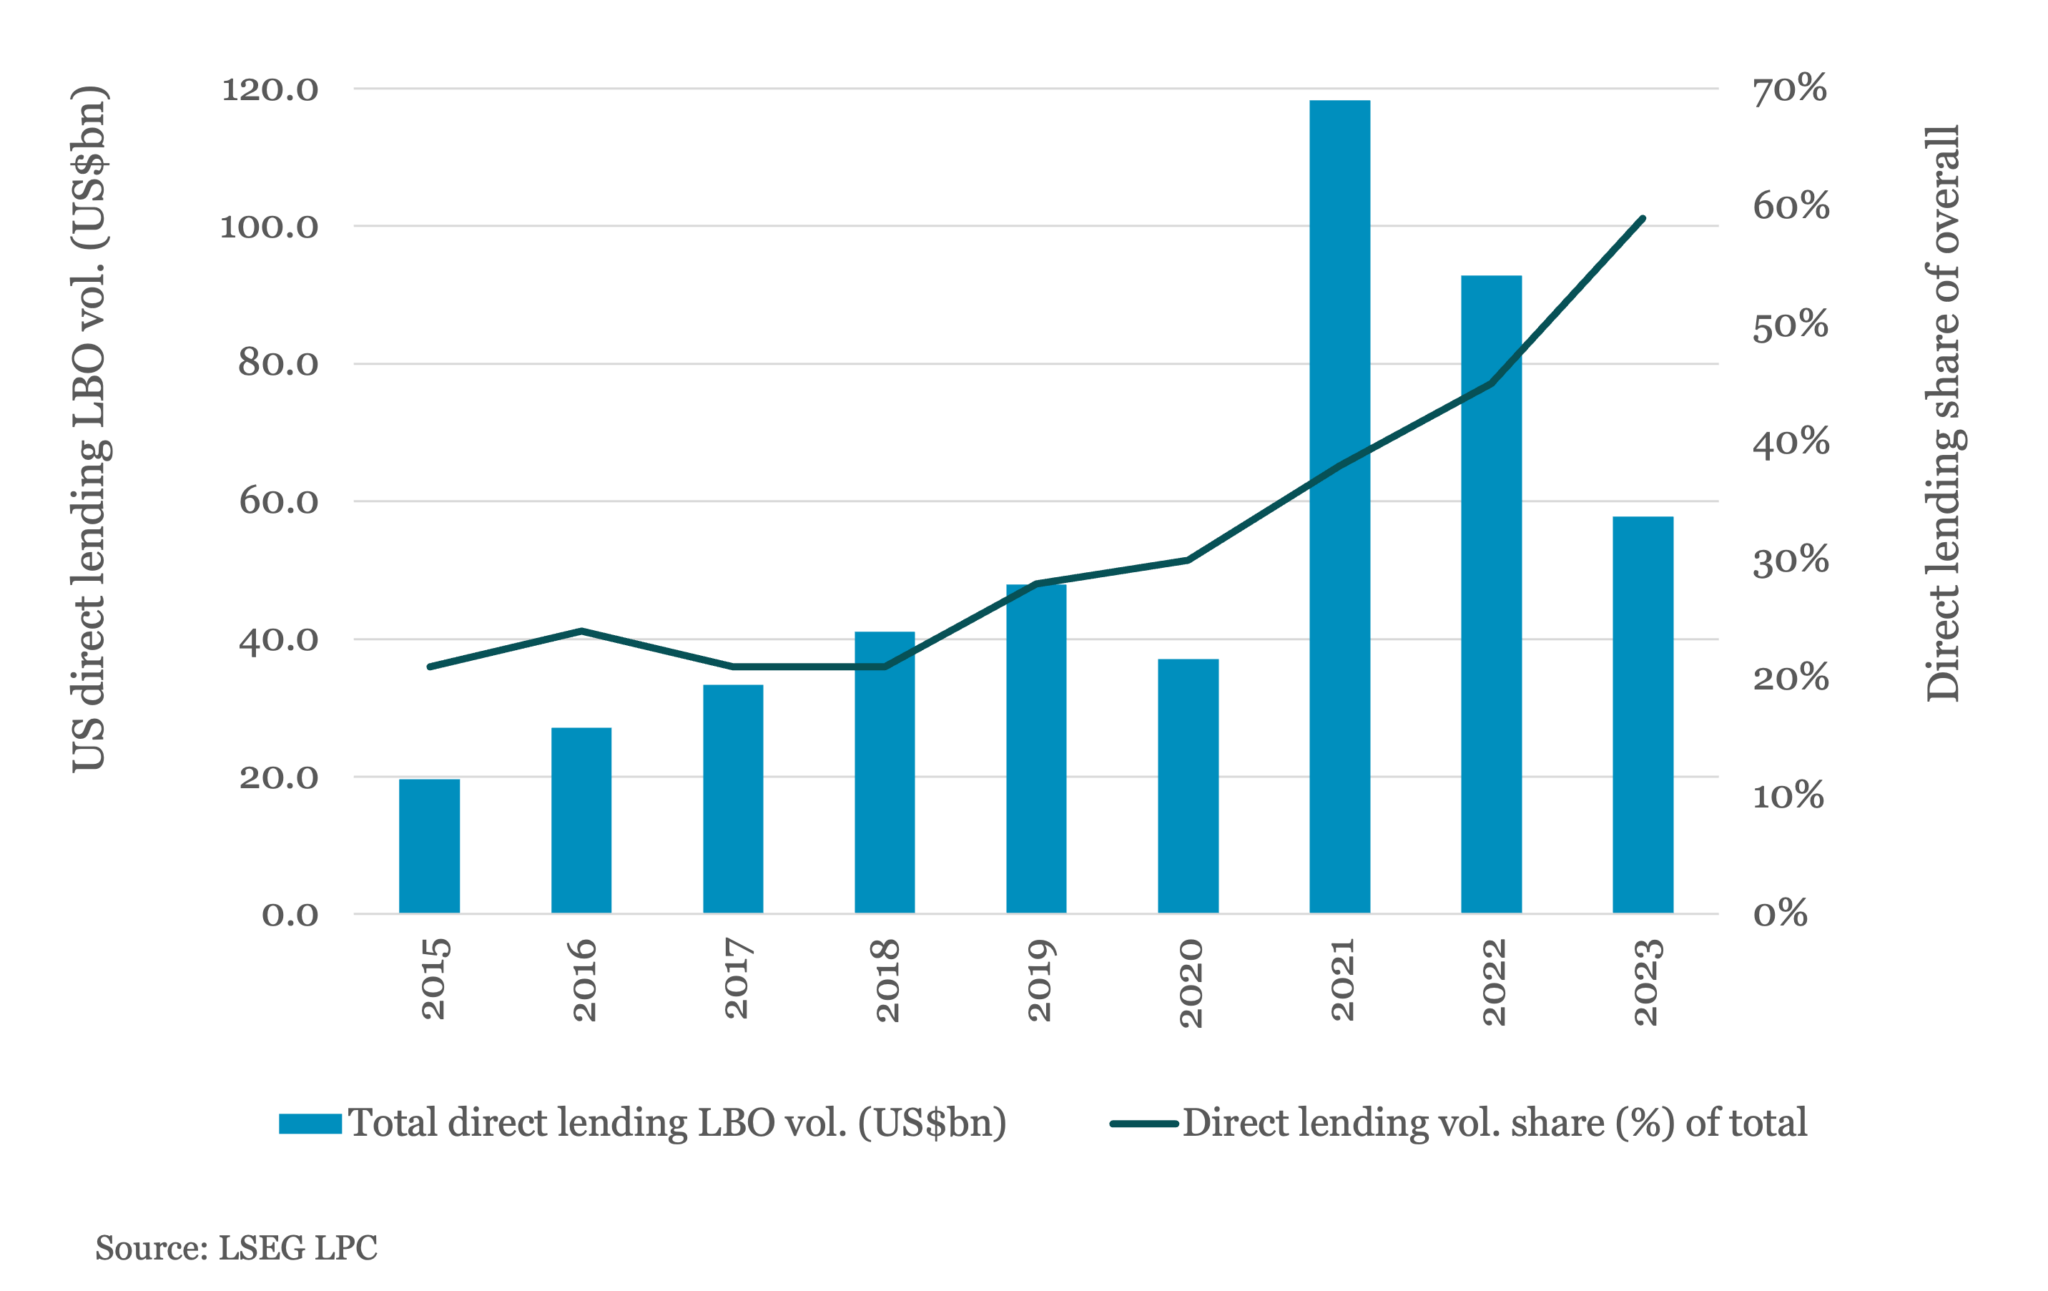
Daily Analytic: Direct lending comprised 59% of US LBO volume in 2023

lseg-0129-1-2048x1291 image

Execution risk drove more LBO issuers towards the direct lending market last year. US direct lending LBO volume totaled US$57.8bn in 2023, 38% lower year-over-year. Last year's total comprised 59% of overall US LBO loan volume, easily an all-time high, topping 2022's 45% share...

Read More

Contact: David Puchowski / LSEG

The Pulse of Private Equity

A quarter of megafunds

PB-0129-v3-2048x1520 image
Download  Data & Report

Contact: Garrett Black / PitchBook

KBRA Direct Lending Deals: News & Analysis

DLD-Logo image

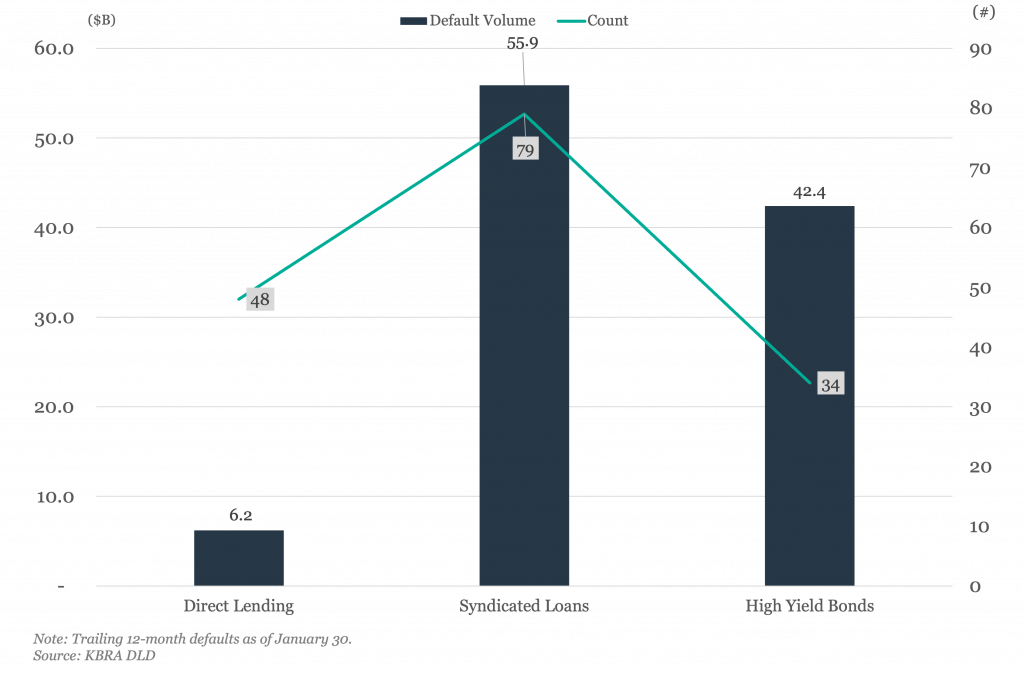
TTM Default Volume, Count

KBRA-0129-1024x673 image

Contact: Eric Rosenthal / KBRA DLD

Middle Market & Private Credit

Fitchratings-for-newsletters image

U.S. Middle Market CLO Snapshot (4Q23)

Overall credit quality across U.S. middle market (MM) CLOs under Fitch Ratings’ surveillance remained stable throughout 2023 with muted defaults, while exposure to assets rated ‘CCC+’ or below increased, according to the latest U.S. MM CLO Snapshot...

Read More

Contact: Winnie Fong / FitchRatings

Covenant Trends 

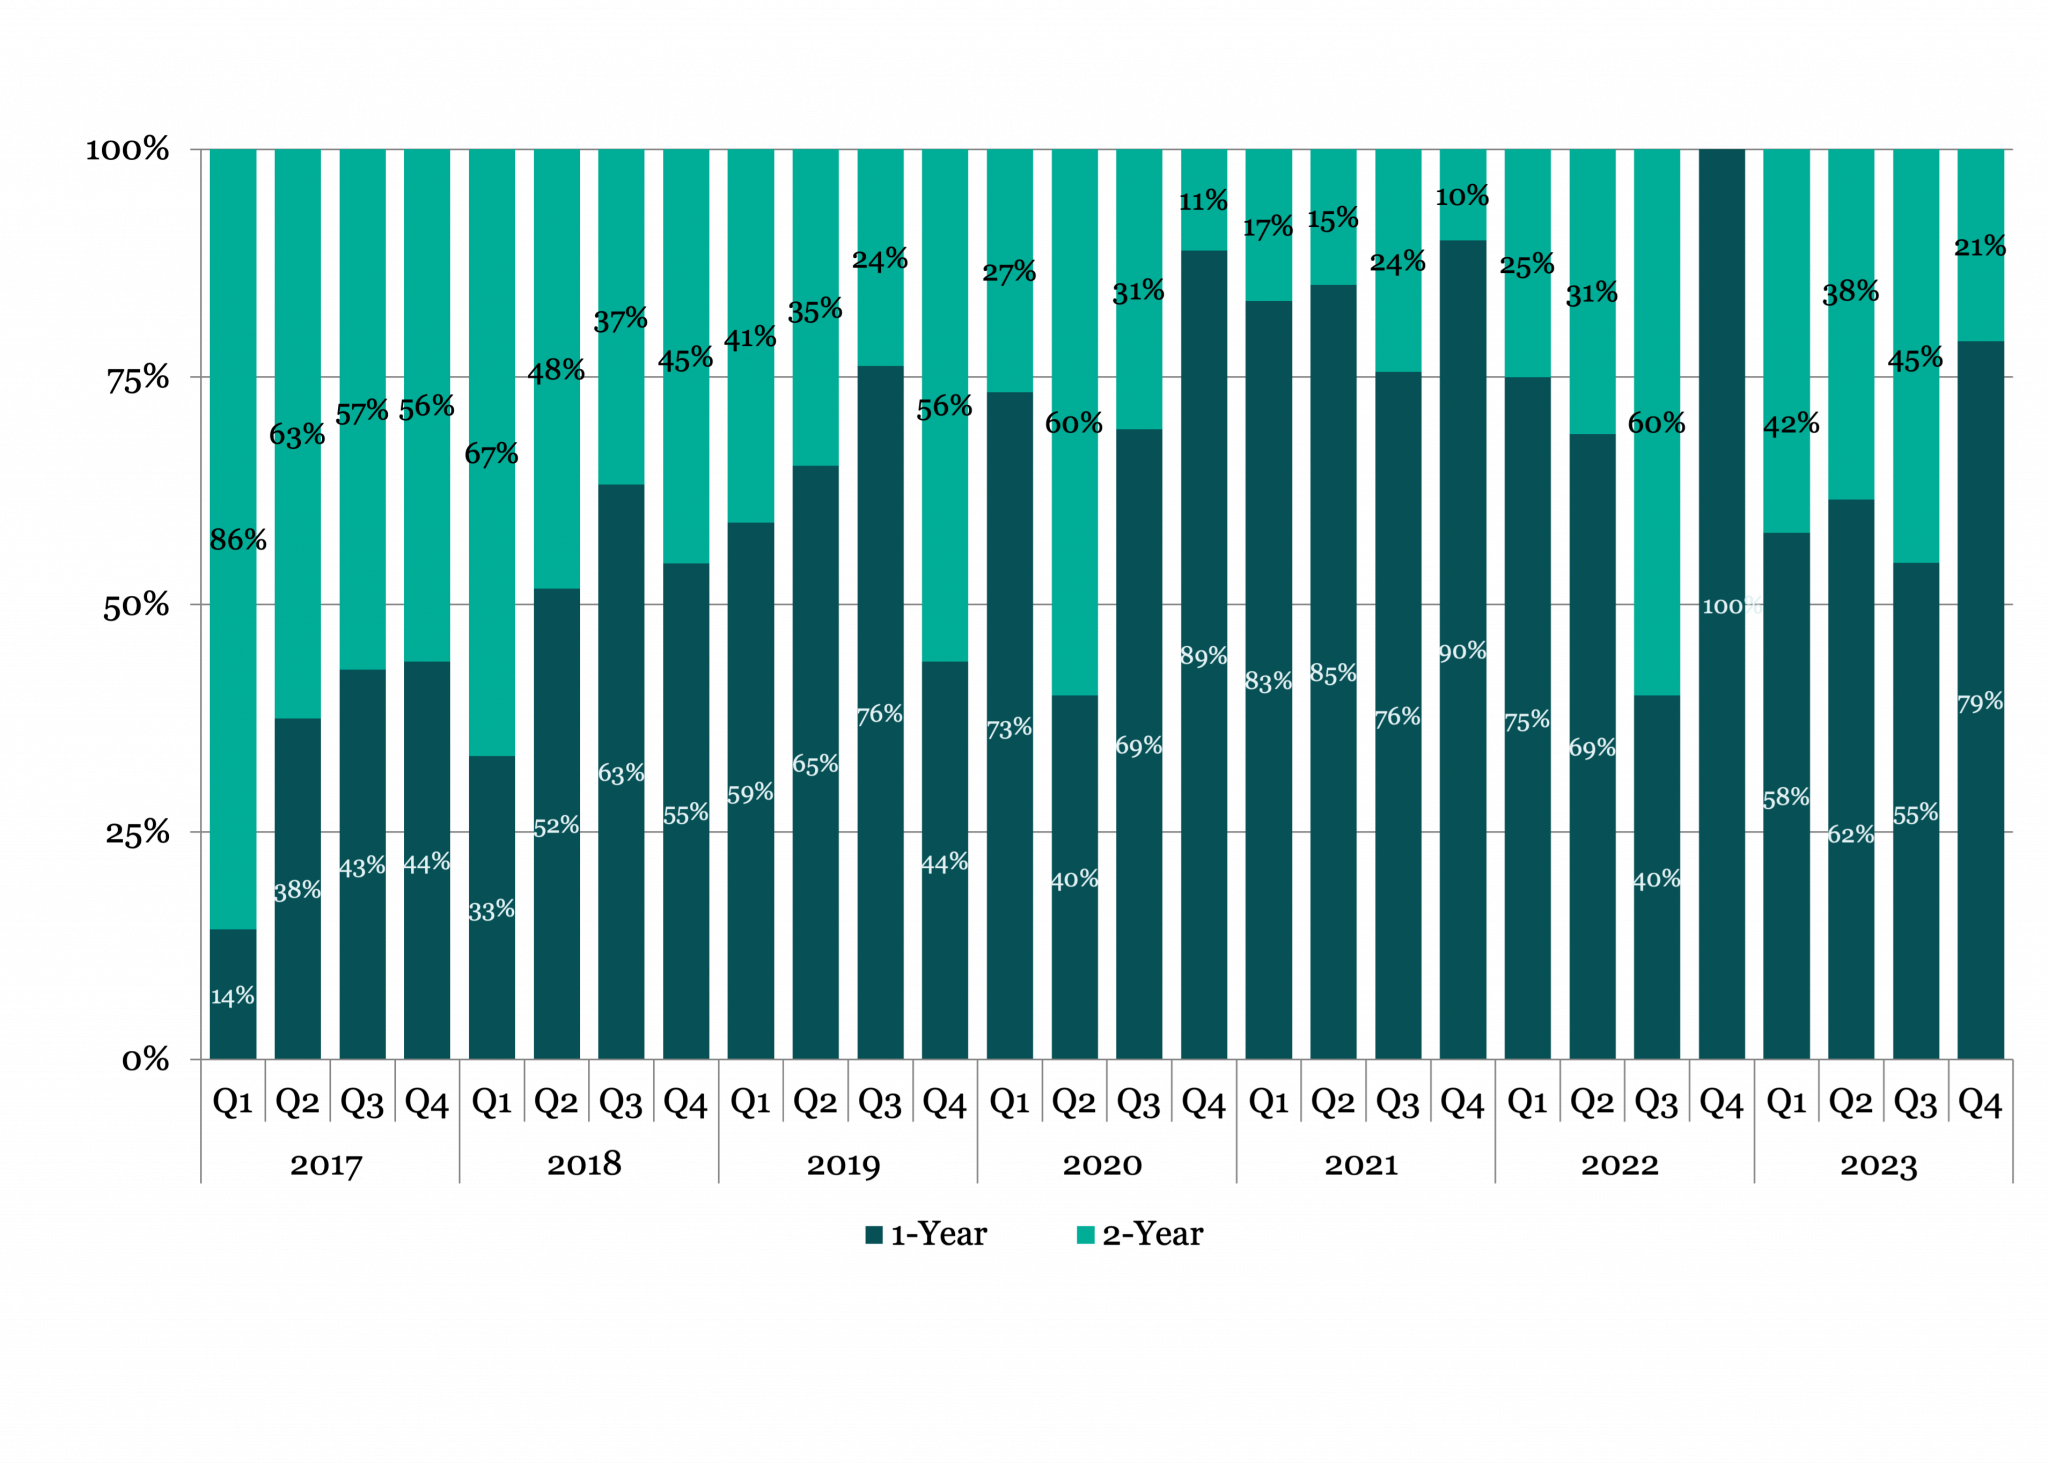
Distribution of MFN Maturity Carveout Horizons

CR-0129-2-2048x1463 image
Download Data

Contact: Steven Miller / Covenant Review

High-Yield Bond Statistics

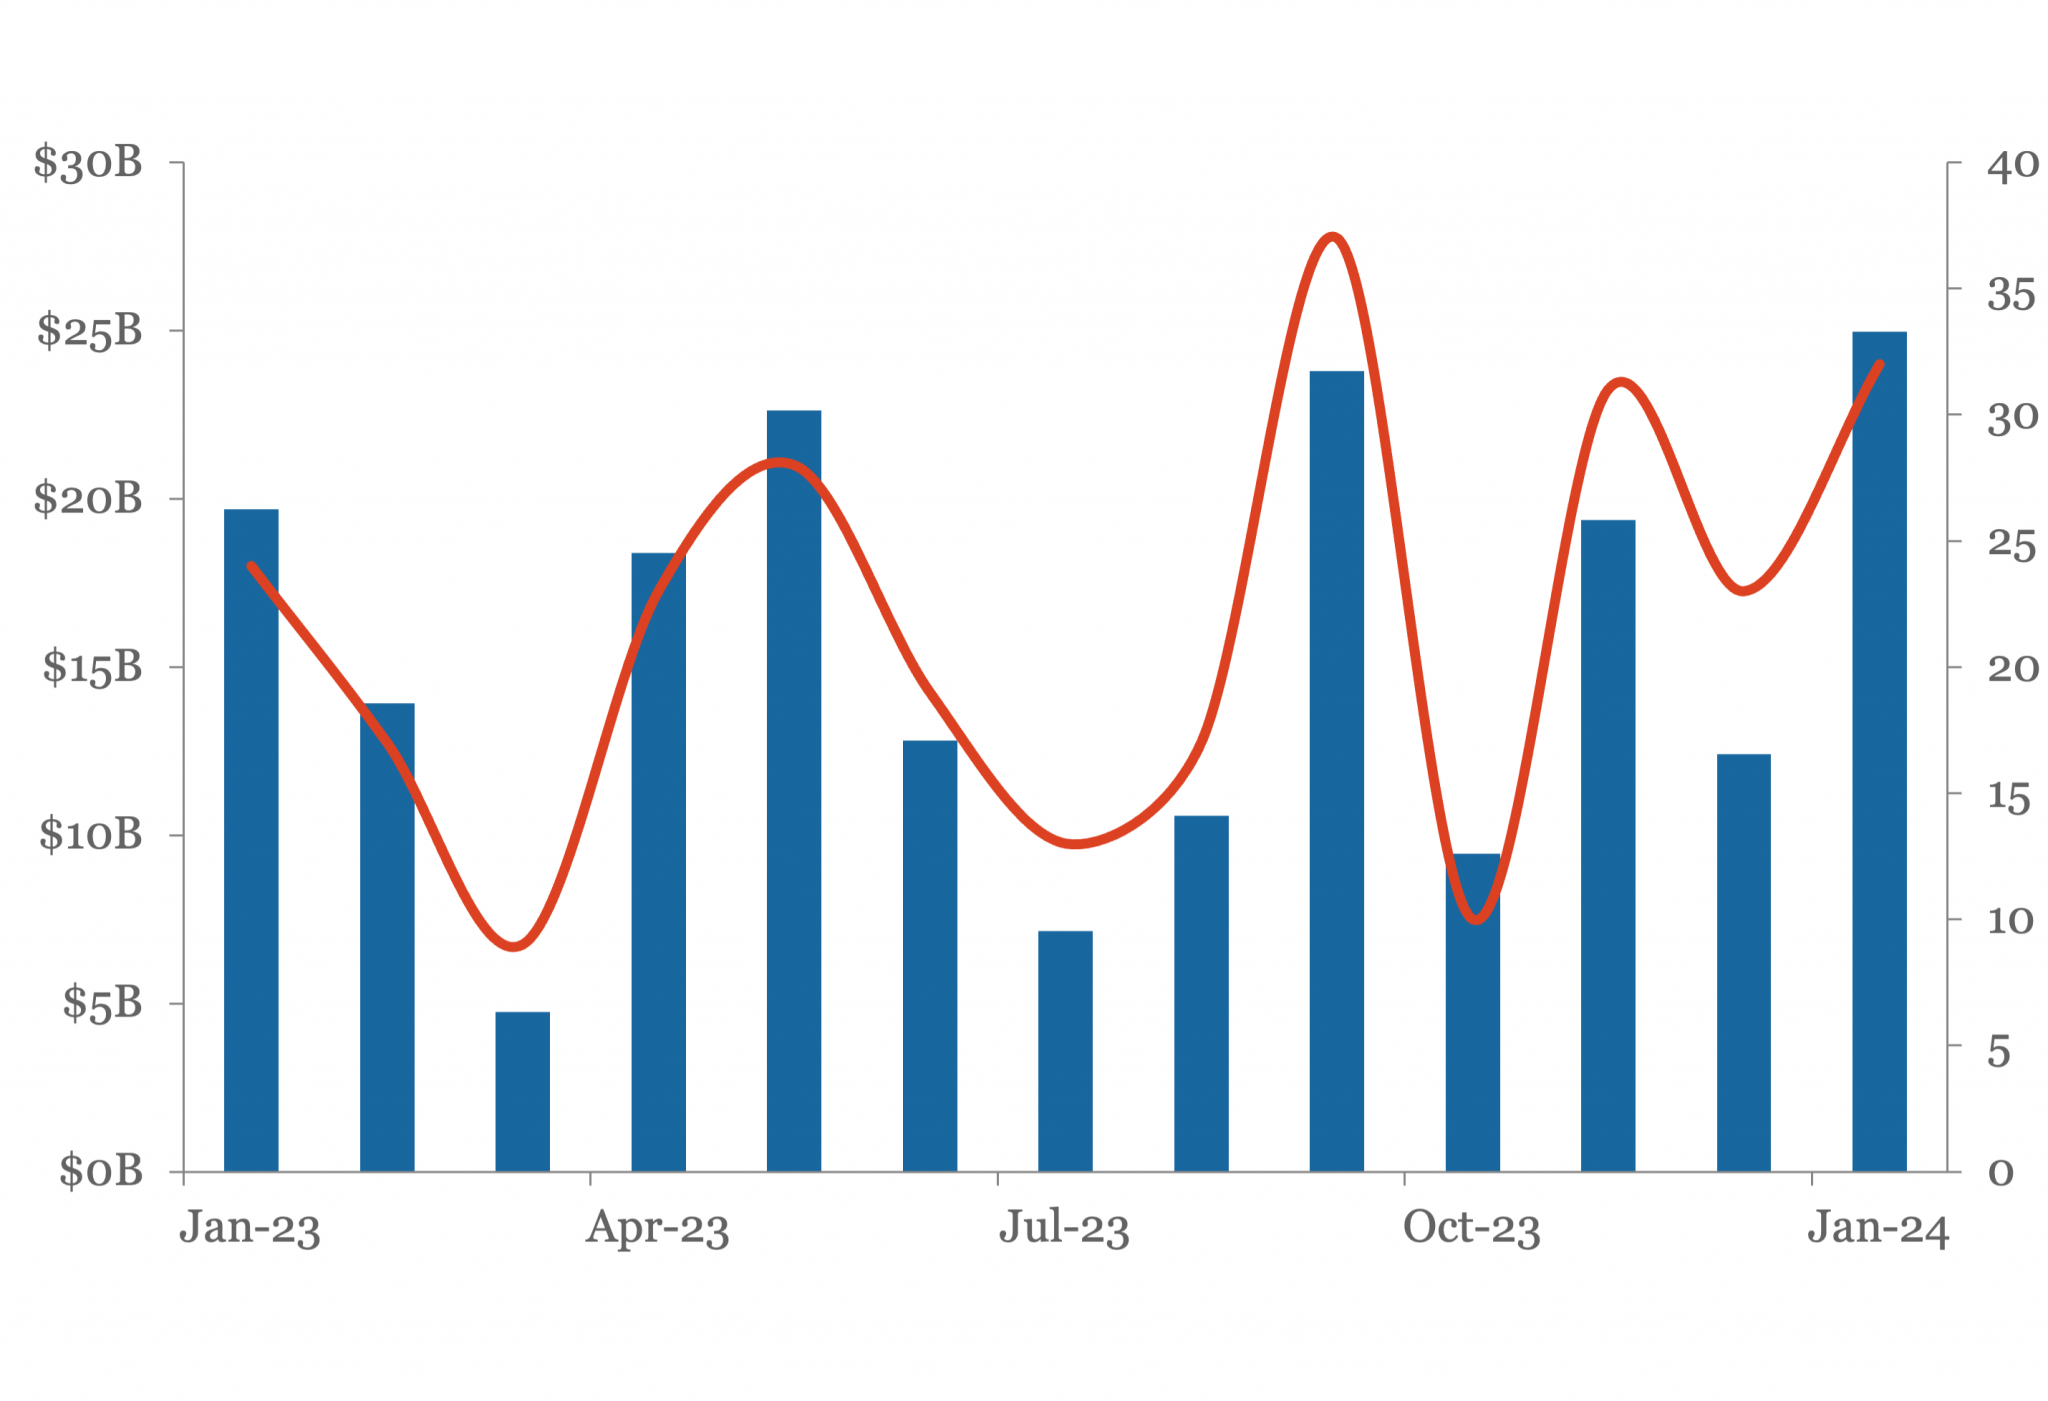
Launched Volume

LFI-LV-0129-2048x1401 image

New-issue Yields

LFI-NIY-0129-2048x1299 image

Weekly Fund Flows

LFI-WFF-0129-2048x1348 image

Weekly fund flows source: Lipper

Download Data

Contact: Robert Polenberg / LevFin Insights

Debtwire Middle-Market

debtwire-0122-3-1024x647 image

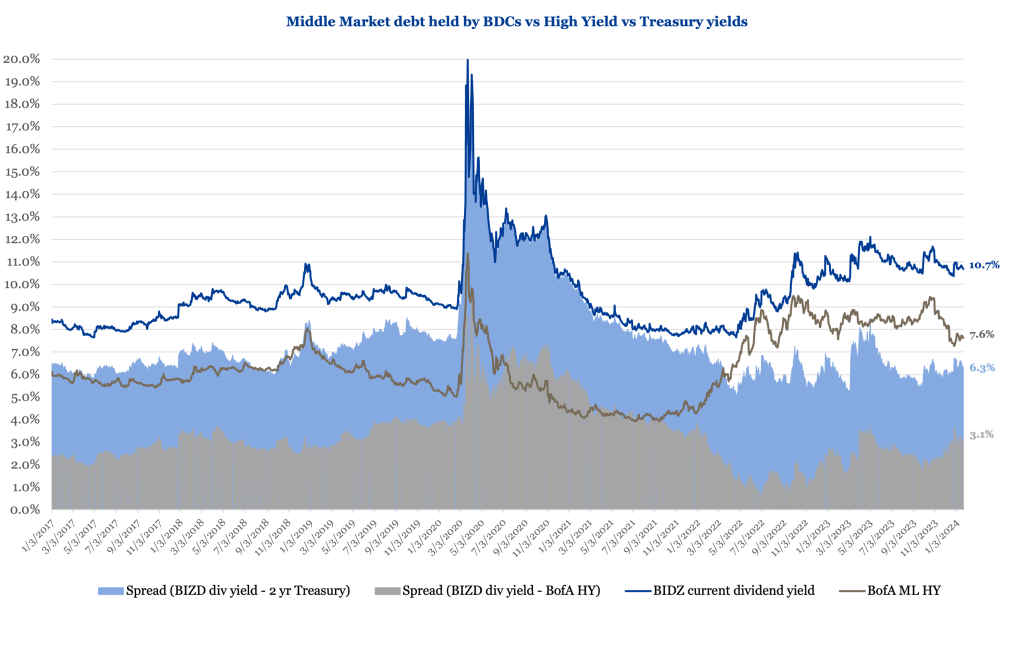
The blue line in the chart is the current dividend yield of the *VanEck BDC Income ETF (currently at 10.7% as of 22 January, down from the highest level in last 12 months of 12.1% in May 2023) that tracks the overall performance of publicly traded business development companies (BDCs, lenders to privately held middle-market businesses that tend to be below investment grade or not rated, with most lending comprising of senior secured loans)...

Read More & Download Data

Contact: Suneet Chandvani / Debtwire 

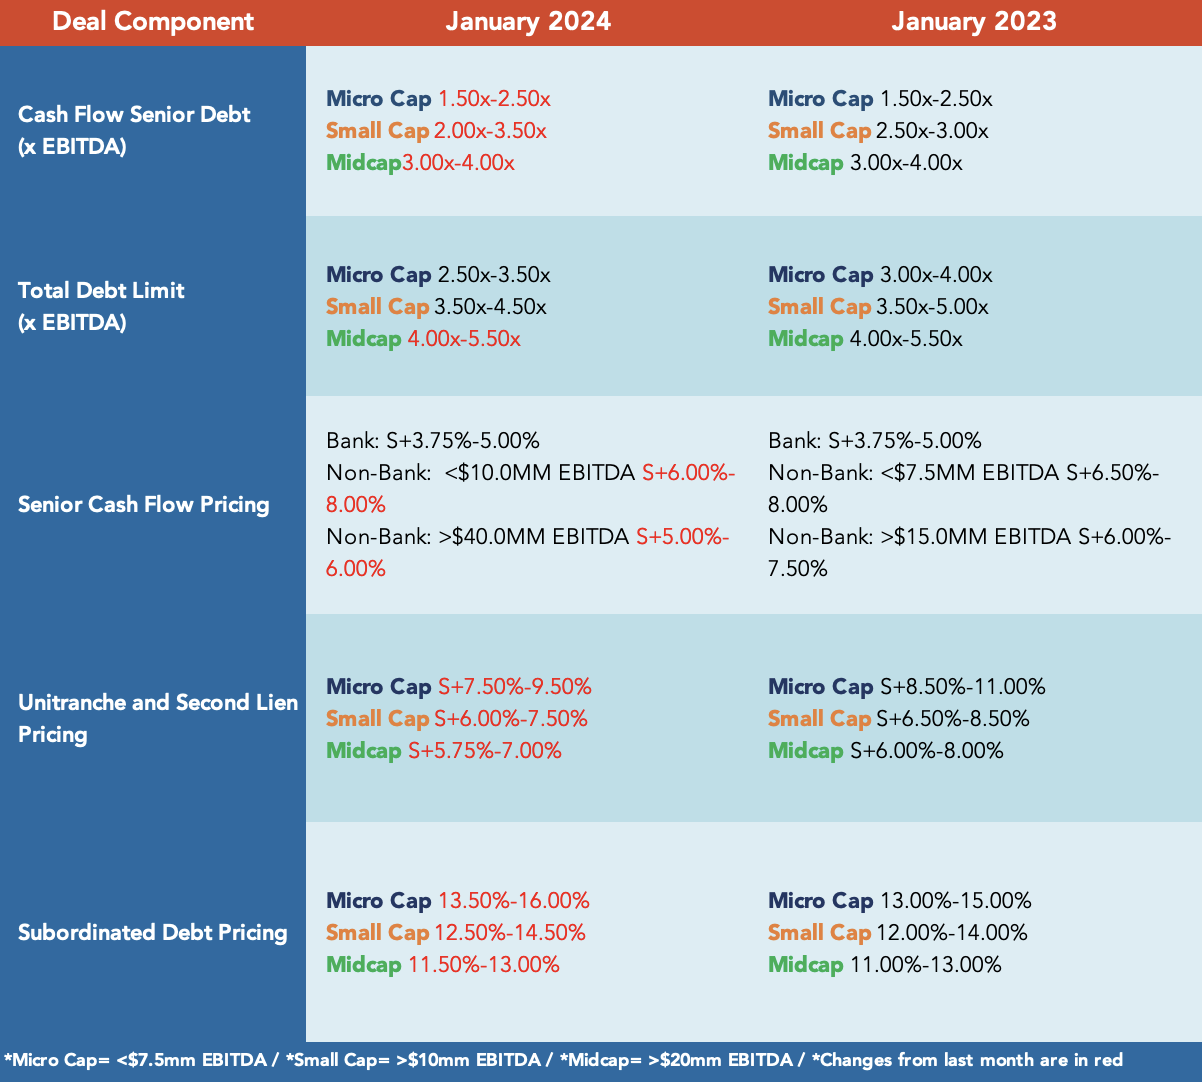
Middle Market Deal Terms at a Glance

SPP-Jan-2024 image

Contact: Stefan Shaffer / SPP Capital Partners

Churchill-2020-logo-white-for-event-invite image
STAY CONNECTED
Twitter  Linkedin  Youtube  

This publication is a service to our clients and friends. It is designed only to give general information on the market developments actually covered. It is not intended to be a comprehensive summary of recent developments or to suggest parameters for any prospective financing opportunity.