|
Your trusted guide to a strong and secure retirement! | |
LBA Quarterly Newsletter - Summer Edition
2026 • Quarter 3 • Issue 19
|
|
|
Robert Dumais
Principal, LBA
|
| Your Retirement Accounts Have A Secret Co-Owner | |
For years, many people faithfully contributed to:
- 401(k)s
- 403(b)s
- Traditional IRAs
- 457 plans
- SEP IRAs
- Annuities
- Various other qualified retirement accounts
The tax deductions felt great at the time. Uncle Sam basically said, “Go ahead… put money away for retirement. We’ll wait.” Well… The waiting period is ending. Eventually, the IRS expects its share through taxable withdrawals and Required Minimum Distributions (RMDs).
It’s kind of like having a business partner who never helped with the workload, never attended meetings, never contributed ideas, but suddenly appears at retirement with a calculator, saying:
“Congratulations on your savings. We’ll take our portion now.”
| | |
One of the sneakiest issues in retirement is accidentally creating “high-income years.”
Many retirees assume:
“I’m retired now, so I’ll obviously be in a lower tax bracket.”
Not always!
Here’s how things can unexpectedly stack up:
- Pension income
- Social Security
- RMDs
- Investment gains
- Part-time work
- Property sales
- Large IRA and qualified account withdrawals
Suddenly, a retiree who thought they’d be in a modest tax bracket discovers they’ve drifted into a higher one. Unfortunately, the IRS doesn’t hand out participation trophies for this achievement.
| | |
Medicare Has Opinions About Your Income Too | | |
Just when you thought taxes were complicated enough, Medicare enters the conversation. Many retirees don’t realize that Medicare premiums can increase based on income. Higher income can trigger IRMAA surcharges (Income-Related Monthly Adjustment Amounts), which can increase the cost of Medicare Part B and Part D significantly.
Translation:
The government may look at your income and politely say, “Wonderful year financially - that’ll cost you extra.” This is why income planning matters. Spreading withdrawals strategically across years may help reduce unnecessary tax exposure and avoid triggering higher Medicare costs.
Retirement income planning isn’t just math:
- It’s timing.
- It’s coordination.
- It’s strategy.
- Occasionally, it’s trying to avoid receiving letters from government agencies that begin with: “Based on your reported income…” Nobody enjoys those letters.
| | |
|
Required Minimum Distributions:
The Government’s Version of “You’ve Waited Long Enough”
| |
At a certain age, the IRS no longer politely suggests withdrawals. They require them.
Required Minimum Distributions (RMDs) are mandatory withdrawals from many qualified retirement accounts. The government essentially says: “You’ve had decades of tax deferral. The buffet is closing. Start taking money out.”
Failing to handle RMDs properly can create costly penalties. That’s why retirement planning shouldn’t happen in isolation. Investments, taxes, healthcare costs, Social Security, and income strategies all interact with one another.
It’s less like balancing a checkbook… and more like conducting an orchestra where everyone is slightly out of tune.
|
A Good Retirement Plan Isn't Just About Growth | |
During your working years, the focus is often, “How much can I accumulate?”
But retirement shifts the conversation toward, “How efficiently can I distribute income?” That’s a completely different challenge.
A successful retirement strategy may involve:
- Managing taxable income
- Coordinating withdrawals
- Monitoring Medicare thresholds
- Understanding tax diversification
- Planning for RMDs
- Preserving long-term income stability
In other words, retirement isn’t simply about crossing the finish line. It’s about making sure the money lasts after you get there.
|
| |
The good news?
You do not have to figure all of this out alone.
| One Important Disclaimer (Before the IRS starts reading this...) | |
While the team at Legacy Benefit Advisors is highly knowledgeable about retirement income strategies and tax-efficient planning concepts, we are not official tax advisors or CPAs. However, we work closely with these topics every day and can help guide clients in the right direction while coordinating with qualified tax professionals when appropriate.
Think of us as experienced retirement tour guides: We may not prepare the tax return itself, but we certainly know where many of the financial potholes are located.
|
| |
Retirement planning isn’t only about growing wealth. It’s about protecting it intelligently. After decades of hard work, saving, investing, and sacrificing, most people would prefer their retirement money go toward:
- Family
- Travel
- Hobbies
- Grandchildren
- Enjoying life
…rather than unintentionally overpaying taxes because nobody helped them build a strategy.
At Legacy Benefit Advisors, we believe retirement is a process, not an event. Sometimes the smartest retirement move isn’t chasing higher returns. Sometimes it’s simply making fewer expensive mistakes.
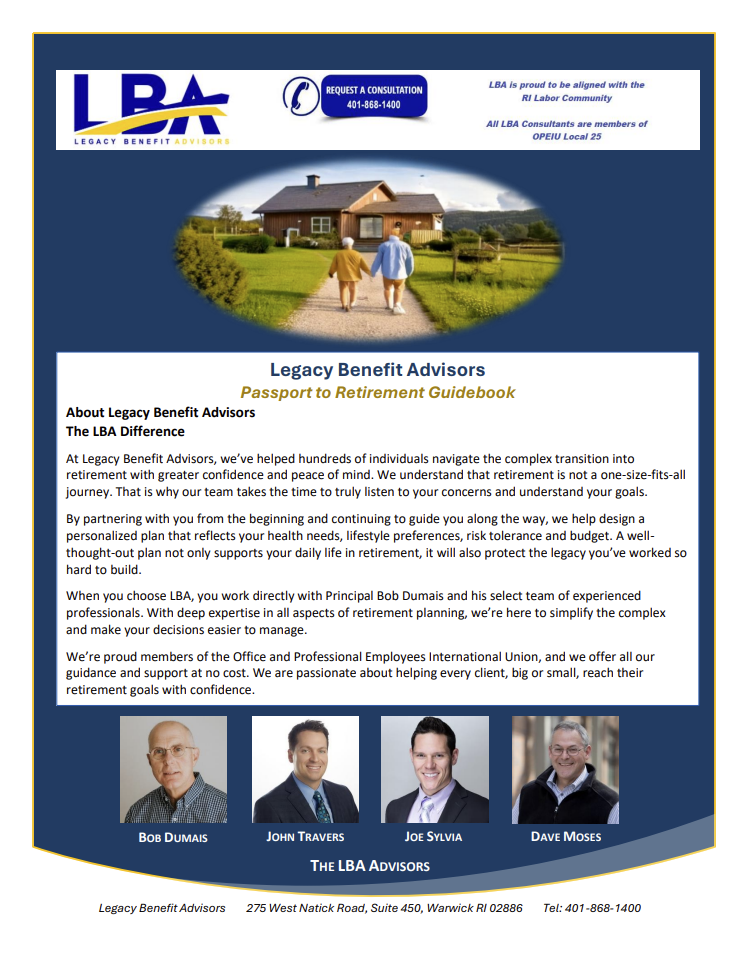
Whether walking or running, athletes always stretch before they compete. Retirement deserves the same kind of preparation. Before you make the leap, get organized and build a strategy designed for success. Start strong with our free Passport to Retirement Guidebook.
| | Passport to Retirement Guidebook | |
Remember: Retirement is a process not an event.
LBA can help with a no-cost consultation!
| | What are YOU stressed about? (We can help.) | | |
☐ Running out of Money
☐ Rising Inflation
☐ Healthcare and Long-Term Care Expenses
☐ Minimizing taxes
☐ Having a Steady Income Stream
☐ Stock Market Volatility
☐ Making Social Security and Pension Decisions
☐ Choosing the Right Medicare Coverage
☐ Managing RMDs, Avoiding Costly Mistakes
☐ Managing 401k, 403b, 457, IRA, Rollovers, etc. Without Penalty
☐ Leaving a Legacy for my Family
| | |
|
One of the more valuable tools we offer is our Passport to Retirement Guidebook. It is a practical, easy-to-follow companion for planning retirement.
It helps you:
• Clarify what retirement looks like for you
• See if you’re financially ready
• Understand healthcare choices
• Organize legal and legacy plans
We encourage you to complete it at your own pace, then schedule a complimentary consultation. Together, we’ll turn it into a personalized retirement plan.
Click Here to download the Passport to Retirement Guidebook PDF
Client Testimonial: "The Passport to Retirement helped us see everything in one place. It made retirement feel real — and manageable."
| | We have covered so many critical topics in our many quarterly newsletters over the past few years. We've created a simple roadmap to all of these great articles for your benefit. | | The Team at Legacy Benefit Advisors has the answers! | | |
John Travers
Benefit Advisor
| | |
Dave Moses
Benefit Advisor
| | |
Joe Sylvia
Benefit Advisor
| | |
LBA consultants aremembers of
OPEIU Local 25
| |  |
Robert Dumais, Principal
275 West Natick Road
Suite 450
Warwick, RI 02886
401-868-1400 (O)
774-991-3369 (M)
401-737-0330 (F)
| | P.S. Add me to your contacts so we can continue to keep you in the know and don't hesitate to hit "reply" to contact us. | | | | |