Access our research on the Bloomberg Terminal with ERH GXY <GO>
|
|
gm -
episode 6 of galaxy brains is live and includes great discussions on markets, coinbase's new nft platform, and dydx's plans for a major upgrade. listen on apple, spotify, amazon, or wherever you get your pods.
also in today's newsletter, we discuss the growing 'stablecoin wars' as more ecosystems and blockchains seek to mimic the success of luna's ust.
have a great weekend,
alex
|
|
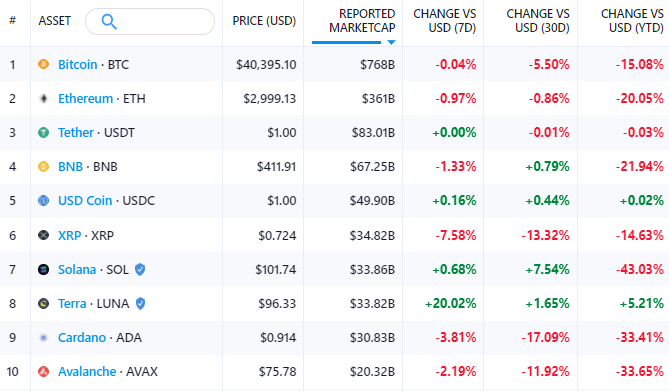
The total implied network value (market cap) of the digital assets market stands at $1.85tn, down 0.5% from last week (when it stood at $1.86tn). Bitcoin’s network value is 6% of gold’s market cap. Over the last 7 days, BTC is flat, ETH is down about 1%, and LUNA is up 20%. Bitcoin dominance is 41.59%, up slightly from last week when it stood at 41.18%. |
|
Data current as of 8:45 am ET on April 22, 2022. Prices and Data via Messari.
|
|
🖼️ Coinbase Debuts NFT Market Place
|
|
After months of anticipation, Coinbase released a beta version of its NFT marketplace on Wednesday. While only a select group of users can transact NFTs on the platform today, any visitor can still browse individual NFTs, NFT collections, and user profiles. The mere release of this platform, even in its limited functional state, is a milestone in and of itself given the 4+million people who signed up for its waitlist (compared to 1.5 million all-time users of OpenSea according to Dune Analytics). Coinbase built this OpenSea challenger with an eye towards integrating its existing retail-oriented product suite as much as possible. Not surprisingly, Coinbase Wallet features as the de-facto gateway to this web3 application (though Coinbase NFT is also compatible with other wallets like MetaMask). The platform will only support Ethereum-based NFTs initially, but they have plans of eventually being cross-chain. Fees on the platform are 0% for the time being, and they’re expected to rise to the low single digits seen in other marketplaces (such as OpenSea’s 2.5% and LooksRare’s 2%). The smart contract calls for exchanging NFTs on the Coinbase NFT platform are handled by 0x (whose token ZRX has seen a ~25% rise this past week on the news of their partnership).
Coinbase is looking to stand out from other NFT marketplaces by emphasizing its social features. On the Coinbase NFT platform, users can like, follow, and comment on NFTs and on other user profiles. This experience positions Coinbase NFT both as an NFT-oriented version of social media and as an NFT marketplace. Coinbase hopes that this added level of user engagement and interactivity will attract and retain users to its platform. Time will tell if the synergies between Coinbase NFT and Coinbase’s existing retail-heavy products will be insurmountable for current NFT juggernauts like OpenSea to compete against.
|
|
OUR TAKE: Coinbase is in a very strong position to capture market share from the likes of OpenSea and other competitors in the red-hot NFT marketplace landscape. For starters, Coinbase can offer its users a very simplified user journey starting with onboarding fiat all the way to acquiring and NFT. Coinbase can also reduce the number of hoops its users need to jump through to obtain liquidity for their NFTs. Coinbase NFT's approach also simplifies tax compliance for users who may otherwise have to manually reconcile taxable events for their NFT trades should they occur across multiple platforms.
More importantly, Coinbase will enjoy a strong relative position due to its data. There are two angles to this. First, Coinbase NFT will employ a discover page (much like what is seen on other platforms). However, because Coinbase has an existing userbase of 89 million individuals, it can leverage this treasure trove of data to recommend more relevant NFTs to its users in their personalized feed. This killer feature of accurate recommender systems anchored by massive datasets for ML algorithms to train on has led to the rapid rise of social media apps like TikTok. Because Coinbase has the best data of all current NFT marketplaces, they have the technical ability to recommend the most relevant content to their users compared to other players in this space.
Additionally, Coinbase NFT’s social features enable brand-new sources of user-generated data to help the platform cultivate a custom experience for each of its users. This is especially crucial in a world increasingly cluttered by new NFT projects that emerge on a daily basis. Users will appreciate the ability for a platform to filter the signal from the noise. With that being said, integrating social features is a double-edged sword because content moderation is extremely tough and it is not a core competency of Coinbase’s existing business. To the extent that hate speech, vulgar language, and unpleasant user-user exchanges happen on its platform, Coinbase may struggle with filtering out this bad content and may do more harm than good from a UI/UX point-of-view. Time will tell if Coinbase can pull this off, but to the extent that they do, they will be well-positioned to slice-off a chunk of NFT trading market share in this highly competitive space.
|
|
💸 Platform Stablecoin Wars Heat Up |
|
TRON to launch its own platform stablecoin USDD. TRON founder Justin Sun announced plans to launch a decentralized algorithmic native stablecoin on Tron called USDD (Decentralized USD). USDD will employ a market module similar to Terra's UST to maintain its peg to the dollar: USDD will be minted by burning a portion of Tron's native platform token $TRX. As demand for USDD increases, burning more TRX will have a diluting effect so that the price of USDD doesn't rise above $1. Similarly, when demand for USDD decreases, USDD can be redeemed for TRX at a 1:1 dollar ratio, which reduces USDD supply puts upward pressure on price whenever USDD is below $1.
TRON DAO is being created to provide custody of reserves backing USDD of up to $10bn in liquid assets (assets not yet specified) to be raised from "initiators of the blockchain industry" for use as an early-stage reserve and to enforce convertibility between USDD-TRX. The TRON DAO Reserve will also set its "basic risk-free interest rate" to 30% per annum. USDD is scheduled to launch on TRON May 5th and will also be available on Ethereum and BNB Chain through the BTTC cross-chain protocol.
Following the announcement, TRX traded up 17%. Terra's Do Kwon responded to the announcement positively, saying "Decentralized economies deserve decentralized money - every blockchain will run on [decentralized] stables soon".
|
|
OUR TAKE: The platform stablecoin wars are starting to heat up. With a design very similar to Terra's UST--including the algorithmic market module, the establishment of a reserve, and a very generous interest rate--TRON becomes the latest blockchain with plans to launch its own native stablecoin. NEAR Protocol is also expected to launch its own native stablecoin USN, though has not yet made any formal announcement to do so.
TRON is currently has the largest balance of Tether across blockchains with a balance of nearly $42bn in TRC20 USDT - above the $40bn of USDT held on Ethereum. Justin Sun is now looking to diversify TRON's reliance on a centralized stablecoin through the launch of USDD, perhaps realizing the importance of having decentralized money especially with Tether's proven ability to freeze USDT held in specific wallet addresses. Or potentially a greater contributing factor, Sun may be looking to mimic the successful model of Terra's UST in driving user adoption. The fixed 30% rate offered on USDD comes in higher than the 19.5% offered on UST through Anchor and Sun's wallet was found to have been locking up $CVX in Convex, suggesting he may be looking to influence rewards on Curve towards USDD (similar to Terra's 4pool strategy). It's an expensive marketing strategy for a blockchain to drive user adoption, which contrasts with the typical playbook employed by L1s last year of launching large liquidity mining incentive programs.
More competition between platforms for stablecoin dominance is great for users as it implies higher rewards on stables - any new chains will have to come in at more generous rates relative to the 19.5% Anchor Rate to incentivize new deposits and to make up for the perceived risk premium on top of UST. Also, if TRON DAO or other chains employ a similar reserve strategy to the Luna Foundational Guard, it would suggest increased buying of assets like BTC. There's a strong moral case for decentralized money over the long term, but still we hope to see more innovation behind any new platform algorithmic stablecoins rather than just copy-and-pasting onto every alternative layer 1. These stablecoins’ designs have yet to be fully battle-tested and the risks of de-pegging need to be better understood.
|
|
🔧 dYdX Details Decentralization Roadmap |
|
dYdX announces a roadmap to full decentralization, titled V4. Founded in 2017 by former Coinbase engineer Antonio Juliano, dYdX garnered mainstream attention in late 2021 by briefly surpassing Coinbase in total daily trading volume. Its hybrid centralized/decentralized system attracted many traders and investors amongst China’s crypto crackdown. The protocol fills a compelling niche within the crypto trading realm, offering spot, margin, and perpetual products for many cryptocurrencies. Today the protocol exists on the Ethereum chain partitioned by Layer 1 and Layer 2 product offerings. The Layer 1 version offers an exchange for crypto margin and spot trading, powered by a centralized order book and matching engine. dYdX trading Inc., headquartered in San Francisco, CA, manages servers that facilitate the order book and engine and collects trading fees. On its layer 2, dYdX offers perpetual contract trading for a wide assortment of cryptocurrencies. The protocol is built with smart contracts and STARK rollups with the intention of full decentralization.
Version 4 is meant to upheave the current protocol and usher in a new cohesive decentralized dYdX ecosystem, one that is community-operated and governed. The primary focus is decentralizing the order book and matching engine, which is now processing an estimated 500 orders per second. In addition, this updated system will require high-speed finality and accurate trade sequencing. The dYdX team outlines these upcoming challenges into three pillars of focus, throughput, finality, and fairness. The update will be entirely open source and meticulously auditable. In partnership with Paradigm, dYdX plans to roll out version 4 by the end of 2022.
|
|
OUR TAKE: dYdX has been a pillar of intrigue within the decentralized finance (defi) ecosystem. Still, up to this point, a centralized corporation has facilitated one of its core service offerings, presenting a conflict of values. If successful, the planned transition can stimulate an intriguing realignment of values within defi. Almost two years since “Defi summer,” the pace of ingenuity in novel defi financial instruments has reduced in velocity. The next chapter of the ecosystem should focus on the redirection of said ingenuity to fortify and improve on the core principle: decentralization. dYdX is taking steps to usher in this new chapter by transitioning its trading operations; for many other protocols, the challenge lies in critically reviewing their governance methodologies.
At the height of recent notoriety, in September 2021, Antonio Juliano reported that they were bringing in revenue of $1.5m + per week. In dYdX V4, “no central party (including dYdX Trading Inc.) will have the ability to receive trading fees.” The portion of revenue that trading fees are responsible for will most likely be redirected to protocol stakeholders or liquidity providers, along with the responsibility of supporting order book functionality. What role with the dYdX token play in this V4 ecosystem? Currently, token holders can utilize voting rights to set layer two risk parameters, add a new token listing to layer 2, and vote on market makers for added liquidity in staking pools. But following the upgrade, holders of dYdX tokens could be eligible to receive mining, trading, and liquidity provider rewards (perhaps even retroactively). Another aspect of V4 that sparks curiosity is its existence on Ethereum (ETH). As is, it is unlikely that layer 1 ETH can support the throughput that dYdX trading inc. now facilitates centrally with servers. The late 2022 release date may align with the projected ETH merge in Fall 2022, or dYdX could launch fully on an alt L1 or fully on an ETH-based L2.
|
|
-
Optimism will move towards "community ownership and governance"
-
The NBA launched a dynamic NFT collection representing players in the playoffs
-
Connext, an interoperability protocol, to launch token and transition to a DAO
-
LimeWire raised $10m in token sale to build music NFT platform
-
Binance.US leaves Blockchain Association to form in-house lobbying group
-
Dune Analytics rebrands to just Dune
-
Andre Cronje sets eyes on regulated DeFi in new blog post
-
Compound governance proposal to end COMP rewards program was rejected
|
|
Access our research on the Bloomberg Terminal with ERH GXY <GO>
|
|
|
|
Galaxy Digital Research Podcast |
In this week's episode, we discussed volatility in markets, Bitcoin transaction fees at all-time lows, and Ethereum's forthcoming merge upgrade. Give it a listen!
|
|
|
|
What to Expect From Ethereum's Merge Upgrade |
In this report, Research Associate Christine Kim breaks down what investors can expect from Ethereum's Merge upgrade, the network's most complex and radical code change to date.
|
|
|
|
Why Bitcoin Transaction Fees Are So Low |
Bitcoin transaction fees are at all-time lows. The last 9 months are the only time in Bitcoin history that a price bull run was not accompanied by a spike in transaction fees. Alex explains how that is possible and why it matters.
|
|
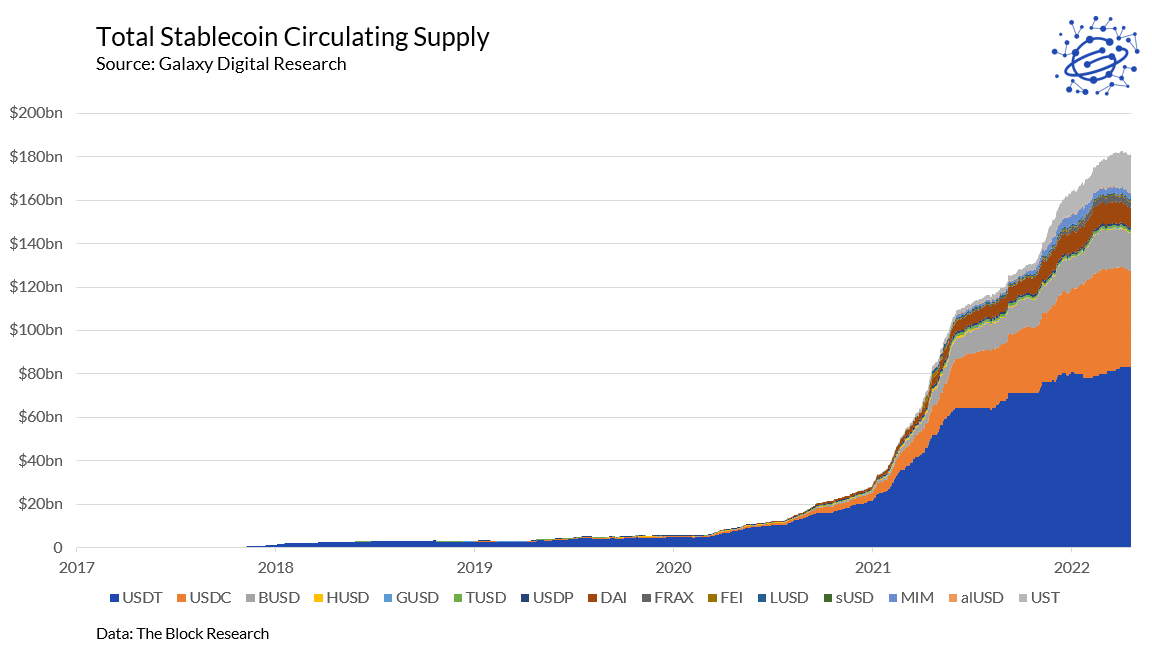
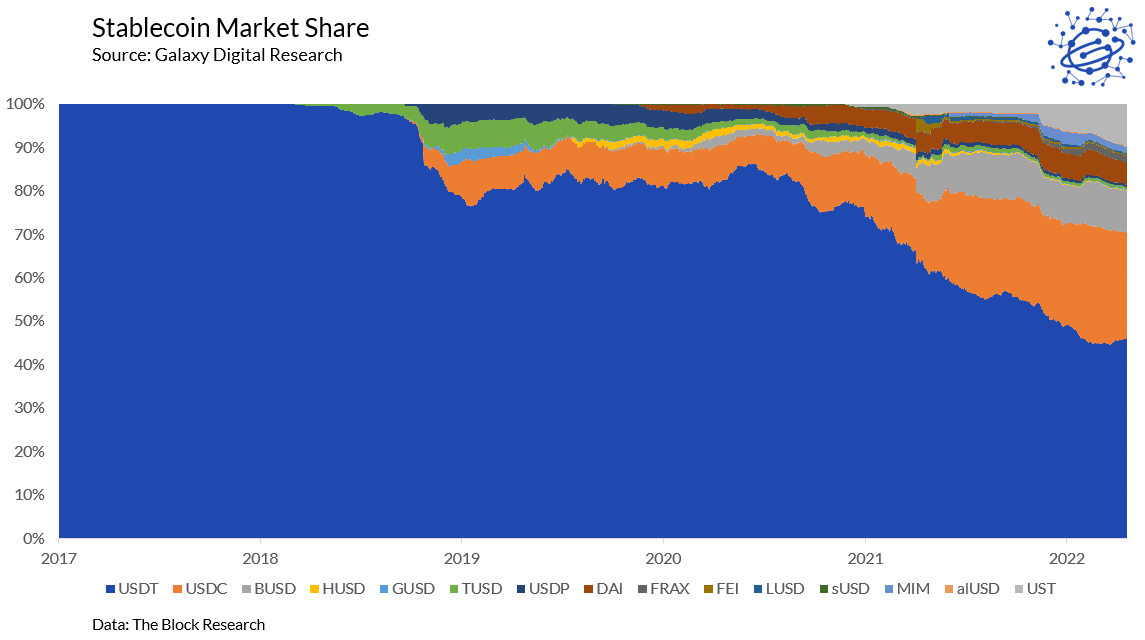
Total stablecoin supply hovers around $180bn. The rise of Luna's UST can be seen over the last several months on the top right of the chart below. |
|
Tether's share of all circulating dollar-denominated stablecoins is at its lowest ever. |
|
Thanks for reading this week. Have a great weekend.
|
|
Alex Thorn
Head of Firmwide Research, Galaxy Digital
|
|
|
Legal Disclosure:
This document provides links to other websites that we think might be of interest to you. Please note that when you click on one of these links, you may be moving to a provider's website that is not associated with Galaxy Digital. These linked sites and their providers are not controlled by us, and we are not responsible for the contents or the proper operation of any linked site. The inclusion of any link does not imply our endorsement or our adoption of the statements therein. We encourage you to read the terms of use and privacy statements of these linked sites as their policies may differ from ours. This document, and the information contained herein, has been provided to you by Galaxy Digital Holdings LP and its affiliates (“Galaxy Digital”) solely for informational purposes. This document may not be reproduced or redistributed in whole or in part, in any format, without the express written approval of Galaxy Digital. Neither the information, nor any opinion contained in this document, constitutes an offer to buy or sell, or a solicitation of an offer to buy or sell, any advisory services, securities, futures, options or other financial instruments or to participate in any advisory services or trading strategy. Nothing contained in this document constitutes investment, legal or tax advice. You should make your own investigations and evaluations of the information herein. Any decisions based on information contained in this document are the sole responsibility of the reader. Certain statements in this document reflect Galaxy Digital’s views, estimates, opinions or predictions (which may be based on proprietary models and assumptions, including, in particular, Galaxy Digital’s views on the current and future market for certain digital assets), and there is no guarantee that these views, estimates, opinions or predictions are currently accurate or that they will be ultimately realized. To the extent these assumptions or models are not correct or circumstances change, the actual performance may vary substantially from, and be less than, the estimates included herein. None of Galaxy Digital nor any of its affiliates, shareholders, partners, members, directors, officers, management, employees or representatives makes any representation or warranty, express or implied, as to the accuracy or completeness of any of the information or any other information (whether communicated in written or oral form) transmitted or made available to you. Each of the aforementioned parties expressly disclaims any and all liability relating to or resulting from the use of this information. Certain information contained herein (including financial information) has been obtained from published and non-published sources. Such information has not been independently verified by Galaxy Digital and, Galaxy Digital, does not assume responsibility for the accuracy of such information. Affiliates of Galaxy Digital own investments in some of the digital assets and protocols discussed in this document. Except where otherwise indicated, the information in this document is based on matters as they exist as of the date of preparation and not as of any future date, and will not be updated or otherwise revised to reflect information that subsequently becomes available, or circumstances existing or changes occurring after the date hereof. The foregoing does not constitute a "research report" as defined by FINRA Rule 2241 or a "debt research report" as defined by FINRA Rule 2242 and was not prepared by Galaxy Digital Partners LLC. For all inquiries, please email contact@galaxydigital.io. ©Copyright Galaxy Digital Holdings LP 2022. All rights reserved.
|
|
|
|
|
|
|