|
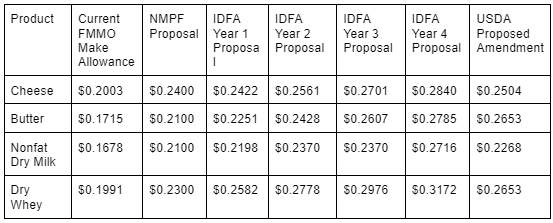
As you can see, USDA has proposed new make allowances that are greater than all four of National MIlk’s proposed make allowances and has settled somewhere between the first and final figures in IDFA’s four-year stairstep proposal.
According to USDA’s justification, the agency was able to easily determine that the existing make allowances were inadequate and must be replaced. USDA in deciding to reject NMPF’s proposal stated that the cooperatives’ arguments–that adopting significantly increased make allowances would be too detrimental to dairy farmer income–was not sufficient as USDA’s mandate under the FMMO system is to determine make allowances based on economic data related to the true costs of manufacturing dairy products. USDA also rejected the IDFA proposed make allowances in part because the agency did not agree with the modeling assumptions used in its supporting evidence. According to USDA the recommended make allowances are drawn from a combination of survey results provided as evidence during the hearing.
Class I Mover
Secondly, there was much debate during the FMMO hearing over the Base Class I Skim Milk Price which we refer to most commonly as the Class I Mover. There were a total of six proposals presented on this subject during the hearing. NMPF proposed returning to the higher-of mover, IDFA and the Milk Innovation Group (MIG) proposed using a modified average-of that would recalculate the adjuster (currently set at $0.74/cwt) after a period of roughly two years, Edge Cooperative proposed using the announced Class III Skim price with an adjuster that would reflect the difference in the higher-of and average-of mover, Edge and AFBF also proposed ending advanced pricing for Class I and Class II products.
USDA’s own calculations on the performance of the average-of mover versus the higher-of points to a loss of $1.066 billion for dairy farmers since the average-of took effect in 2019. USDA found that the average-of mover did “mute” blend prices across the country, especially in the Southeast. Furthermore, USDA states that the hearing evidence points to the fact that the change in Class I mover also contributed to volatility in pooling and depooling of milk in several Federal Orders dominated by Class III and Class IV manufacturing. Therefore, USDA recommends that the Base Class I Skim Milk Price return to the higher-of.
While USDA sided with dairy farmer groups in returning to the higher-of, they did agree with processor groups that extended shelf life products (ESL) do have significantly different marketing challenges than traditional class I milk. Therefore, USDA is recommending a modified average-of mover for Class I ESL products. The Class I ESL adjustment would be announced at the same time as the Class I mover and would be equal to the difference between the higher-of and average-of Class III and Class IV skim milk plus a rolling monthly adjuster that would be calculated as the average of the differences between the higher of and the average of for the prior 13-36 months (meaning there would be a 12 month lag). USDA stated that it is seeking to create less volatility for the base Class I price for ESL products since those products are competing increasingly against other shelf-stable products (juice, soda, sports drinks, etc.).
Class I Differentials
The third major recommendation from USDA would overhaul the Class I zone differentials map. There was strong disagreement between farmers, cooperatives, and processors over how best to update the differentials map given the changing dairy landscape since the map was developed in 2000. USDA determined that the Milk Innovation Group’s proposal to zero out the base Class I differential to $0.00 was unfounded, and the agency chose to keep the base rate at $1.60/cwt. Furthermore, USDA found that the “Grade A maintenance costs” that were baked into the original base differential during order reform 25 years ago is still appropriate given the fact that the regulatory system governing dairy farmers requires Grade A standards on the farm. USDA also stated that balancing costs and additional monies to incentivize Class I supply are still necessary elements of the Class I base differential, effectively nullifying MIG’s proposal.
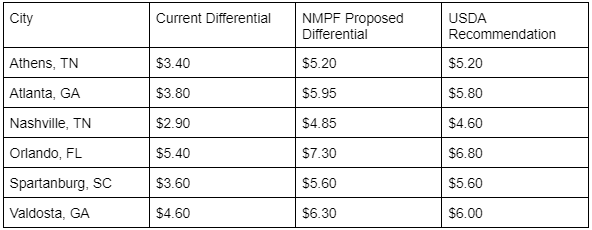
This left USDA with the issue of determining how or if the Class I differentials should increase regionally. While USDA did not agree with NMPF’s proposal to raise the base differential $0.60/cwt, the agency did agree that there is ample evidence to support raising Class I differentials across the country. USDA went about setting the new differentials by utilizing a model to reflect the costs of servicing Class I markets across the country and then adjusting the “bands” or “zones” to ensure competitive balance among handlers and processors. In the Southeast, the new differentials would start at $3.70/cwt in the Appalachian Order (FO 5) and increase in increments of $0.20-0.30/cwt as they move South and East. In the Southeastern Order (FO 7), the bands start at $3.20/cwt in Missouri and max out at $6.00/cwt in Southeast Georgia. The Florida Order’s maximum differential was raised to $7.40 at the southern end of the peninsula.
Proposed Class I Differentials for Southeastern Processing Locations
|