|
Happy October, IMA Members!
We are coming off our fall conference, which hopefully left many of you who were able to attend with a renewed sense of energy for our ever-changing industry. The conference planning committee brought back the golf outing to kick us off, and we had the most beautiful fall weather Iowa could have offered us. I look forward to growing this event next year with more hole sponsors, tents and games at the holes, as well as more golfers.
Our time was filled with motivating speakers, roundtable networking sessions and a very insightful appraisal panel. One of our favorite economists, Dr. Chris Kuehl, provided insight into our current economic landscape. Dan Meers wrapped up the conference with a very emotional reminder to us all to embrace the present and be ever grateful for the good in our lives.
Save the date for our spring conference in Coralville on March 29-30 as the conference planning committee works on some exciting things to get us going for the new year. We have space open on both our conference planning committee and our IMA education committee. Please contact us if you’re interested in joining one of these committees. We love to have a wide variety of input from our members to make our events and education offerings as valuable to you as possible. Watch your emails for our next education offering, coming out soon.
| | |
Casey Purcell
Kind Lending
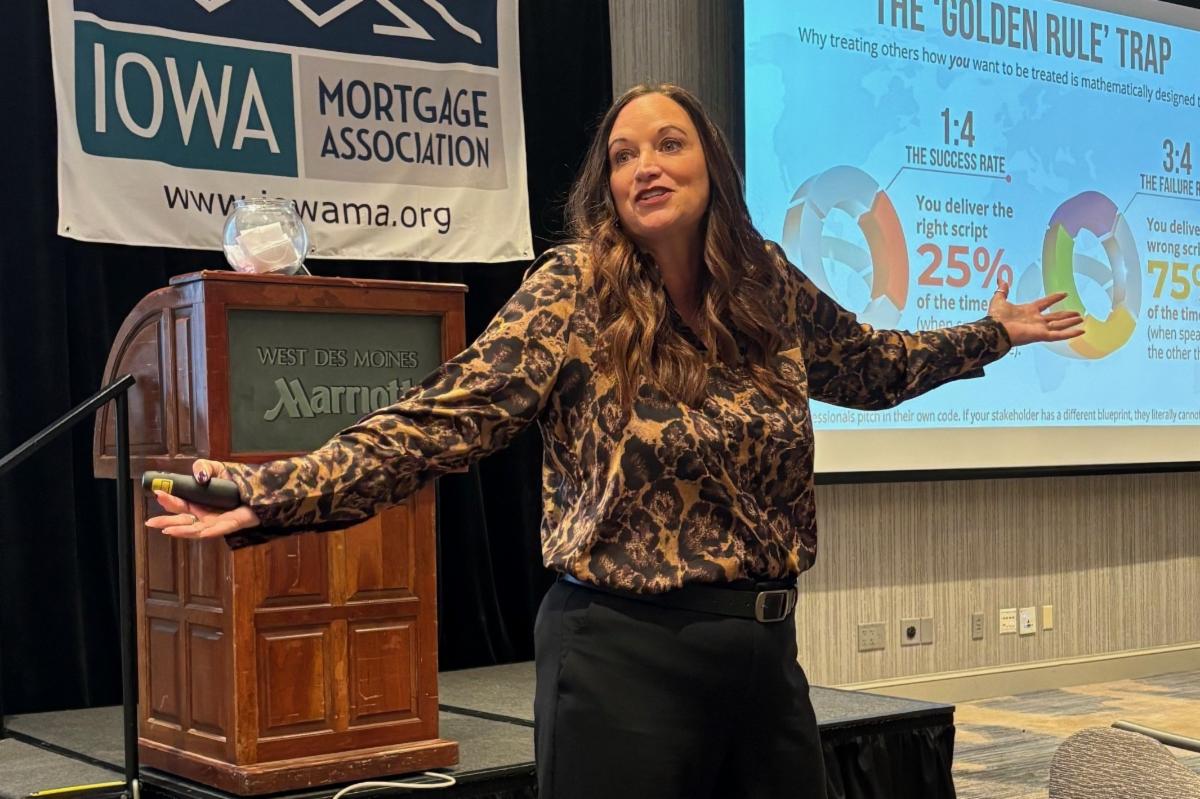
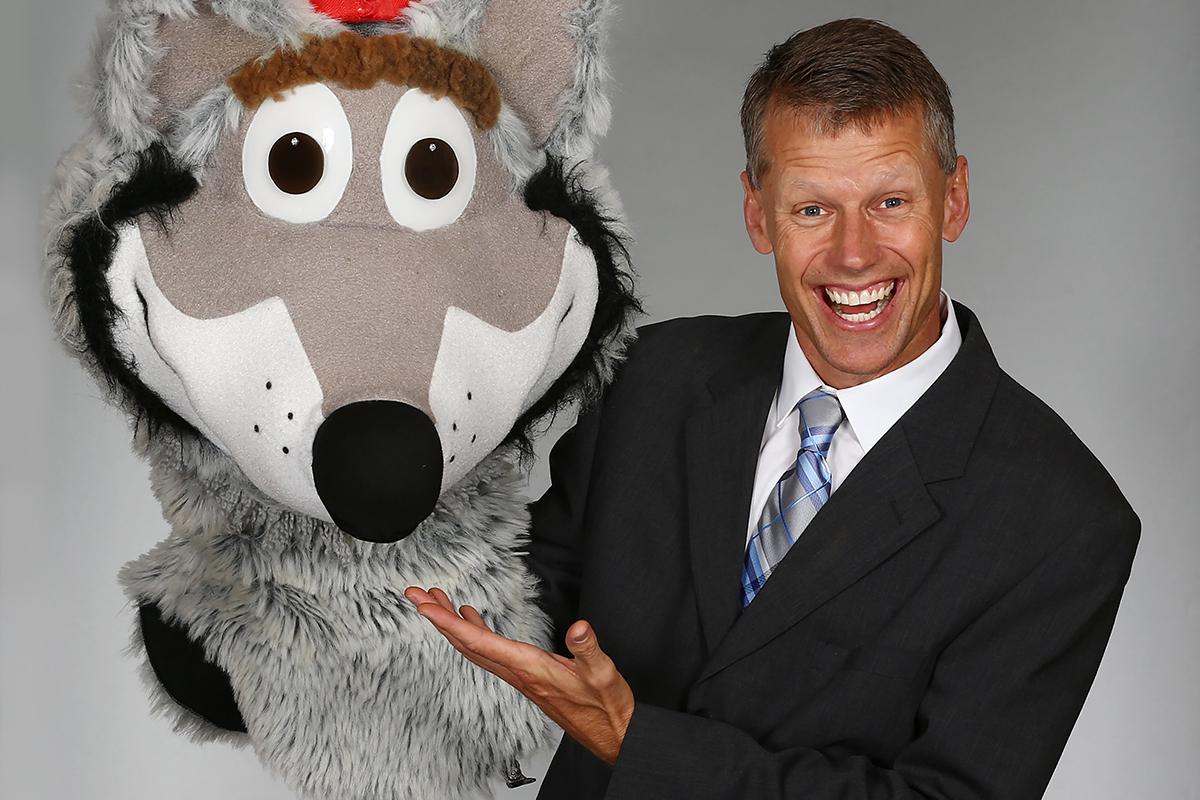
| | | | Thank You for Attending the IMA Fall Conference | Thank you to everyone who attended the IMA Fall Conference this year. From an opening golf outing to a powerful closing session by Dan Meers, nearly 100 mortgage professionals gathered to learn and network. Through informative sessions on understanding how people communicate to build trust and relationships, an economic update, an appraisal panel and mortgage industry trends, attendees gained valuable insights and new skills to excel as mortgage professionals. | Pictured above is Lynsey Mulder, Mulder Consulting, LLC, who opened the conference with a session on how to “crack the code” to understand others’ communication styles. | Pictured above is Dan Meers, former Kansas City Chiefs mascot, who closed the conference with an inspirational message about living a meaningful and memorable life. |
IMA Elects New Leadership | | |
The IMA recently elected officers and directors to serve on its 2026-27 board of directors. These leaders assumed their roles during the annual IMA Fall Conference.
Officers of the IMA Executive Committee include:
- Casey Purcell, president, Kind Lending
- Derek Carter, vice president, Community 1st Credit Union
- Nick Mundorf, president-elect, Flat Branch Home Loans
- Dave Lewis, secretary-treasurer, Halo Mortgage
- Terry Gearhart, past president
Officers were nominated and approved by IMA member organizations from across the state. The IMA Executive Committee leads the board of directors, which is responsible for setting policy and overseeing the general operation of the IMA.
Also serving on the 2026-27 IMA board of directors are:
- Jay Borbeck, CBMS
- Charlie Chedester, Midwest Family Lending Corp.
- Krystal Frederick, Dupaco Credit Union
- Brianna Gaunt, Community 1st Credit Union
- Missy Griffin, GreenState Credit Union
- Jason Froelich, Home Services Lending
- Jason Hutchison, American Bank & Trust Co.
- Amanda Krenz, Community 1st Credit Union
- Matt Klein, Central Bank
- Dave Lewis, Halo Capital
- Megan Severson, Essent Guaranty
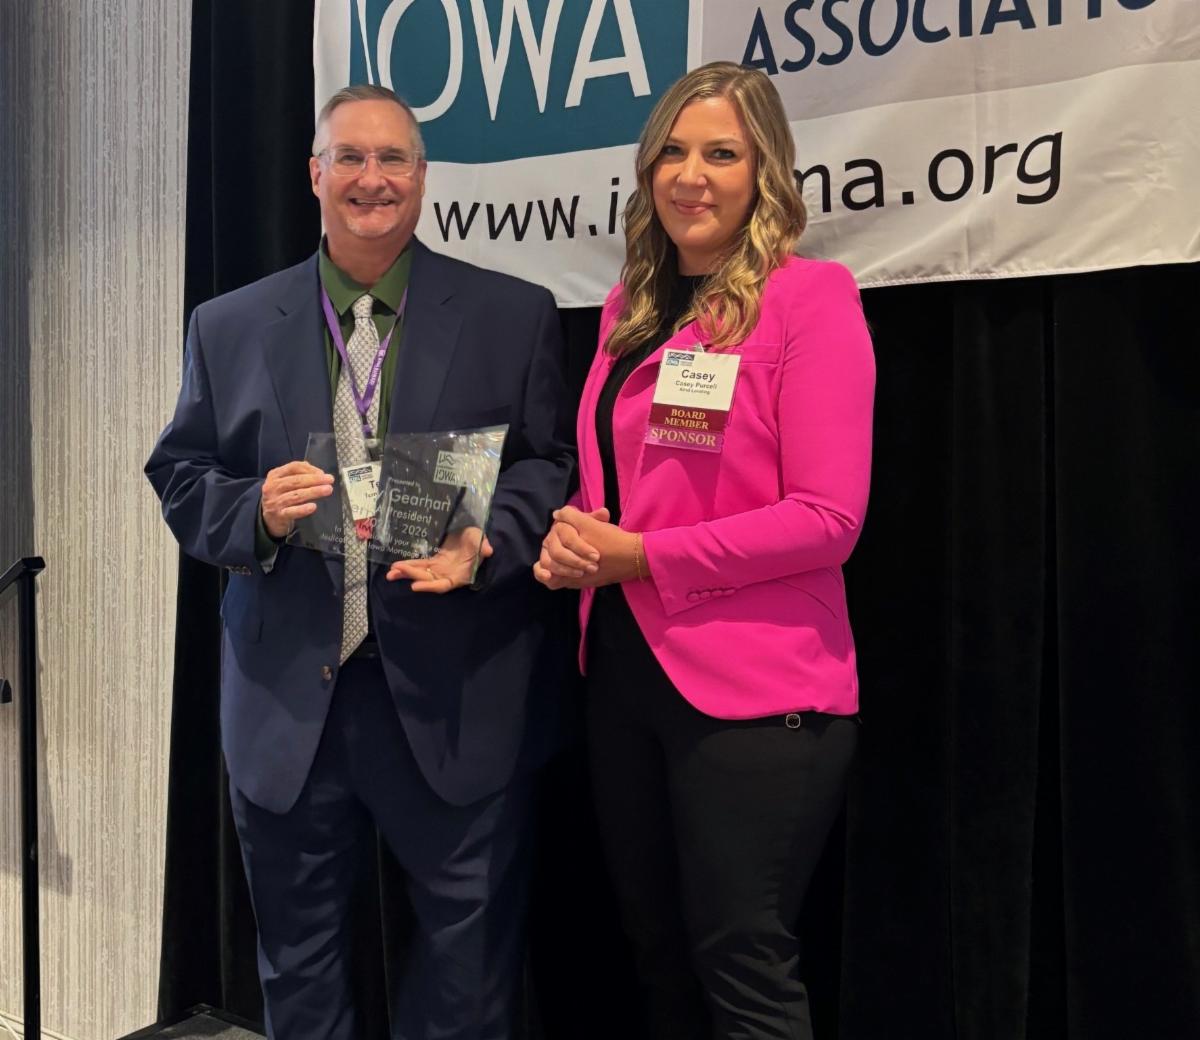
Pictured above is incoming IMA President Casey Purcell presenting a plaque of appreciation to outgoing IMA President Terry Gearhart.
| | CFPB Updates the Special Information Booklet | | |
The Consumer Financial Protection Bureau (CFPB) released an updated version of Your Home Loan Toolkit, which must be provided to certain mortgage loan applicants to help explain real estate settlement services, mortgage costs and the homebuying process. The guide, also known as the Special Information Booklet, is required under Reg. X, 12 CFR 1024.6, and Reg. Z, 12 CFR 1026.19(g).
The July 2026 edition substantially modernizes the booklet’s content and presentation but does not appear to establish new regulatory obligations or change existing delivery requirements. The CFPB indicates that lenders may begin using the revised toolkit immediately.
The Real Estate Settlement Procedures Act (RESPA) requires the CFPB to prepare the booklet at least once every five years. Reg. X also provides that the CFPB may revise the booklet periodically and publish notice of a revision in the Federal Register. Although the CFPB has not published a Federal Register notice or established a deadline for using the revised booklet, lenders may begin using it immediately. Each lender should determine the timing of its transition based on its operational and compliance risk considerations, including coordination with document vendors. Lenders using printed copies may exhaust their existing supply before transitioning to the revised edition.
Bankers can access the updated booklet on CFPB’s website here.
|
Temporary Exception: UAD 3.6 | Fannie Mae and Freddie Mac announced an alternative for sellers unable to meet the Nov. 2 deadline for the Uniform Appraisal Dataset (UAD) 3.6. Sellers must request an exception to continue submitting legacy appraisal reports from Nov. 2 through May 19, 2027. However, the government-sponsored enterprises encourage sellers to complete implementation before March 1, 2027, when legacy appraisals will no longer qualify for certain appraisal-related representations and warranties relief. After May 19, 2027, all new appraisal submissions must use UAD 3.6. Read the full policy exception. |
Fannie and Freddie Expand VantageScore Access | Fannie Mae and Freddie Mac announced expanded availability of VantageScore 4.0 on Sept. 9 allowing all lenders to use the credit score when assessing creditworthiness for single-family mortgages. The expansion follows a pilot program that offered the score to a limited group of lenders while retaining classic FICO as an option. According to Fannie Mae and Freddie Mac, the broader rollout gives lenders another scoring option and supports a more modern, competitive credit scoring framework. For more details, read the Freddie Mac and Fannie Mae resources. |
FHA Sets Date for Alternative Credit Scores | The Federal Housing Administration (FHA) published Mortgagee Letter 2026-11 on Oct. 8 to formalize the addition of VantageScore 4.0 and FICO Score 10T as acceptable credit scoring models for Title II mortgage programs, beginning with FHA case numbers assigned on or after Jan. 1, 2027. The mortgagee letter also provides guidance on how lenders must determine the minimum decision credit score when more than one credit scoring model is submitted. Read the full mortgagee letter. | | | | |