|
The Impact of Heifer Slaughter on Herd Expansion & Beef Supply
It is no secret that record-high beef prices over the last year are a result of tight cattle supplies and strong consumer demand. The average monthly retail price for all fresh beef products in July was $9.63/lb. This is down from the high of $10/lb. in April but is still 5% higher than the same month last year and 31% higher than the 5-year historical average for August.
Demand shifts among beef products are normal for this time of year as we transition from the grilling months of summer to the pot roast days of fall. As we get closer to the holiday season, we can expect to see more demand shifts and seasonal price changes among beef products. Additionally, fuel prices continue to require a larger portion of household incomes that could otherwise be spent on grocery items such as beef. However, the overall story is that consumers still want to buy beef amidst tightening cattle supplies further supporting beef prices.
Beef production so far in 2026 (as of September 1) has declined by 5%, or 829.4 million pounds, compared to the same period in 2025. While average dressed weights for both steers and heifers have increased by roughly 30 pounds since last year, the increase has not been enough to offset the decrease in the number of cattle being processed. At the time of writing this, year-to-date federally inspected steer and heifer slaughter are down by 5.6% and 11.2%, respectively.
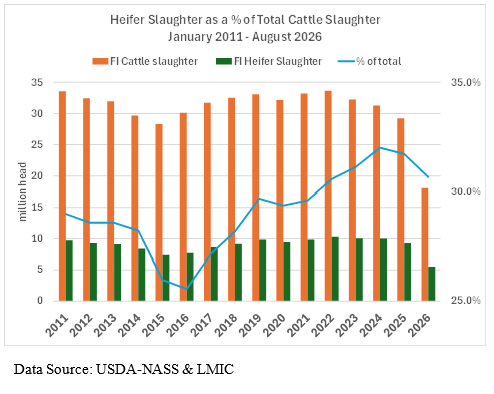
The decline in heifer slaughter does imply more heifers are being retained, but the percentage of heifers being slaughtered so far in 2026 is 30.7%. When we started holding back heifers from 2012-2016 for the last expansion period, this percentage ranged from 28.6% to 25.6% before heifer slaughter began increasing again in 2017. Fundamentally speaking, as more heifers are retained, beef production can be expected to decrease in the short-term until more calves enter the market, resulting in an increase in beef production in the long-term.
|