|
Inflation Outpaces Home Prices
Greetings!
For the past few years, buyers have been squeezed from several directions at once: home prices climbed sharply, mortgage rates moved higher, and inflation pushed up the cost of almost everything else. The latest reports suggest some of those pressures may finally be starting to ease.
The Federal Reserve’s preferred inflation measure, the Personal Consumption Expenditures price index (PCE), rose 0.3% in August and 3.4% from a year earlier. The Core PCE, which strips out the more volatile food and energy categories, increased 0.2% for the month and 3.0% year over year. Those figures came in a little better than expected, giving the Fed more reason to be patient before raising rates again.
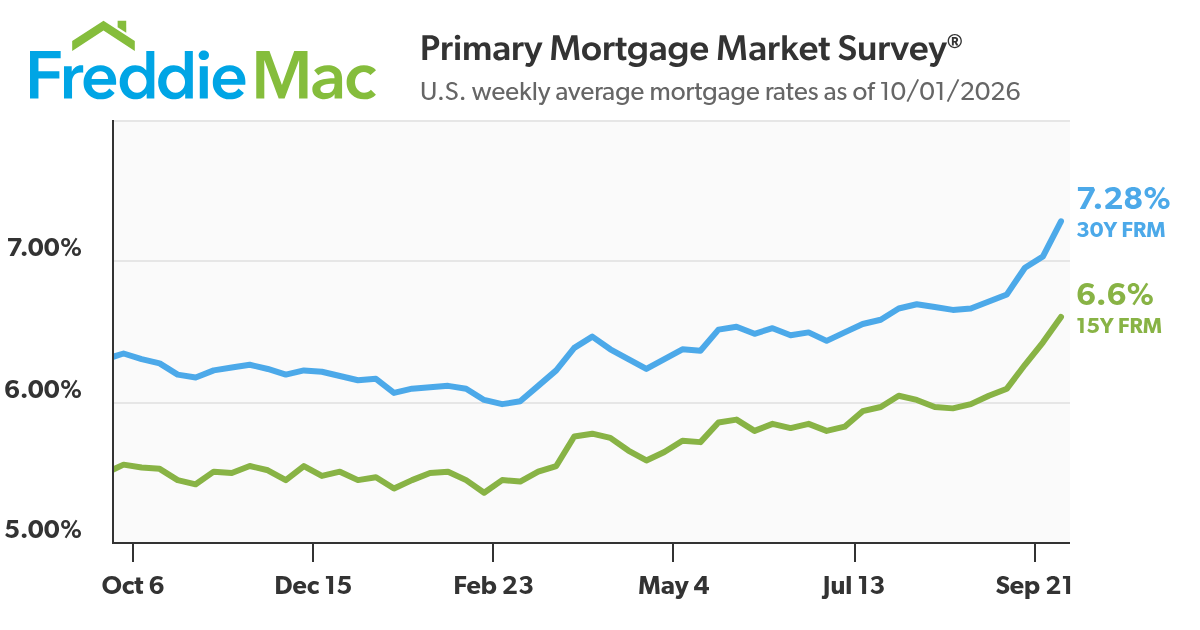
That matters to housing because inflation and interest rates are closely connected. If inflation continues to cool, some of the pressure on borrowing costs could ease. For now, however, mortgage rates remain a challenge for buyers.
At the same time, home prices are still rising nationally, just much more slowly than during the housing boom. The latest S&P Case-Shiller National Home Price Index showed prices up 1.9% from a year earlier in July.
Here is the more important point: inflation is still running faster than home-price growth. That means home values are rising in dollar terms, but losing ground after adjusting for inflation. S&P’s Rebecca Kaufman noted that “slightly lower inflation and stronger nominal home price appreciation helped narrow the gap.”
How the Market Is Shifting
For buyers, slower price growth can provide some relief, especially in markets where more inventory is creating added negotiating room. The bigger challenge remains financing, and mortgage rates may stay elevated until inflation moves closer to the Fed’s target.
For sellers, strong appreciation can no longer be taken for granted. Pricing realistically and paying close attention to local conditions matter more than they did when nearly every market was moving sharply higher.
Current homeowners are in a somewhat different position. Many are still sitting on substantial equity built over the past several years, even though the pace of appreciation has slowed. That equity can give them more flexibility if they decide to sell, buy another home, or tap some of that value for other needs.
For the housing market overall, slower price growth, persistent inflation and higher borrowing costs are creating a more balanced—but still challenging—environment for buyers and sellers.
We’re here to help you make sense of what the latest data could mean for your plans to buy, sell, or refinance. Feel free to reach out anytime—or forward this newsletter to someone who might benefit from the insight.
|