|
INVESTOR RIGHTS MONITOR
Insights You Can Use, Advocacy You Can Trust.
October 2026
| | |
Prediction Markets: Innovation for Whom, and at What Cost?
Industry interest in prediction markets continues to grow. In August, Wealthsimple released a white paper recommending broader access to event contracts. More recently, VerdX applied to become an order-execution-only (OEO) investment dealer trading exclusively in prediction market contracts. Regulators should consider this interest carefully, but it should not determine the outcome.
The issue is not whether prediction markets are innovative, whether some investors are buying them in the U.S., or which products regulators believe should succeed. It is whether offering them through regulated investment channels is consistent with investor protection and with fair, efficient and vibrant capital markets—and whether the risks can be adequately addressed.
Supporters cite potential benefits, including forecasting and hedging. Regulators should weigh those benefits against the risks to retail investors, market integrity and the regulatory framework. Contracts tied to virtually any real-world event could require costly new systems to monitor trading, detect manipulation and address misuse of non-public information. Regulators must determine whether effective oversight is feasible, who would pay for it and whether the regulatory demands would be proportionate to these products’ role in the market.
For ordinary investors, this is not an abstract debate about regulatory classification. Products that package wagering in the language and convenience of investing could encourage short-term speculation through the same platforms Canadians use to save for retirement, education and other long-term goals. The consequences may be especially serious for investors with limited savings or little capacity to absorb losses.
Caution is not resistance to innovation. Offering gambling-like products through mainstream investment platforms could expose more Canadians to losses they are not prepared to absorb. It also raises a broader policy question: whether making short-term event speculation more accessible through investment channels could divert limited savings from investments that finance Canadian businesses, support jobs, and contribute to economic growth.
FAIR Canada’s white paper, Prediction Markets in Canada: Drawing the Regulatory Line, emphasizes that legal form is only the starting point of the discussion. Regulators must also consider how these products function in practice, the risks they create and whether the securities framework can address them effectively. Until those questions are answered, broader retail access through regulated investment channels is premature.
JP Bureaud, CEO, FAIR Canada
| | |
Binding Authority for OBSI: Why the Case Against It Falls Short
As governments and regulators move toward granting the Ombudsman for Banking Services and Investments (OBSI) binding authority, some industry voices have begun to raise the spectre of higher costs and reduced access to advice and products for smaller investors.
That argument risks presenting decision makers with a false choice between effective redress and access to advice. Binding authority may entail implementation and compliance costs, and firms whose clients have more complaints upheld may face higher compensation costs. But no evidence specific to binding authority shows that those costs would be material enough to raise the price of advice or widen the advice gap. Speculative warnings unsupported by evidence or constructive proposals do not advance the debate; their practical effect is to impede reform and preserve a system that can leave investors without meaningful redress.
The status quo imposes real costs on investors. When a firm declines to follow an OBSI recommendation, an investor may be left to accept less, abandon the claim or pursue litigation. Making OBSI decisions binding would give firms a stronger incentive to resolve legitimate complaints fairly and promptly.
Investors should not have to accept less than OBSI recommends simply because they cannot afford to go to court. Canada can provide access to advice, competitive markets and enforceable redress—and a financial system that works for investors should deliver all three.
| |
Making Open Banking Work for Consumers
FAIR Canada recently submitted comments on Canada’s proposed consumer-driven banking framework. We support efforts to give Canadians greater control over their financial data and to replace risky practices such as screen scraping with safer, more secure data-sharing.
At the same time, the framework must be designed through the eyes of consumers. Federal and provincial regulators should work together so Canadians have a consistent and seamless experience, regardless of which regulator oversees a particular financial product or service. Complaint-handling processes must also be coordinated so consumers are not left to navigate gaps, overlaps, or uncertainty when something goes wrong. The success of consumer-driven banking should be measured not only by the innovation it enables, but by whether it produces safer, more transparent, and more useful financial services for consumers.
| | |
Can Canada Learn from the EU’s Retail Investment Strategy?
The European Union’s Retail Investment Strategy (RIS) is nearing final approval. Two features merit attention in Canada: its focus on whether investment products deliver value for money and its effort to impose greater accountability when firms use financial influencers, or “finfluencers,” to promote investments.
The RIS would require firms to assess product costs, charges, performance and other benefits, including through comparisons with similar products. Supervisory benchmarks would play a role in parts of the framework and could help regulators identify products warranting closer scrutiny. The objective is not simply to make fees more visible, but to require firms to consider whether investors receive reasonable value from the products they manufacture or distribute.
Canadian regulators have improved cost transparency and require costs to be considered in suitability assessments. These measures, however, do not amount to a value-for-money assessment. Suitability asks whether a product is appropriate for a particular client, taking account of the client’s circumstances and reasonably available alternatives; value for money asks whether the product’s costs are justified by its performance, services and other benefits. A separate issue is who makes that determination. Disclosure leaves investors to assess value for themselves, whereas a value-for-money framework would place a clearer responsibility on firms to assess value when designing, approving and reviewing products.
The RIS would also require firms that use finfluencers to have written agreements and oversee their promotional activities. This recognizes that firms benefit when online personalities market their products and should not be able to distance themselves from misleading or non-compliant promotions. Clear oversight obligations could also help ensure that advertising standards apply consistently across traditional and social-media channels.
In Canada, existing securities laws—including registration, disclosure and marketing requirements—apply to finfluencers and to firms that work with them. The RIS would go further by expressly requiring written arrangements and oversight when firms engage finfluencers for marketing. Canada does not currently have an equivalent set of finfluencer-specific requirements at the national level.
Canada need not replicate the EU regime. However, the RIS contains proposals worth considering as Canada examines how to strengthen investor protection.
| |
B.C. Court Ruling Highlights Account Agreement Risks
The Supreme Court of British Columbia dismissed an investor's claim against Scotia Capital Inc. arising from alleged unauthorized trading in a Scotia iTRADE account. The court concluded that the investor did not notify the firm about the trades within the timeframe set out in her account agreement.
The court found that the agreement required the investor to bring concerns about unauthorized trading to the firm's attention and that she did not do so within the 30-day period specified in the contract. The court also rejected allegations that the firm should have explained trading risks, assessed whether transactions were suitable, or obtained informed consent for the trades. It found that a discount broker does not give investment advice or suitability assessments for clients. As a result, the claim was dismissed.
For investors, the case is a reminder to carefully read, keep, and understand account agreements, terms and conditions, and disclosure documents before opening an account. Investors should pay particular attention to any provisions requiring prompt reporting of suspected unauthorized transactions.
This case also raises broader questions about the practical effectiveness of disclosure for DIY investors. While the court applied the account agreement as written, policymakers and market participants may wish to consider whether important provisions, such as deadlines for reporting unauthorized trades and related investor responsibilities under account agreements, are disclosed prominently and explained in language that ordinary investors can readily understand. In FAIR Canada's view, the case highlights the importance of helping investors understand the practical consequences of key account agreement provisions before problems arise.
| |
CIRO Data Breach Settlement Moves Forward
In August 2025, the Canadian Investment Regulatory Organization (CIRO) identified a cybersecurity breach that compromised the personal information of approximately 750,000 Canadian investors. CIRO sent notification letters to affected investors advising them that some of their personal information had been exposed in the incident.
The Superior Court of Quebec has now authorized a class action to facilitate a proposed national settlement for Canadians affected by the breach. CIRO has agreed to the proposed settlement without admitting liability. In a hearing set for January 14, 2027, the Court will consider whether to approve the settlement.
Affected investors should pay close attention to what happens next. Notice of the proposed settlement must be published by November 10, 2026, and will provide important details about the settlement and investors’ rights. Investors will have until December 15, 2026, to opt out of the settlement. Those who do not opt out will be bound by the settlement if it is approved.
FAIR Canada encourages impacted investors to carefully review the Notice when it becomes available and consider what the proposed settlement means for them.
| | | |
Investor Education Month & World Investor Week: Spot the Scam Before You Invest
October is Investor Education Month in Canada, and October 5–11 marked World Investor Week, a global initiative focused on strengthening investor education and protection. This year’s primary themes were investor resilience, digital deception and scam awareness, reflecting the changing risks investors face as more financial information and investment opportunities move online.
To mark Investor Education Month, the Canadian Securities Administrators are encouraging Canadians to stay focused on their long-term financial goals, critically assess information they encounter online and take steps to protect themselves from investment fraud. This includes checking whether an individual or firm is registered before investing, being cautious about unsolicited investment offers and recognizing that promises of high returns with little or no risk are a common warning sign of fraud.
There are several resources investors can use to put these lessons into practice:
-
Check registration: The CSA’s National Registration Search can help you confirm whether an individual or firm is registered to sell investments or provide investment advice.
-
Stay informed about potential risks: CSA Investor Alerts identify firms and individuals that may pose a risk to investors, while its Investor Tools provide information on avoiding fraud and conducting due diligence.
-
Know the signs of relationship investment scams: World Investor Week resources explain how these increasingly sophisticated scams can begin through social media, dating apps, online groups or an unexpected message before trust is used to introduce a fraudulent investment opportunity.
Investor education is an important part of investor protection. Taking the time to verify who you are dealing with, question investment claims, and use trusted sources can help you make more informed decisions and recognize potential fraud before putting your money at risk.
Explore the CSA’s investor tools and resources.
Learn more about World Investor Week and relationship investment scams.
| |
What Does “Financial Advisor” Really Mean?
The Financial and Consumer Services Commission of New Brunswick (FCNB) has produced resources to explain the differences between financial planners and financial advisors to New Brunswickers. You can find their resource here.
Unfortunately, the requirements for financial advisors under FCNB’s framework do not reflect what Canadians expect. In 2023, FAIR Canada published the results of an investor survey showing that over 90% of Canadian investors agree that a financial advisor should be proficient in all core areas of personal finance, and over half strongly agreed. New Brunswick’s title protection framework does not deliver on that expectation. As noted in FCNB’s resource, a financial advisor is only required “to have expertise in at least one investment product, like mutual funds, exchange-traded funds (ETFs), or stocks.”
This means that a person using the title “financial advisor” may have expertise and authorization limited to particular products, such as mutual funds or insurance. Investors should not assume that the title alone means the individual can advise on the full range of financial needs or products. They should ask what the advisor is qualified and licensed to provide, how the advisor is compensated and whether the advisor is restricted to certain products or providers.
When working with a financial advisor, it is crucial that you understand what services and advice they can or cannot provide. Always ask questions such as the following:
- What products are you licensed to sell?
- What services and advice are you qualified to provide?
- What education do you have?
- What conduct standards are you required to follow?
- How can I make a complaint about your conduct?
- To whom can I complain about your conduct?
- How are you compensated?
| | |
Ringing the Bell for Financial Literacy
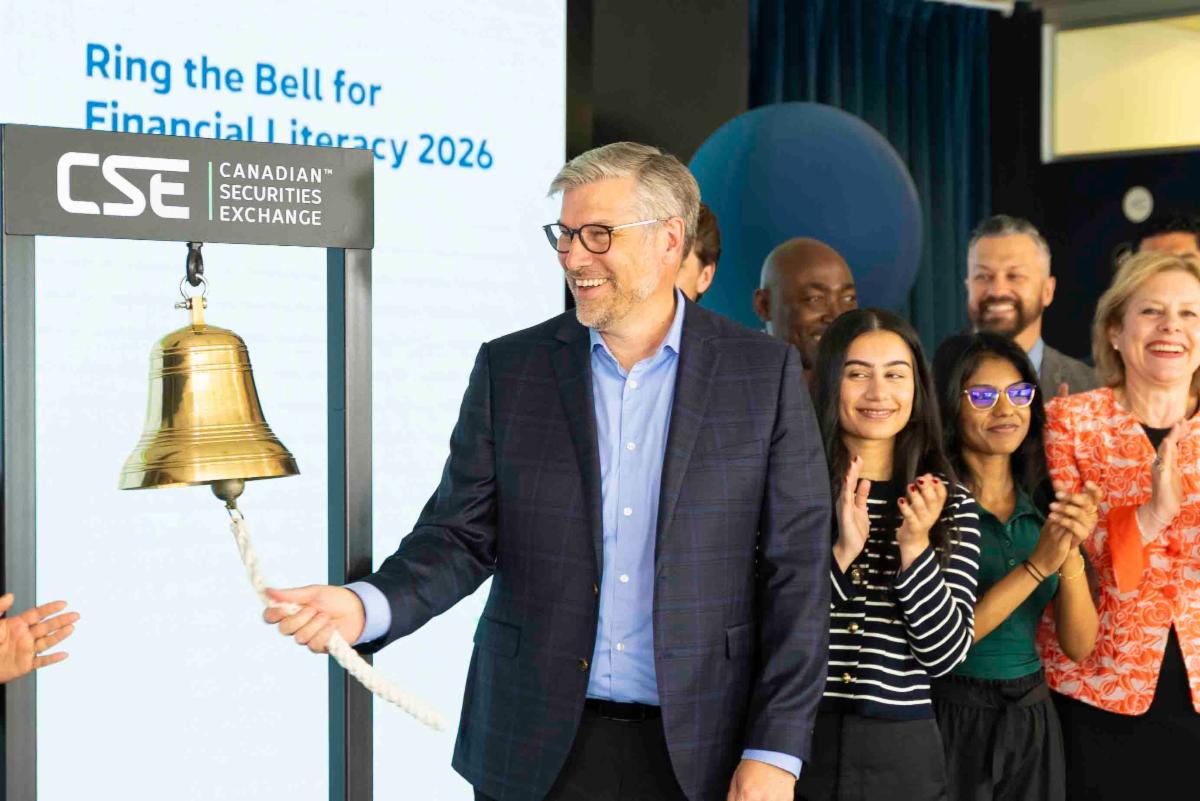
This month, we were proud to join the Canadian Securities Exchange for World Investor Week and the World Federation of Exchanges' Ring the Bell for Financial Literacy.
This year's focus on financial resilience, digital deception, and scam awareness could not be timelier. As Canadians navigate rising financial pressures, fraudsters are becoming more sophisticated, using AI-powered tools, deepfakes, and fake investment opportunities to target investors.
World Investor Week is an opportunity for Canadians to access tools, information, and resources from their local securities commissions and FAIR Canada that can help them build financial resilience, recognize the warning signs of fraud, and better protect themselves from scams.
A sincere thank you to the CSE and all partners supporting this important initiative. Together, we can build a safer and more informed investing environment for Canadians.
| | |
Do you have feedback on our newsletter or suggestions for topics you’d like us to write about? Your input is valuable and will help us improve our newsletter content for loyal subscribers like you. Please email us at info@faircanada.ca with your comments and/or suggestions.
| | | | |