|
Inflation data continues to throw the market for a spin, showing signs of a strong economy despite lingering concerns. Last week’s PCE and Q1 GDP readings, among several other variables, are continuing to test the markets’ bets on the future. GDP was expected to grow 2.5% and it came in at 1.6% annualized, while PCE came in 0.3% over expectations at 3.4% annualized, casting fears of stagflation in the economy. The service sector was the biggest contributor to the higher than anticipated personal consumption expenditures index. April’s Core PCE reading, which excludes food and energy from the print, however, came out at 2.8% annualized, 0.1% higher than the forecast but mirroring last month’s print.
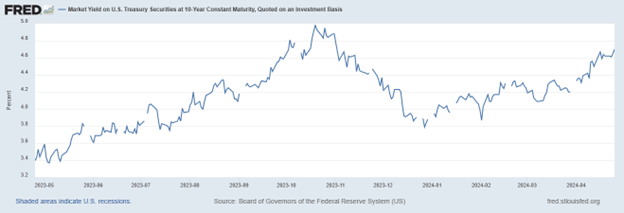
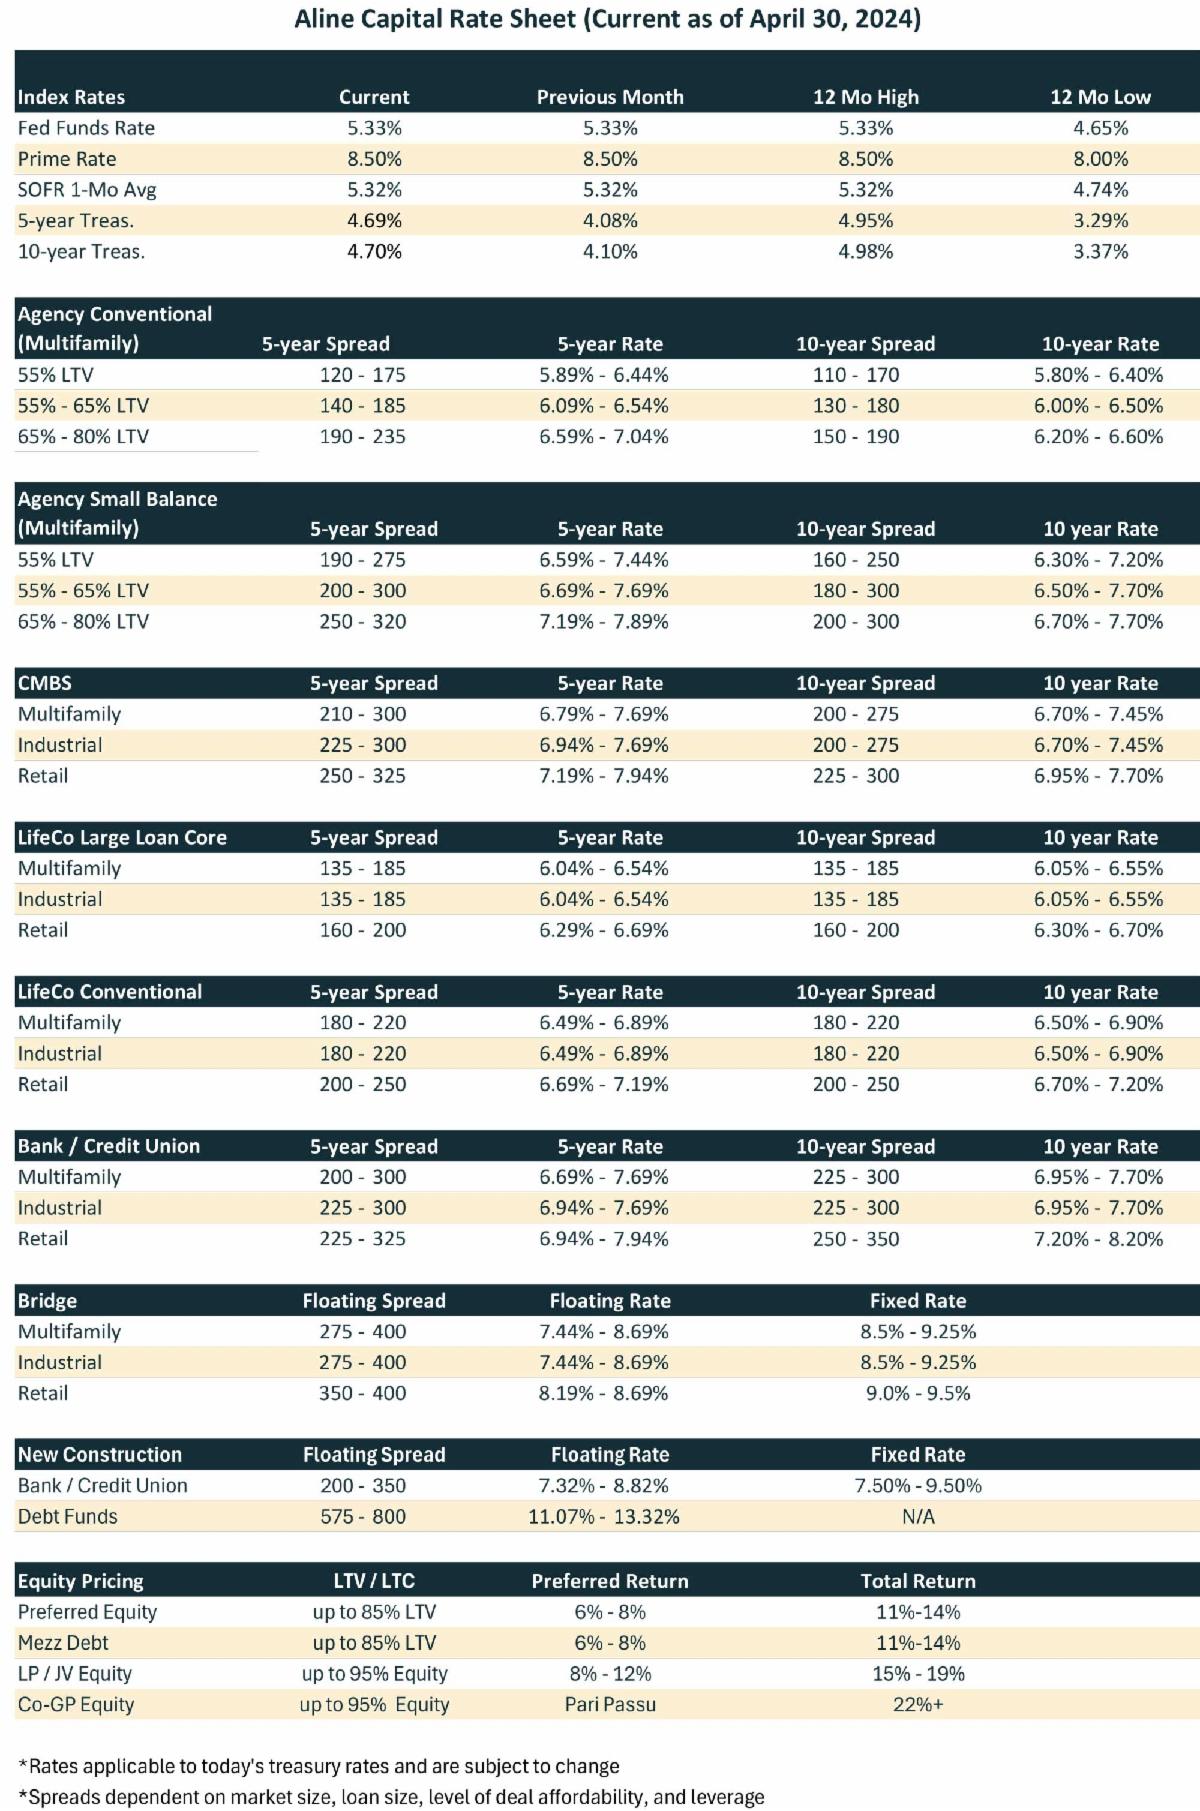
The 10 Year treasury began the year at 3.86%, rising to 4.17% by the end of January and subsequently climbing up to 4.7% last week, falling back down to “4.7%” as of April 30th, 2024. This 85-basis point swing reflects greater volatility and a lack of consensus in the market as to where long-term inflation is truly headed. Investors and lenders alike are finding difficulty pricing risk in this climate.
|