Upcoming Industry Events

June 4-7

CUES Governance Leadership Institute I - Toronto, ON


June 5

LSCI Loan Decisioning Boot Camp - Online


June 7-9

CUES Governance Leadership Institute II - Toronto, ON


June 11-12

Carolinas CUL Annual Meeting - Asheville, NC


June 13

Middle TN Chapter Meeting - Nashville, TN


June 13-15

LSCI's University of Lending - Schaumburg, IL


June 14-16

Southeast CU Conference & Expo - Orlando, FL


June 18-20

TN Bankers Association Annual Meeting - Palm Beach, FL


June 20

LSCI's School of Repossession - Online


June 21-22

Virginia CUL EMERGE Conference - Richmond, VA


June 26

KACCU Chapter Meeting - Knoxville, TN


June 27-30

NAFCU's Annual Conference - Long Bach, CA

Industry News

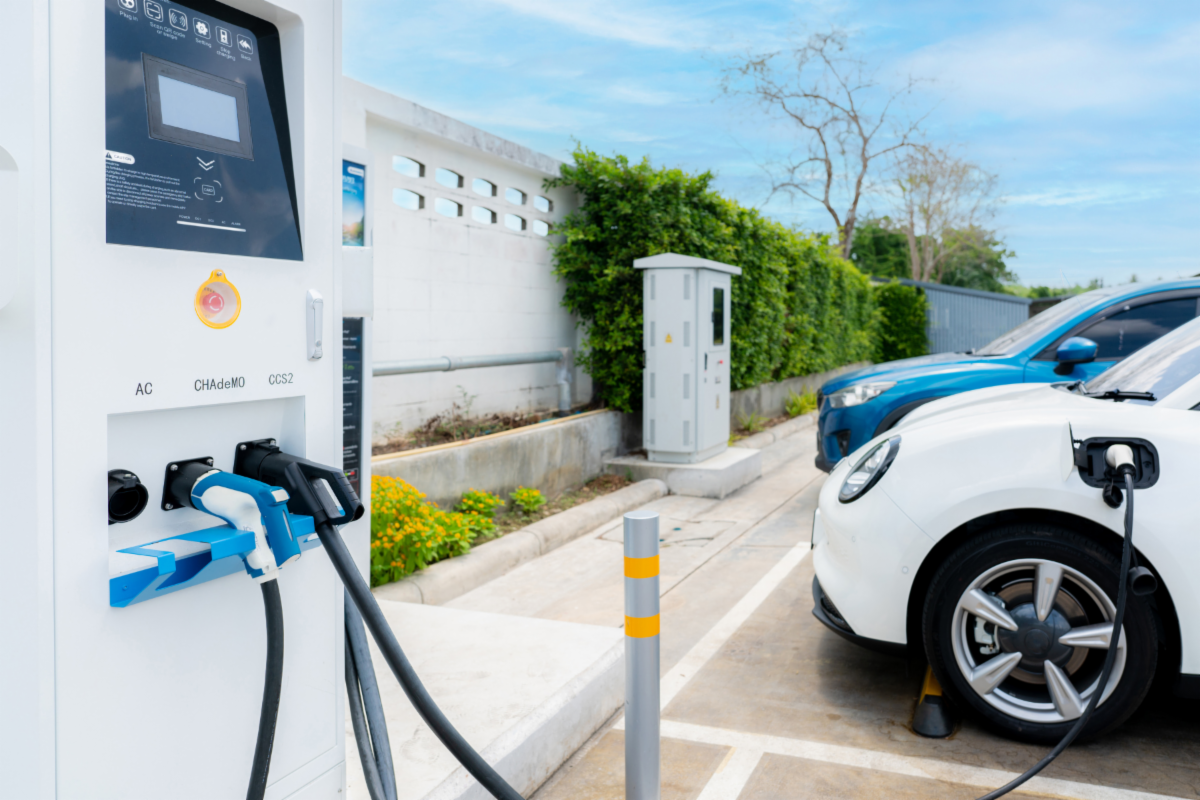
Will EVs Dent the Auto Repair Business?

Electronic vehicles (EVs) may have fewer mechanical parts prone to failure and require less repairs than internal-combustion engines, but there are some offsetting factors that tend to make their repairs more expensive. EVs have additional cooling components, more sensors, and heavier batteries causing some parts to wear out more frequently. The demand for these parts and their required calibration tools is higher and causes more complexity. The mom-and-pop auto-repair shops might not have the knowledge or capital to invest in the right training and equipment. On the other hand, large auto-dealer groups view this transition as an opportunity as they are reporting more revenue being generated per repair order for cars with alternative powertrains, such as EVs or hybrids. If auto-repair shops can't catch up, their business could end up shifting to auto-dealers.


Read Full Article

wsj.com

Housing Market Predictions for 2023: When Will Home Prices Be Affordable Again?

The limited supply of houses that is keeping the prices high is projected to remain, in part, due to those who purchased homes at record-low interest rates staying put. Any further pricing dips in 2023 will depend on the region and where the mortgage rates go. The steepest declines are expected in areas that experienced big price booms during the pandemic, such as Austin, Phoenix, and West Coast metro areas.


Overall, economists predict the housing market is more likely to correct itself from the double-digit percentage jumps we've seen in home prices over the past few years rather than crash. Current homeowners have more secure footing than those coming out of the 2008 financial crisis, with more positive equity in their homes. Another housing market crash symptom that is missing is a jump in foreclosures. Even though foreclosures are on the rise, the equity many homeowners still have should help prevent increased levels of foreclosures.


Read Full Article

forbes.com

Raving Fan Review of the Month

"Love [your] site! Everyone is so knowledgeable!"


Commodore Perry FCU


See what other Raving Fans are saying about ISI!

Data/Industry Trends

Auto Dealers Finally Have Cars to Sell Again

After years of empty lots and depressed sales, dealerships are happy to see the availability of new cars and trucks back on the lot, and buyers are happy to see bigger selections.

Learn More


Dealers are Stayin' Alive as Retail Continues to Shift

Now that many auto dealer's lots are flooded with inventory, the new challenge for dealers is to embrace the continued enthusiasm of pre-ordering and grow online offerings, including F&I (Finance & Insurance). The control of the market is shifting more towards buyers and away from sellers.

Learn More


June Holidays, Fun Facts, and Folklore!

The month of June brings beauty in all forms, from flowers to sunlight. Find out what events are happening this month, gardening tips, astronomy highlights, seasonal recipes, folklore, and more!


Everything you need to know about June

almanac.com

Force-Placed CPI or Blanket Insurance


Are you reviewing switching from force-placing CPI to blanket insurance, or from blanket insurance to force-placing CPI?


If so, make sure you do your homework. I repeat, DO YOUR HOMEWORK. There is no cheating allowed when making a decision this big. Changing your program is more than changing insurance program types, it is a fundamental philosophy change across your financial institution.


We see so many lenders making a change to "fix" or "solve" one area of their pain point or problem they are experiencing. Only to learn later, that the unintended consequences of the change were not expected and worse than their original issue they were trying to fix.


Make sure you speak with a company or someone that offers both program types, blanket and force-placed. If they only have one program type, they are going to tell you all the benefits you want to hear about the type they offer.


Taylor MacCurdy

CEO

tmaccurdy@isicpi.com

704-957-5024


We would be privileged to discuss further, contact us at management@isicpi.com.

Connect with Us:
Facebook  Twitter  Instagram  Linkedin  

Contact Info:


Phone: 800-749-5440

Email: management@isicpi.com

Website: insurancesystemsincorporated.com

ISI is an administrator of Collateral Protection Insurance (CPI) and Blanket Lenders Single Interest (BLSI) for financial institutions. We provide insurance, lending, and marketing products to the financial institution marketplace. Our mission is to deliver the best products and services in the industry through responsive service, comprehensive coverage, and advanced technology. We combine the lender's vision and our proven plan to create a portfolio that matches the lender's needs for a successful program and partnership.