Market Leadership Flips: The "S&P 493" Takes the Reins | |
If you enjoy market drama with a fascinating twist, June provided a masterclass in market rotation. For months, we have watched a small handful of tech hyperscalers carry the heavy index load. However, June threw a curveball that shook up the status quo, featuring an intense rotation away from mega-cap tech giants and toward chipmakers, smaller companies, and traditional defensive pockets.
Despite a volatile 30 days that saw the mega-cap heavy S&P 500 Top 50 slide 4.62% in June, the second quarter as a whole capped off an absolute powerhouse performance for the broader markets. We will break down these under-the-radar shifts—and how blockbuster semiconductor earnings managed to soothe macroeconomic anxieties—in the next edition of the GRAnderson Wealth Management Group Monthly Economic Update, due by the end of this week.
| The Q2 Breakdown: Small- and Mid-Caps Steal the Spotlight | |
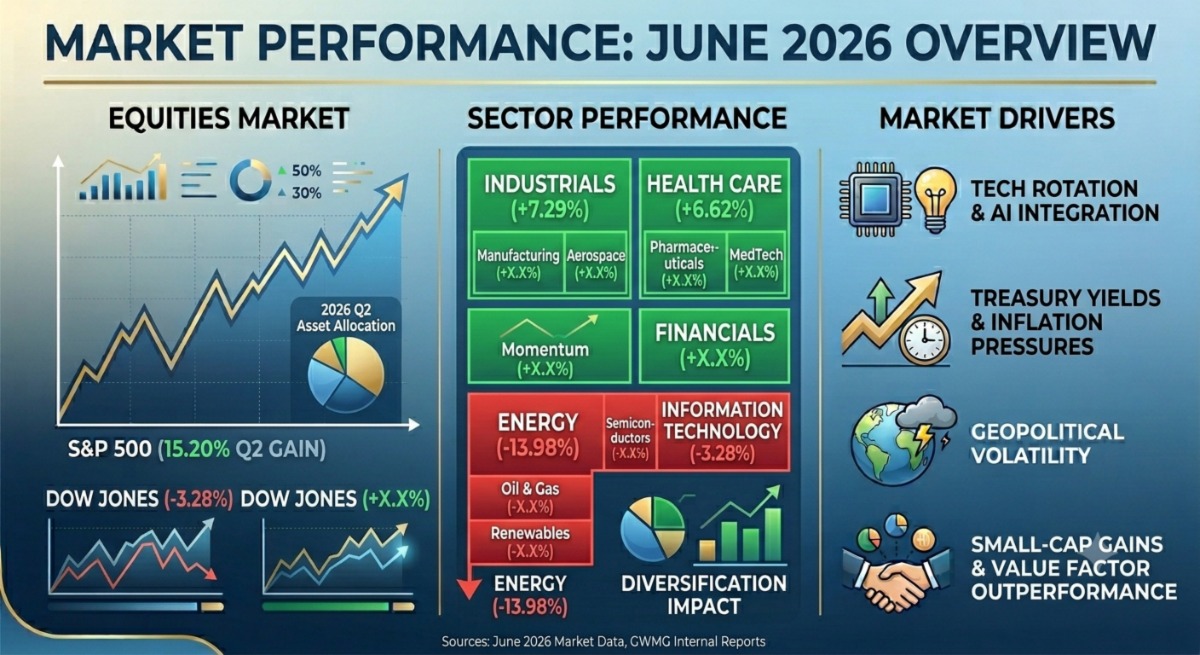
What a difference a quarter makes. While large-caps took a well-documented breather in June—pushing the S&P 500® down 0.95% for the month—the full Second Quarter 2026 results reveal a beautiful broadening of market participation. Investors aggressively hunted for value beyond the heavyweights, sparking a massive quarterly surge in smaller, more agile corporations.
The second quarter finished with stunning multi-digit returns across the board:
-
The Small-Cap Explosion: The S&P SmallCap 600® spearheaded the quarterly charge, jumping 7.29% in June to lock in a spectacular 19.70% gain for Q2.
-
Mid-Cap Momentum: The S&P MidCap 400® was right behind, advancing 3.59% for the month and securing a stellar 14.47% quarterly return.
-
The Benchmark Resiliency: Powered by its strong runs in April and May, the S&P 500® gained 15.20% in Q2, marking its best quarterly performance since the second quarter of 2020.
Q2 Sector Contributor Leaderboard
The internal engine of the market shifted over the quarter, showcasing where the true strength resides. Out of all large-cap sectors, only Energy and Utilities ended Q2 with losses. Here is how sector contributions stacked up for the S&P 500's total 15.20% Q2 return:
-
Information Technology: +10.46% (Despite a 3.28% pullback in June, it finished Q2 up a staggering 31.79%)
-
Industrials: +1.34% (Surged 7.29% in June to lock in a 14.85% Q2 return)
-
Financials: +1.13% (Finished the quarter up 9.01%)
-
Consumer Discretionary: +0.91% (Finished the quarter up 9.27%)
-
Communication Services: +0.85% (Finished the quarter up 8.32%)
-
Health Care: +0.83% (Finished the quarter up 8.78%)
-
Real Estate: +0.17% (Finished the quarter up 8.52%)
-
Energy: -0.54% (Slid 13.45% over the quarter as oil retreated)
See this month's GRAnderson Wealth Management Economic Update for details.
| |
Greetings!
If this is your first exposure to the GRAnderson Wealth Monthly Update -- welcome! We hope you receive a valuable amount of information that will help with your investment decisions!
Sincerely,
Gregory Anderson
Founder and CEO
|
Click here to see the latest issue of the
New issues generally appear the 4th or 5th of every month.
| | Fixed Income & Commodities: Hard Assets Slide as Bonds Hold Ground | | |
The pressure on mega-cap tech at the end of the quarter did not destabilize the bond market. Even as Treasury yields fluctuated and the yield curve flattened in response to hawkish sentiment from the Federal Reserve and easing geopolitical fears, fixed income offered a stable cushion. All reported bond indices logged positive total returns for the second quarter.
A Broad Q2 Retreat for Hard Assets
In sharp contrast to the energy surges that defined the start of the year, commodities ended the second quarter firmly on the backfoot. Crude oil and gold prices pulled back heavily from their prior highs:
-
Energy Plunge: S&P GSCI Energy cratered 13.98% in June, dragging its total Q2 performance down to a loss of 17.02%.
-
Precious Metals Retreat: The S&P GSCI Precious Metals Index gave back 2.72% in June, finishing the quarter down 14.32%.
-
Industrial Metals Bright Spot: Conversely, Industrial Metals held its ground against the macro gloom, with the S&P GSCI Industrial Metals index finishing Q2 up nearly 1% (0.82%).
Find details about these trends and other statistical categories in our latest Economic Update.
| | What we're watching at GRAnderson Wealth | | |
As we transition into the second half of 2026, we are closely tracking several critical market indicators to navigate these shifting tides:
-
The Tech Hyperscaler Reset: We are evaluating if the temporary pullback in mega-cap tech represents an "AI trade" bubble burst, or a healthy valuation cooling period before the next leg up.
-
The Staying Power of Small-Caps: The massive 20% quarterly surge in the S&P SmallCap 600® indicates a robust economic undercurrent. We are watching to see if easing yields will fuel this broadening rally further.
-
Yield Curve Transitions: With hawkish Fed sentiment flattening the yield curve, our eyes remain fixed on how shifting interest rate expectations will impact absolute return models.
Ultimately, sharp shifts in factor and sector dominance validate our core commitment to looking at non-traditional, alternative asset classes to smooth out portfolio turbulence. By managing your portfolio through discipline and an intentional behavioral lens, we ensure your financial foundation remains undisturbed by the noise of volatile headlines.
| | Market Summary: At a Glance | |
-
A Record-Breaking Quarter: Despite an uneven June, the S&P 500® clocked an incredible 15.20% gain for the second quarter, marking its best quarterly performance since mid-2020.
-
The Broadening Rally Explodes: Smaller companies dominated the quarterly field; the S&P SmallCap 600® jumped 19.70% and the S&P MidCap 400® rose 14.47% in Q2 as mega-caps rotated.
-
Tech Rules Q2 Total Return: Information Technology finishing the quarter up 32% made it the primary engine of Q2 equity returns, despite its 3% step back in June.
-
Bonds Deliver Wins: Shifting Fed policy and yield fluctuations failed to derail fixed income, with all primary bond indices closing the quarter in positive territory.
-
Commodities Hit the Brakes: Hard assets slid broadly in Q2, fueled by sharp quarterly drops in Energy (-17.02%) and Precious Metals (-14.32%).
| |
Founded in 2005, GRAnderson Wealth Management Group, Inc., is a registered investment advisory firm specializing in comprehensive financial planning and investment management services for clients with life goals. In addition to traditional investment solutions, value is added with alternative investments in direct ownership in energy, commercial real estate, managed futures and private equity.
GWMG specializes in investing and financial advising for individuals, business owners, 401(k) plans, pension and profit sharing plans, and personal family trusts.
GRAnderson Wealth Management Group, Inc.
303-228-3160
| | | Stay Disciplined. Stay Diversified. | | | | |