|
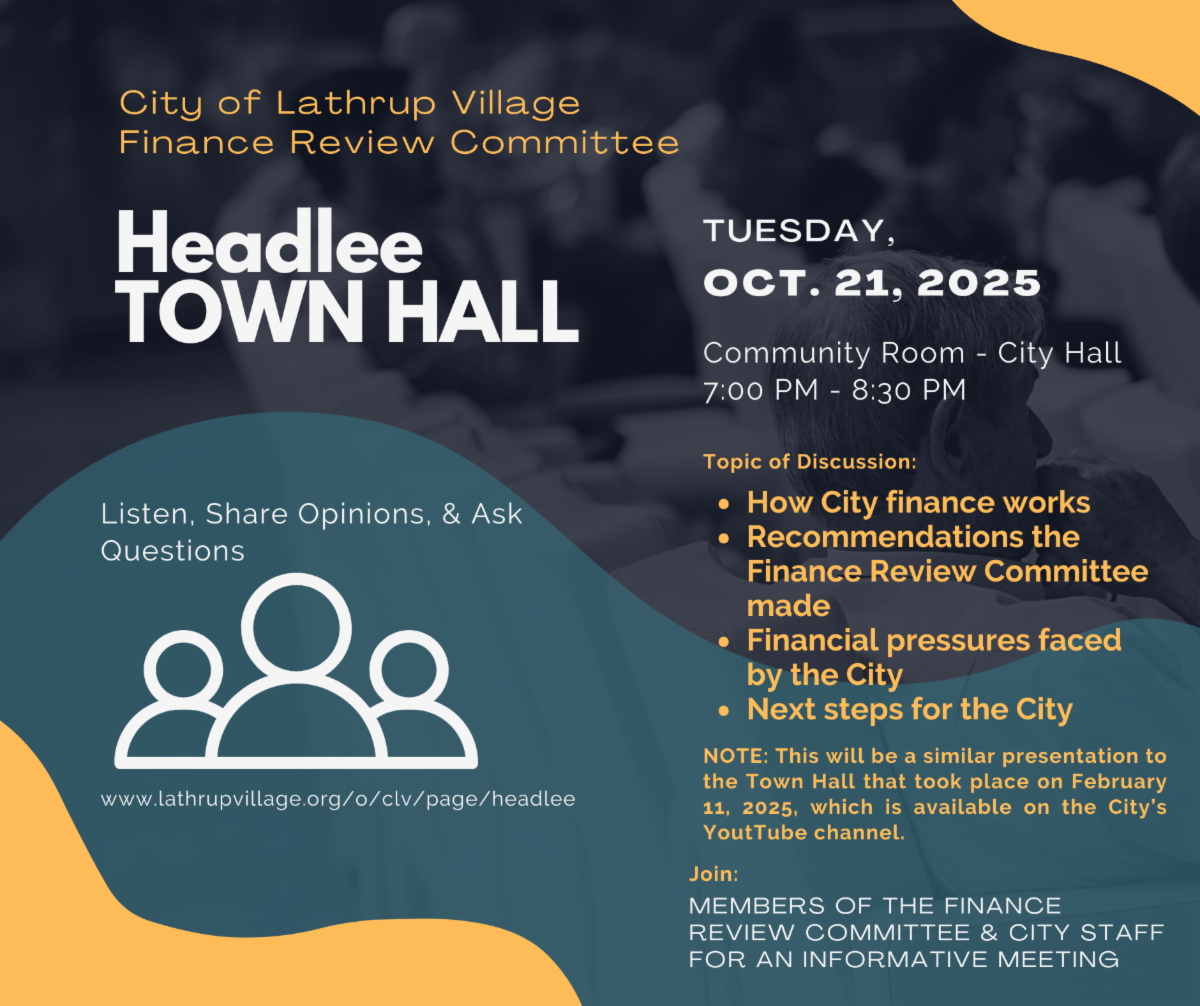
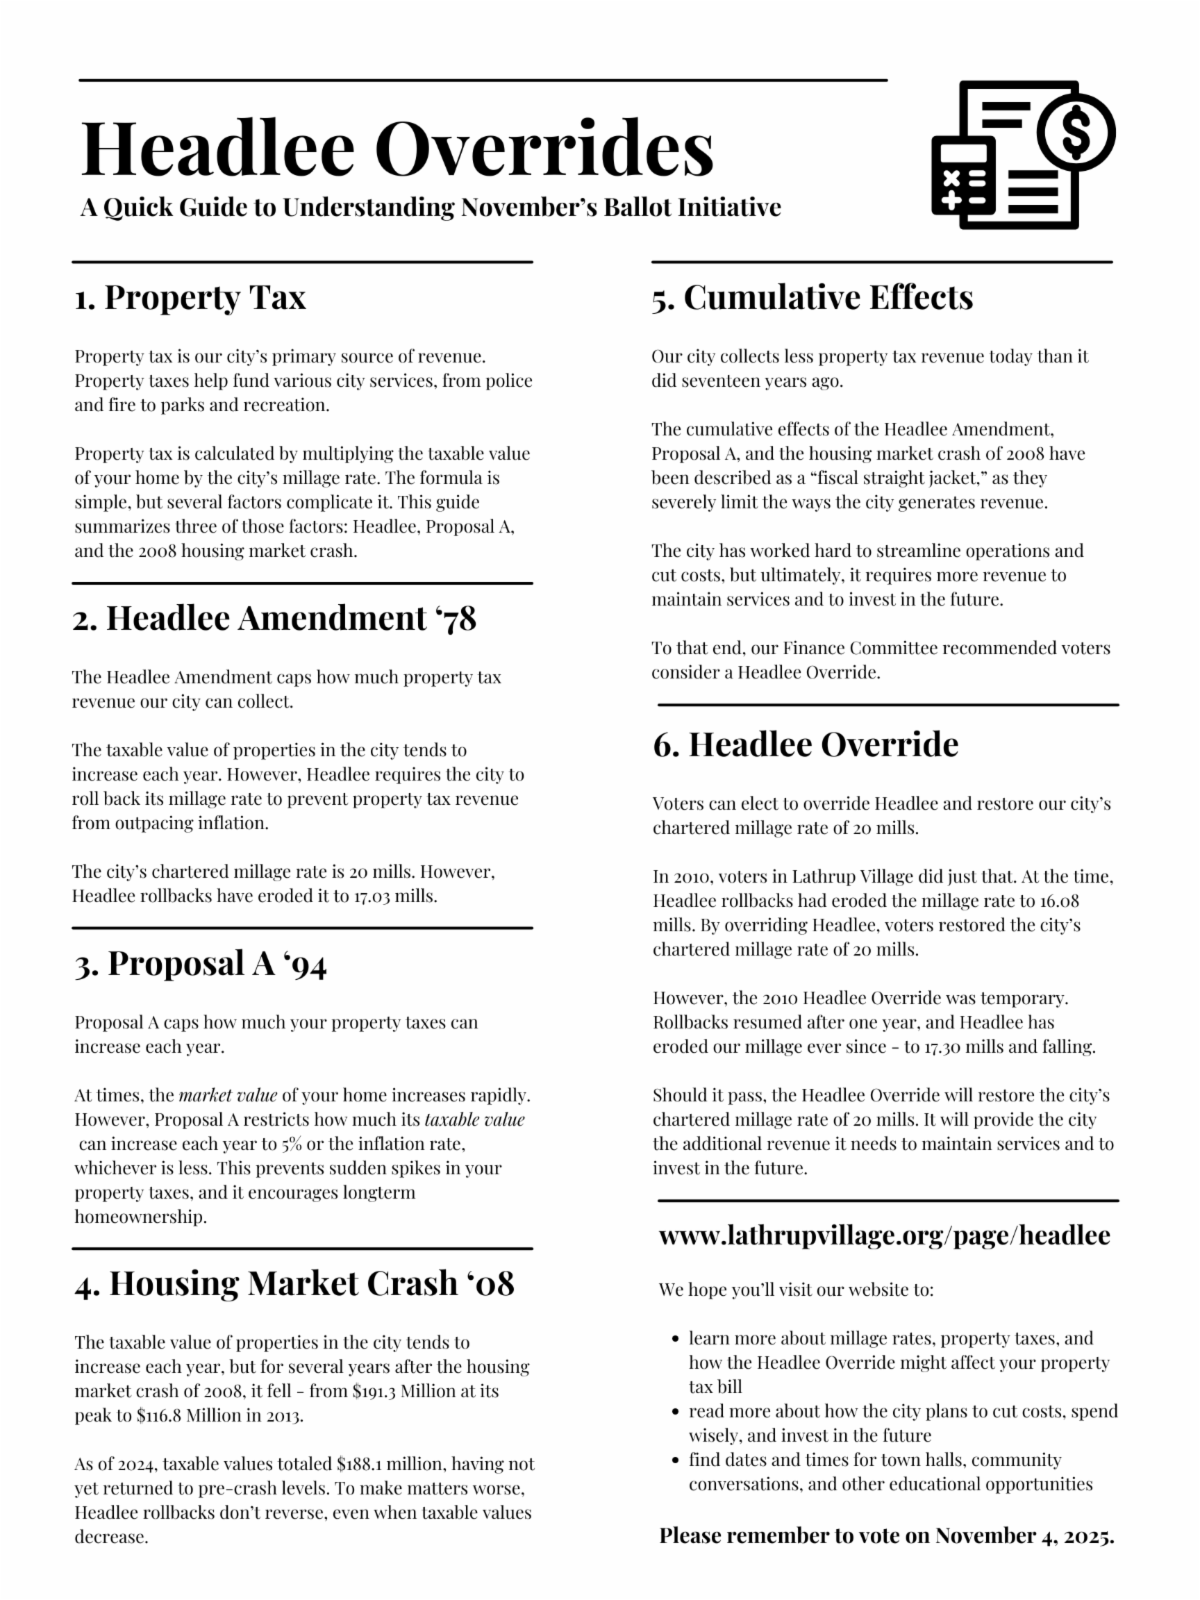
There has been a lot of information shared on social media over the past month, especially related to City finances and Headlee. Below is my view (City Administrator Greene) and some clarifications on items that have been posted and have made their way from social media to my office. If you have any questions, please don't hesitate to contact City Hall.
Employee payouts for compensated absences: If you would like a deep dive into Governmental Accounting Standards Board (GASB) statement requirements for compensated absences, please click here. The City follows GASB statements via our Auditors for reporting purposes.
Compensated absences (ex: sick & vacation leave) are considered long-term liabilities and appear as liabilities on the government-wide statements; however, they do not appear on financial statements unless an employee is entitled to a payout based on contract language or they leave employment with the City.
Claims are being circulated that the City has paid out over $620,000 since 2019 for compensated absences. If the claimant is willing to share their math, that would be appreciated. Payments above and beyond normal pay or usage of PTO, include those PTO hours obligated to employees leaving employment of the City (which includes long-tenured employees who held substantial PTO banks) and/or contractual obligations (ex: union comp time payouts). While reviewing PTO banks, accounting for the 100% staff turnover on the administrative side of City Hall since 2019, we are seeing ~$300,000 of obligated PTO that has been distributed.
Based on the City’s independent audit, conducted by Maner Costerisan, the City’s outstanding liability associated with compensated absences is ~$150,000 as of June 30, 2024. There is no argument that the City is on the hook for this money in the long term; however, it would take every single City employee leaving employment within the same fiscal year to see this payout hit the books.
The City has adopted updated policies to limit PTO rollover from year to year, which limits the City’s long-term liabilities. These updates started back in January 2025 with the approval of the LVPD Union contract, and the City Council carried the same language over to the administrative employees via an update to the Personnel Manual.
City Administrator Contract: My contract with the City has been used as an example of a “spending problem” that the City has. There is zero doubt I have a bias in this topic, but as a former Village Administrator and an Assistant City Manager who assisted in the contract negotiations of two new City Managers, I have had the opportunity to review numerous City Administrator/Manager contracts over the years and have a unique view towards these agreements that the general public does not have. This contract is not out of the ordinary for a Manager/Administrator when you factor everything in, such as retirement contribution levels and the level of insurance coverage a community can provide. For those who have never worked in municipal government before, I would implore you to review other managers' contracts before jumping to a conclusion. Many are available via a simple Google search or can be available by contacting a specific City. Additionally, you can take a look and see what our state government & federal government partners receive for a general comparison.
To your Council’s credit, this contract is less than what was originally asked of them. There is a balancing act when it comes to City Administrator contracts, doing what is good for the City and attracting qualified candidates, and the Administrator has to be able to have some benefits/protection as they are always one meeting away from being publicly fired without cause.
Audits: There is information being pulled and shared from older City audits.
I would recommend reviewing the most recent information to see where the City currently stands. Recent audit documents can be found on the City’s website.
One question specifically that has come up is regarding “Interfund Receivables/Payables.” For example, you may see a chart that shows the General Fund owing the Water/Sewer Fund money, and ask why. One example of why the general fund may owe the water/sewer fund money is for water and sewer late payments.
You may have seen the meetings where the Council approves a special assessment roll for delinquent water/sewer payments. Those late payments are then collected via taxes and deposited in the General Fund. The General Fund then needs to transfer those specific monies to the water/sewer fund for cash reporting purposes, as they are payments for water/sewer service. Once transferred, that amount is removed from the interfund receivables/payables report.
MI Community Financial Dashboard: The City formally utilized a tool called Munetrix for yearly reporting that was required by the State of Michigan for State Shared Revenue requirements. As of 2024, the State no longer required those specific reports for State Shared Revenue payments, so the City was able to cancel the Munetrix subscription, saving the City $4,000+ annually. However, the State has created the MI Community Financial Dashboard, which the City could have been utilizing for the previously required reporting. A link to that dashboard is on the City website.
The dashboard provides high-level information pulled directly from the City’s independent audit. Without doing a deep dive, some of the information can be misleading. If you have questions, please reach out.
For example: In 2021, the report shows TOTAL City Revenue of $15.53 million and TOTAL expenditures of $10.47 million. Seeing this, it looks like the City is doing amazing. However, diving deep, we realize this is when the voter-approved street improvement bond millage hit the accounts. Then, over the next couple of reporting years, it shows the City expenditures exceeding City revenue each year, including by $3.32 million in 2023. These are the years when that bond project (along with other City projects) was completed and paid for from the bond money that was previously deposited in our accounts.
In reporting year 2024, the City begins to return to normal with TOTAL revenues of $9.78 million and TOTAL expenditures of $9.74 million. Included in this was the City adding funds to the General Fund’s Fund Balance (i.e., revenues exceed expenditures).
Downtown Development Authority: The Downtown Development Authority (DDA) Act was passed by the State of Michigan in 1975 to give municipalities an economic development tool they could use to rebuild and reposition their downtowns, increase taxable values, and encourage private investment.
The LVDDA utilizes a Tax Increment Financing (TIF) mechanism to finance many of its projects. The DDA’s TIF is derived from some of the new taxes generated by new building construction in the DDA District, which is then directed into downtown purposes to encourage economic growth, greater tax values, and private reinvestment. The TIF can also keep tax revenue that would have otherwise been transferred to other taxing jurisdictions (ex: County, DIA, Zoo, etc.) Due to the DDA Act, the LVDDA is also allowed and does impose a 2-mill levy against all properties within the DDA District.
In 2025, via the TIF & 2-mill levy, the LVDDA is projected to bring in ~$500,000 to cover its operational and project expenses (total projected DDA revenue for FY 26 is ~$530,000). If the City were to dissolve the DDA, the City would lose the 2-mill levy, and any taxes we previously would have kept (i.e., County, DIA, Zoo, etc.) would then be required to be redistributed to those entities. This means the City’s General Fund would only see a tax revenue increase of ~$340,000 (total City loss ~$160,000). Now, while the General Fund revenue would see a spike, the expenses the DDA covered do not instantly go away, so the General Fund would be on the hook for all those costs, with overall less money to cover them. The DDA’s approved budget expenses in FY 26 are ~$519,000, which includes covering the costs of major capital projects that the DDA is funding.
The DDA and City operate with a cost-share agreement. The current agreement runs through June 30, 2026.
If you ever have questions, please feel free to reach out.
|