|
The big picture goal over the last month has been to reduce beta and risk where possible. Here’s what we did:
• Sold EWY (South Korea) and FXI (China): Both were showing daily moves of 6–7%. That level of volatility is not something we want in the portfolio right now. Also sold long-term bond ETF and trimmed Mid-Term & LCorprates. Why? We know from the past that as inflation rises so to do yields, and when they go up, prices go down. If we go into a growth slowdown and yield start retreating, will revisit.
• Trimmed Gold Miners and Silver: Moved both to minimum 1% positions. The long-term thesis remains intact — metals are supply-constrained, historically under owned, and tend to perform well in stagflationary markets. With the U.S. deficit now over $39 trillion and growing, the fiscal backdrop hasn’t changed. We just reduced the short-term volatility exposure.
• Added US Dollar ETF: The dollar trend has shifted to the upside, which is consistent with a rising inflation backdrop — not surprising.
• Added Commodities ETF: We want exposure to rising inflation.
If the trend continues or changes, expect moves.
Quarter-End Rally — What to Make of It
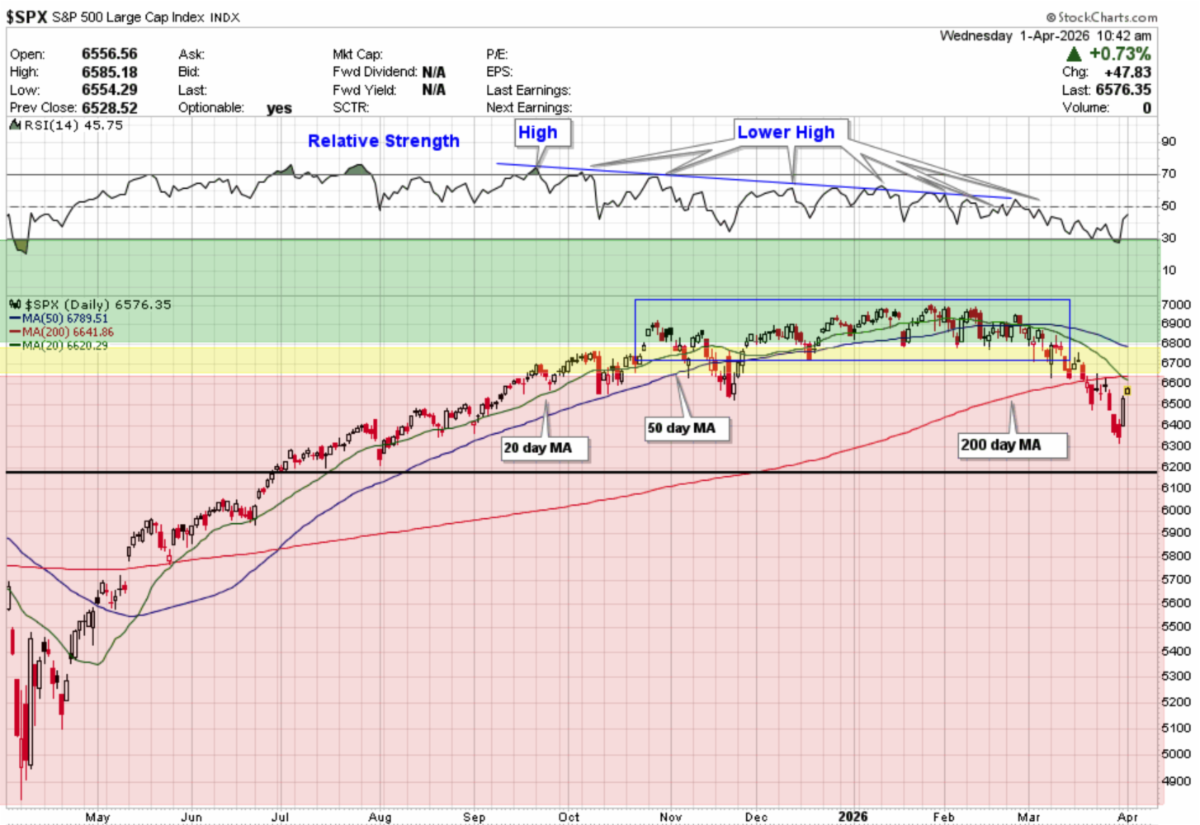
Yesterday was quarter-end, and we saw a significant move to the upside. How significant? The last time we saw a rally of this magnitude on the last day of the Quarter was 2008.
This is textbook market behavior. Some of the biggest single-day rallies occur during corrections and or bear markets. Yesterday was a perfect example. Markets got extremely stretched to the downside and snapped back. That’s not a surprise; that’s how it works.
Technically, this is a classic snapback: indexes that broke below their 200-day moving average are rallying back toward it, while indexes that held the 200-day are bouncing off it. That’s countertrend behavior — normal and expected — until proven otherwise.
We ignore the first few days of any rally attempt — that’s noise. What matters is what comes next: Can the market follow through? Does leadership emerge? Do quality setups develop?
We also still have daily headlines from the administration to navigate, and an announcement tonight on Iran. Add that until the Strait of Hormuz is open, oil prices and inflation will remain a headwind.
Bottom line: This was an oversold rally sparked by headlines — but not defined by them, and certainly not confirmation of a reliable bottom. Now we watch: the quality of the follow-through, the emergence of leadership, and the health of market internals. If the rally lacks conviction, if economic pressure builds, or if leading stocks begin to roll over — then this remains what it most likely is: a rally within a correction.
A reminder on our discipline: we sell sector positions before touching any core holdings (QQQ, SPY, DIA, RSP). If you ever see us moving core, you’ll know we see another leg lower ahead. We’re not there yet — but we’re watching everything closely.
|