Pricing Intelligence Report

MARCH 2026

This report tracks QSR net lease inventory across the Intermountain West and highlights current pricing, lease terms, and income concentration.


Executive Overview:

March pricing data shows the Intermountain West QSR market is still rewarding platform strength over lease term alone.


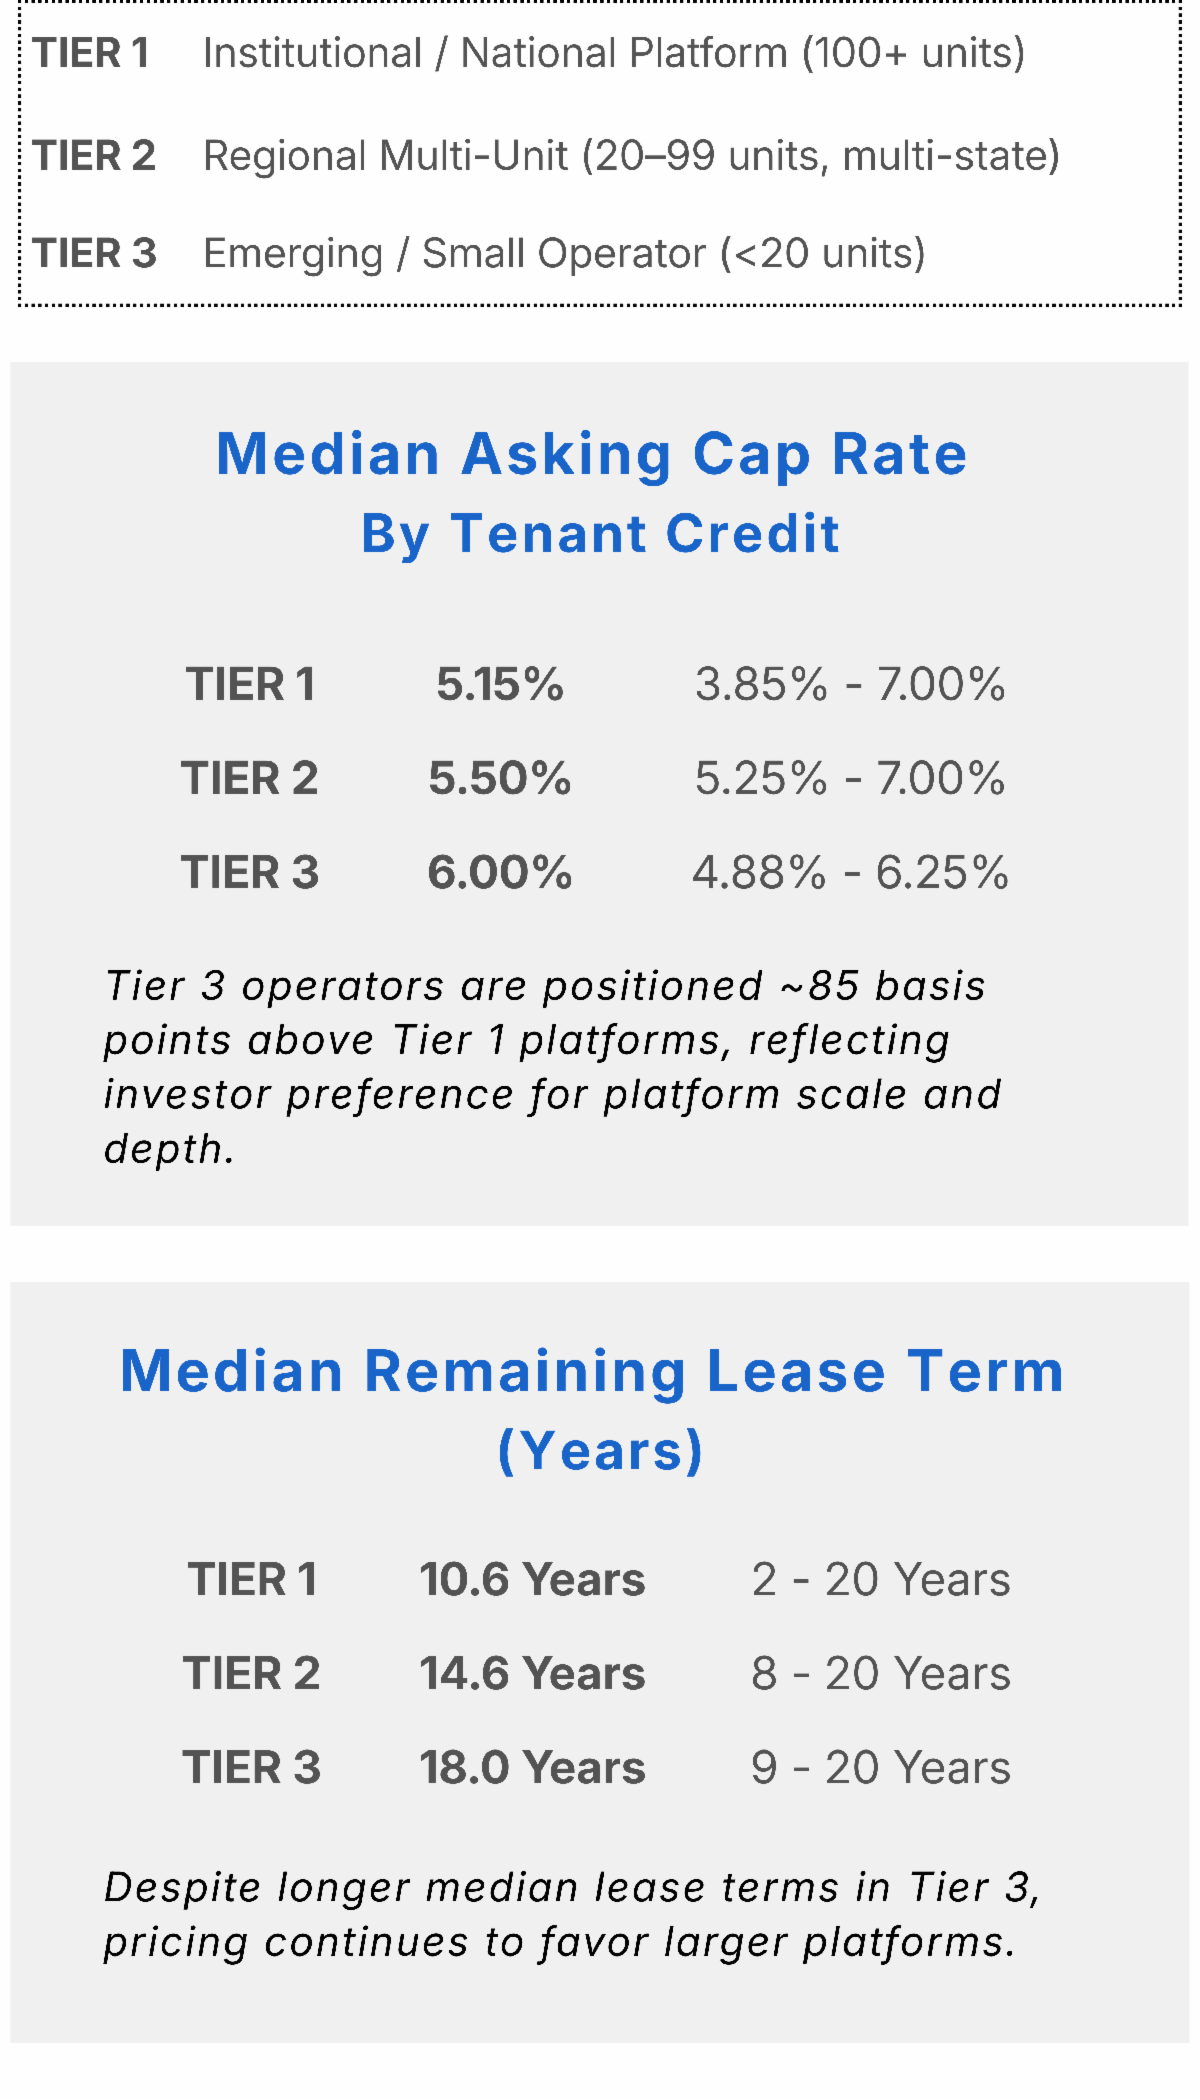
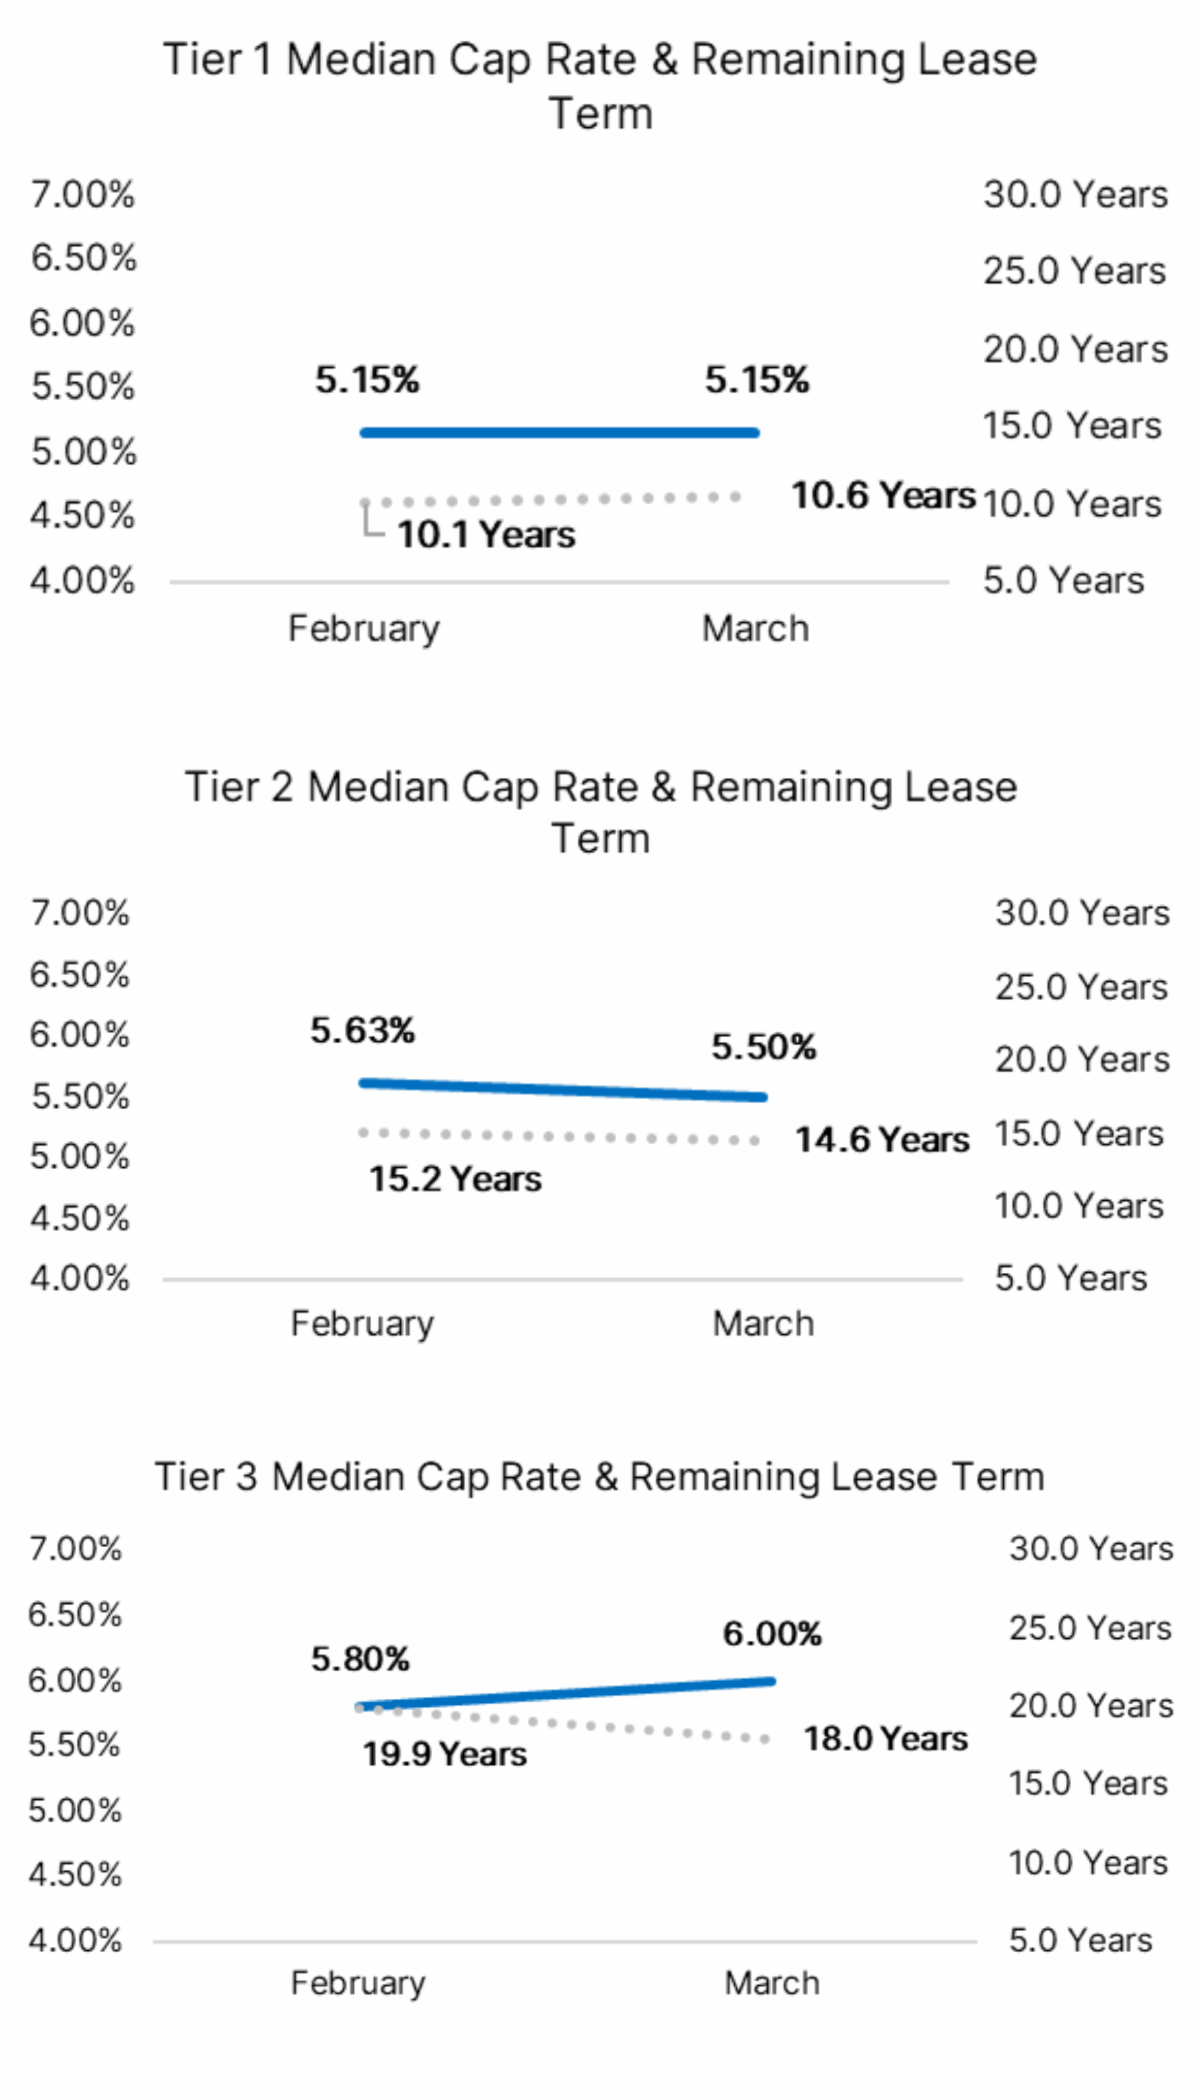
Single-tenant cap rates held firm at the top of the stack, with Tier 1 at 5.15% and Tier 3 moving out to 6.00%, widening the spread to roughly 85 basis points despite longer leases for smaller operators.


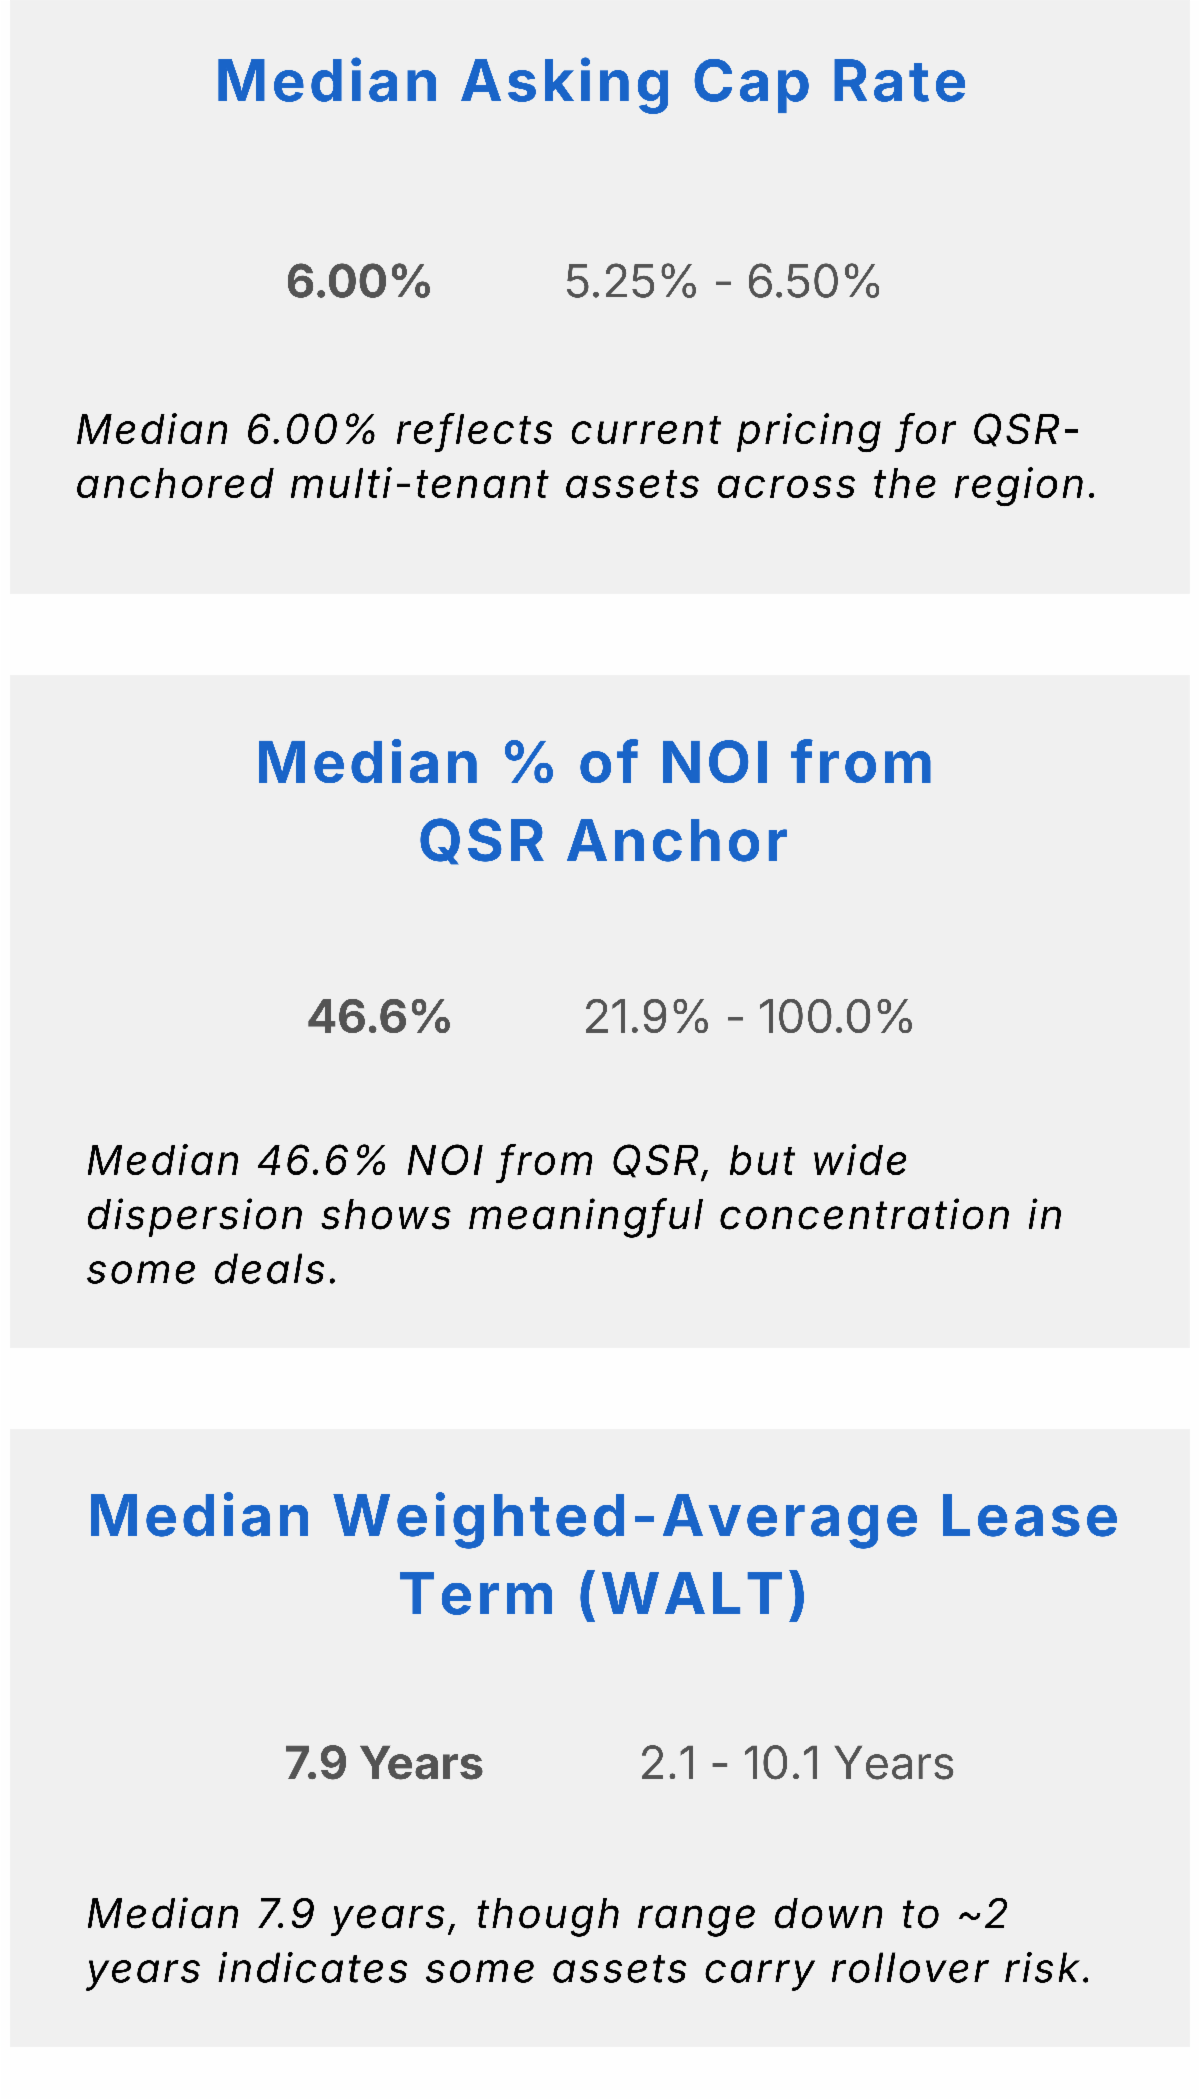
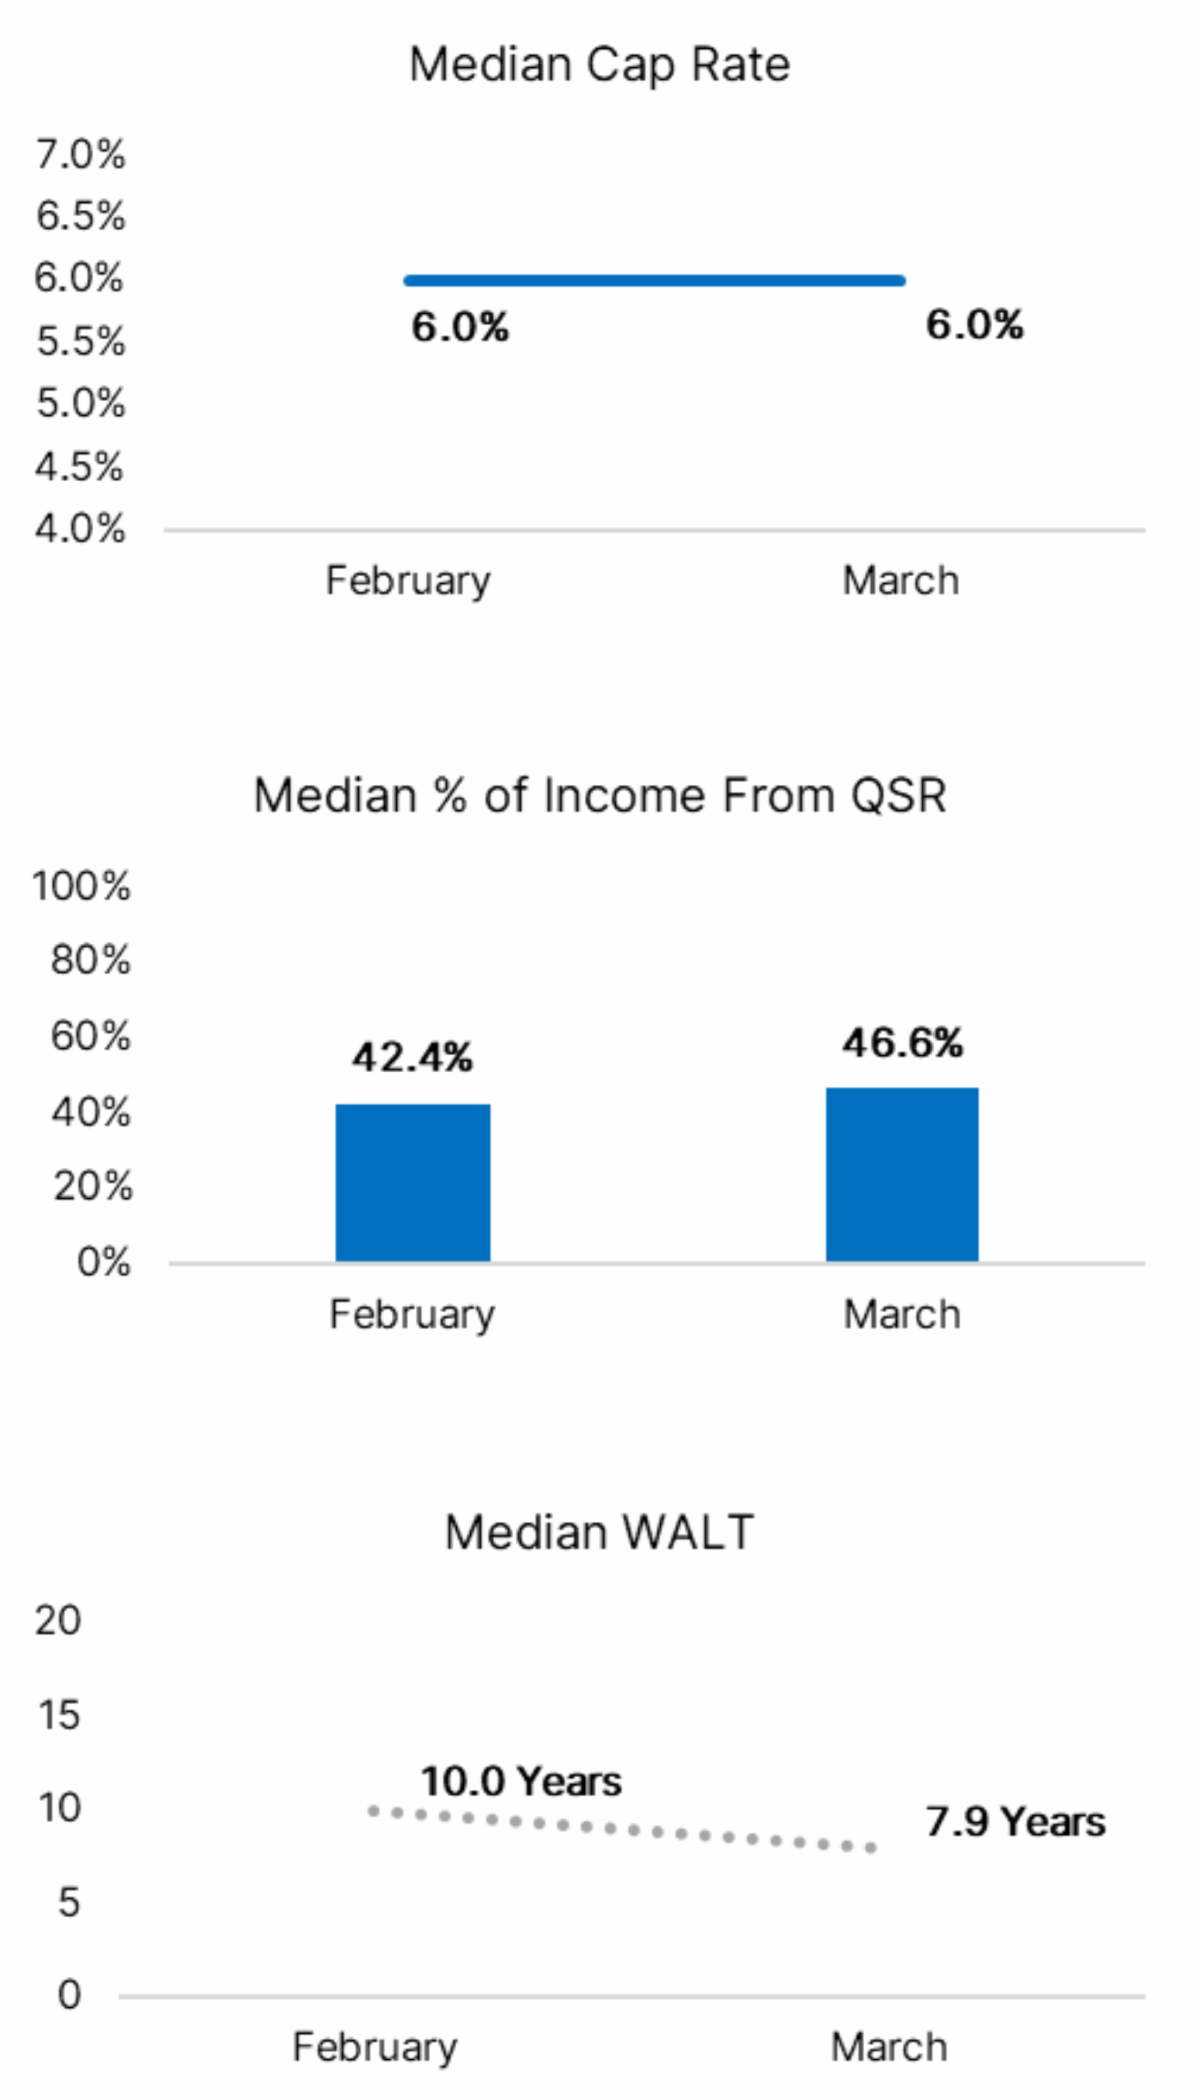
In the multi-tenant space, median asking cap rates stayed flat at 6.00%, but WALT fell to 7.9 years as median NOI from QSR rose to 46.6%.


SINGLE-TENANT NET LEASE (STNL)

Summary: Cap rates remained most aggressive for larger platforms, with Tier 1 holding at 5.15% while Tier 3 expanded to 6.00%—an ~85 basis point spread despite longer lease term profiles among smaller operators.


MULTI-TENANT RETAIL (MTR)

Summary: Median asking cap rates held at 6.00%, while median WALT declined to 7.9 years and median NOI from QSR increased to 46.6%.


Prepared by Evan Hawksley

Retail Investments Advisor

NAI Excel | Lehi, UT

M: 801.209.7097 | ehawksley@naiexcel.com

This report is provided for informational purposes only. Data is derived from publicly marketed listings and broker disclosures and is believed to be accurate. Asking pricing and lease metrics may differ from final transaction terms. Nothing herein constitutes investment, legal, or tax advice.


Curious how your asset would be priced in this environment?


Call or text me at 801.209.7097, or reply to this email.