January 13, 2025

coming_soon_stamp.jpg

Client Conference Call


We will be hosting a client conference call on Thursday, January 30th at 4:00 pm CT. The title of the call is “Market Perspectives for 2025.” We will weigh and discuss factors we feel will make an impact during the year.  We will also provide an update on tax changes for 2025.


Please dial the toll-free number 888-800-2082 a few minutes before 4:00. The call will last about 30 minutes, and you will have the opportunity to ask questions near the end. If you are unable to listen live, the call will be recorded and available at www.aviorwealthmn.com under the “Resources” tab the following day. 

The Markets

Bond yields are rising—and they have investors’ attention.


Last year, the United States Federal Reserve (Fed) lowered the federal funds rate by one percent. (The federal funds rate is the interest rate the Fed charges banks. It influences other interest rates.) This shift in Fed policy made a lot of people happy.


  • Companies, business owners, and consumers cheered because Fed rate cuts typically lower borrowing costs. As a result, rates on business loans, home equity loans, auto loans and credit cards tend to move lower.


  • Stock investors were enthusiastic because lower borrowing costs can reduce companies’ expenses and increase profits, and that can lift stock prices higher. Since the stock market moves in anticipation of future events, rate cut expectations are already reflected in many companies’ stock prices.


  • Prospective homebuyers were optimistic. Fixed mortgage rates are linked to the yield of the 10-year U.S. Treasury note, and they hoped it might also move lower.


Bondholders were more skeptical. Even as the Fed was cutting the federal funds rate, yields on longer maturities of U.S. government bonds were moving higher—not lower. One reason is that economic data—including last week’s strong jobs report—continue to confirm that economic growth and inflation are exceeding expectations. As a result, the Fed may be inclined toward fewer rate cuts in 2025.


“For stocks, higher bond yields imply no increase in price/earnings ratios and possibly some contraction from current levels,” reported Randall W. Forsyth of Barron’s. Changing expectations for Fed actions and company performance is likely to shift analysts’ outlook for stock market performance.


There is a second reason for the divergence in Fed actions and government bond yields, according to economist Mohamed El-Erian, a columnist for Bloomberg. He explained that key government bond yields in advanced economies “are widely regarded as the most accurate gauge of the economic outlook, including growth, inflation and central bank policies.” In his opinion, “Yield increases show that investors are closely watching whether advanced economies have the ability to deal with high debt and rising borrowing costs.” 


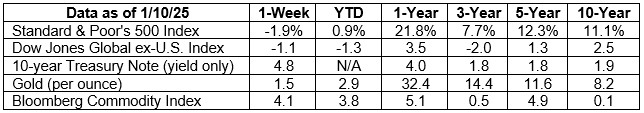
Last week, major U.S. stock indices moved lower, and yields on longer maturities of U.S. Treasuries continued to rise.

How Much Do You Know?


Last year, Pew Research asked adults across the United States how much they knew about personal finance, a topic that includes “managing your money as well as saving and investing. It encompasses budgeting, banking, insurance, mortgages, investments, and retirement, tax, and estate planning,” reported Will Kenton of Investopedia.


More than half (54 percent) of those who participated in the survey said they knew a great deal or a fair amount about personal finance. However, the results varied widely depending on the demographic attributes considered. For example, knowledge about money appears to increase with age, reported Khadijah Edwards of Pew Research Center. For example:


Ages 18 to 29:            41 percent know at least a fair amount

Ages 30 to 49:            47 percent know at least a fair amount

Ages 50 to 64:            60 percent know at least a fair amount

Ages 65 and older:     67 percent know at least a fair amount


Extrapolating that result suggests that about two-thirds of Americans may know a fair amount about personal finance as they approach retirement. Many survey participants learned what they knew about money from family and friends. Others said they relied on:


  • The internet,
  • A college or university course,
  • Media (news, documentaries, and books), and
  • Elementary or high school classes.


When asked about various issues related to finances, respondents were more confident in their ability to accomplish some tasks than others. For example, participants were confident they could:


  • Find their credit report 75 percent
  • Make a monthly budget                                59 percent
  • Develop a plan to pay off debt                      57 percent
  • Create a plan to save money                        56 percent
  • Build an investment plan to grow wealth      27 percent


If you have friends or family members who would benefit from knowing more about how to manage, save, and invest money, gifting a subscription to a personal finance publication could make a difference. You’re also welcome to share our contact information. We help people pursue their financial goals.  

thinking_girl_idea.jpg

Weekly Focus - Think About It


“Real knowledge is to know the extent of one’s ignorance.”

 —Confucius, philosopherr


Bruce Kuehl | 763.542.8884 | bruce.kuehl@avior.com

Investment management and financial planning services offered through Avior Wealth Management, LLC a registered investment advisor. Investments involve varying degrees of risk and there can be no assurance that the future performance of any investment or investment strategy will be profitable or equal past performance results. All investments subject to loss including the loss of principle. Nothing contained herein should be construed as tax advice. Specific, individual tax questions should be asked of your CPA or accountant.


Please remember to contact Avior, In writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you want to impose, add, or modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please advise us if you have not been receiving account statements (at least quarterly) from the account custodian. A copy of our current written disclosure Brochure and Form CRS (Customer Relationship Summary) discussing our advisory services and fees continues to remain available upon request or at www.aviorwealthmn.com.