Key Insights - Fed Cuts Rates, Markets Hit New Highs
-
Indexes Rally on Fed Move: U.S. stocks climbed to record highs after the Federal Reserve cut rates for the first time in nine months. Small-caps led with the Russell 2000 +2.16%, followed by the Nasdaq +2.21%, S&P 500 +1.22%, and Dow +1.05%.
-
Fed Policy Shift: The Fed lowered short-term rates by 25 bps, citing slowing job gains and downside risks to employment. Projections signaled another 50 bps in cuts by year-end and the possibility of further easing into 2026–27. Governor Stephen Miran dissented, favoring a larger 50 bps cut.
-
Trade Breakthrough: A Friday call between President Trump and President Xi yielded an agreement on U.S. ownership of TikTok and progress on broader trade talks—lifting sentiment.
Momentum Indicators Stay Bullish:
-
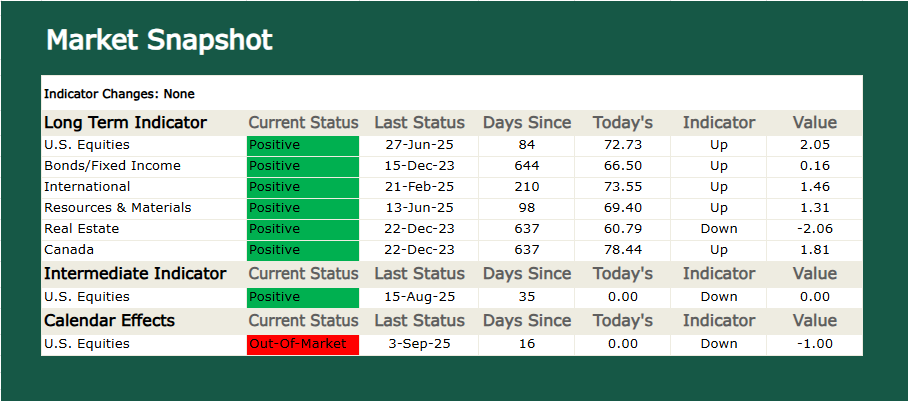
Equity DELTA-V: 72.73 (Bull) ↑ from 70.67.
-
Bond DELTA-V: 66.50 (Bull) ↑ from 66.37.
-
Short-Term Signals: Galactic Shield and Starpath remain positive; Starflux at 7.94 (slightly lower).
Volatility Dips: VIX rose 4.7% to 15.45 as investors weighed Fed easing against growth headwinds.
Here’s what else we cover in this week’s market update blog:
-
Europe: STOXX 600 dipped, with mixed results across markets. BoE left rates at 4% but slowed bond sales to reduce market pressure.
-
Japan: Nikkei +0.62%, TOPIX –0.41%; BoJ surprised markets by announcing ETF/REIT sales. Two policymakers dissented for a rate hike, signaling a more hawkish tilt.
-
China: CSI 300 –0.44%, Shanghai –1.30%; retail sales (+3.4%) and industrial output (+5.2%) both missed expectations. Persistent deflation and weak investment raised calls for more stimulus.
Visual Highlight – Rate Cuts in Historical Context: The Fed’s first 2025 cut lowers the target range to 4.00–4.25%. Projections suggest two more cuts this year, potentially bringing rates down to 3.50–3.75%. This marks another turn in the decades-long interest rate cycle, from the Volcker-era highs of 19% to the near-zero rates of the financial crisis and pandemic.
|