|
Housing at a Standstill
Greetings!
Home prices remained above year-earlier levels during the first quarter of 2026, according to the S&P CoreLogic Case-Shiller National Home Price Index. However, prices declined month-over-month for the first time in eight months. On a seasonally adjusted basis, the National Index dropped 0.2% month-over-month and was up 0.7% year-over-year, the 14th consecutive month of slowing annual price growth and the weakest appreciation since June 2023. “Monthly price movements offered a seasonal spring lift but little underlying momentum,” stated Nicholas Godec, Senior Executive at S&P Dow Jones Indices. “The latest six months saw only a negligible 0.3% rise in national home prices, barely keeping pace with the 0.3% in the prior half-year—a sign of a housing market nearly at a standstill.”
More than half of the 20 metropolitan markets tracked posted year-over-year price declines in March, with Seattle showing the steepest annual decline at 2.5%, followed by Denver (-1.95%), Tampa (-1.93%), and Dallas (-1.71%). Meanwhile, Chicago posted the largest annual price increase at 6.1%, followed by New York and Cleveland at 4% and 3%, respectively.
However, after adjusting for inflation, the nationwide monthly change declined -0.5% and the annual change fell to -2.4%. “With consumer inflation accelerating to roughly 3.3% in March, U.S. home values have now fallen in real terms for the 10th consecutive month, underscoring an ongoing erosion of inflation-adjusted housing wealth,” added Godec.
The Federal Housing Finance Agency (FHFA) House Price Index (HPI) indicates that home prices hit a new high in March, increasing by 0.1% to reach 441.6, as expected. Year-over-year, the Index has risen by 1.7%. However, after adjusting for inflation, the real HPI decreased by 1.1% month-over-month to 196.4, the lowest since May 2024. Real home prices were down 0.7% year-over-year, marking the seventh straight month of annual decline in real home prices.
It is important to remember that both the Case-Shiller and the FHFA Indexes are lagging indicators, as "March" represents a 3-month average of January, February and March closing prices, with January closing prices including some contracts signed in November. With inflation pressures and energy costs remaining elevated, future housing data could reflect additional affordability challenges.
Inflation Continues to Rise
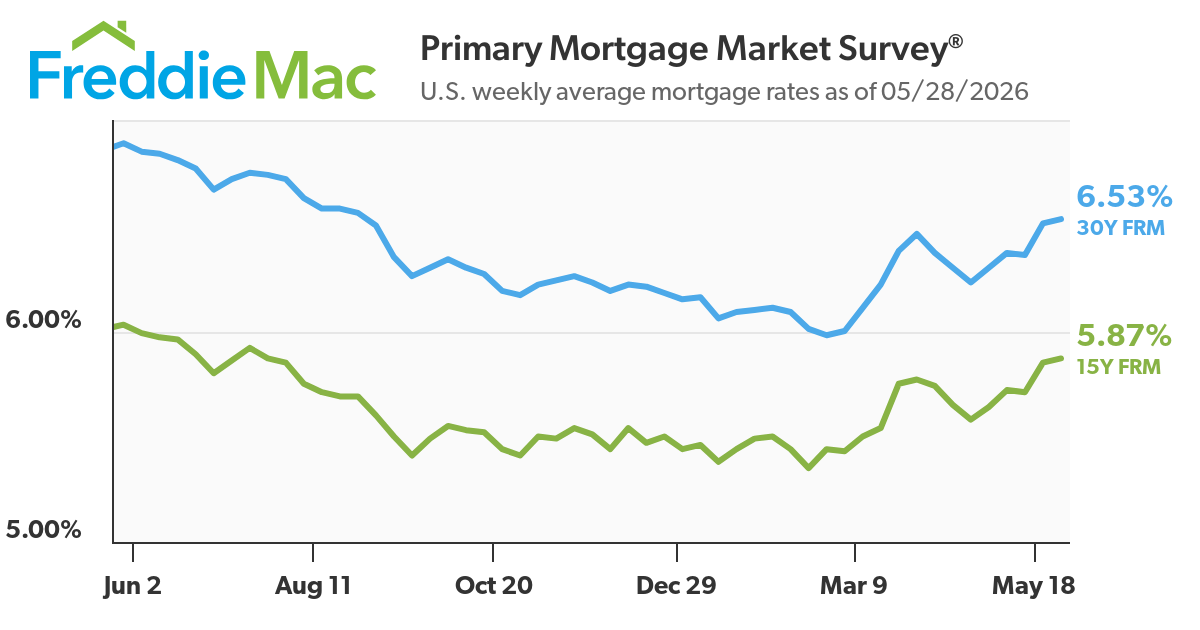
According to the Personal Consumption Expenditure (PCE) Price Index, the Federal Reserve Bank’s preferred gauge for inflation, prices rose at their fastest pace in three years in April. The PCE Index rose 3.8% compared to April 2025 and 0.4% compared to last month. The Core PCE, which eliminates the more volatile prices of food and energy, rose 0.2% month-over-month and 3.3% year-over-year, significantly reducing the chances of a rate cut at the next FOMC meeting.
If you have questions about buying, selling, refinancing, or simply understanding what these changes could mean for your home’s value or your long-term plans, we’re always here as a resource. Feel free to reach out anytime—or forward this newsletter to someone who might benefit from the insight.
|