|
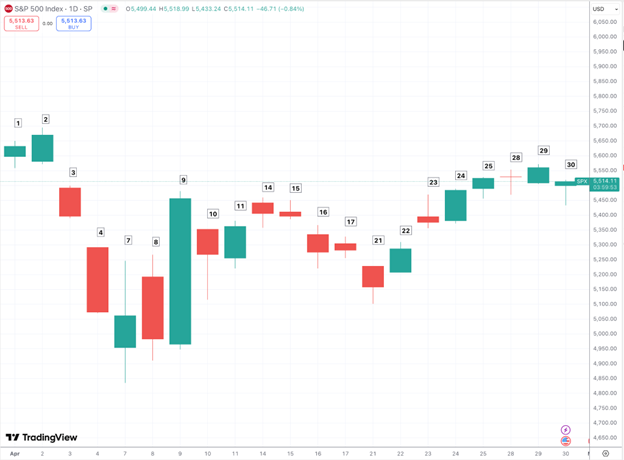
S&P 500 Index - Daily Chart - April 1-30, 2025 (Source: Tradingview)
April 1
Wall Street kicked off the second quarter with a tech-driven rally, though the broader picture was mixed. Gains in the Nasdaq and S&P 500 helped lift investor sentiment, but the Dow closed slightly lower, down 11 points, as losses in Johnson & Johnson offset broader market strength. Meanwhile, soft economic data weighed on the outlook, with U.S. manufacturing contracting in March and job openings slipping in February—signs the economy could be cooling.
April 2
Stocks started the session in the red but quickly turned around as buyers stepped in, driving a strong rebound across major indexes. The Dow rose 235 points, while the S&P 500 climbed 0.67% and the Nasdaq gained 0.75%. Tech was a mixed bag—Apple, Amazon, and Nvidia posted gains, while Alphabet, Microsoft, and Meta lagged behind.
April 3
Markets took a nosedive after President Trump unveiled sweeping new tariffs, rattling investor confidence. The Dow plunged 1,679 points, its sharpest decline in months. The S&P fell 4.84%, and the Nasdaq tumbled 5.41% as tech stocks bore the brunt of the selloff. Fears that tariffs would fuel inflation and hurt corporate profits triggered widespread liquidation across sectors.
April 4
Retaliation from China sent another shockwave through Wall Street, intensifying fears of a trade war. The Dow cratered another 2,231 points, while the S&P and Nasdaq shed 5.97% and 6.07%, respectively. With investor sentiment deteriorating, concerns of a looming recession began to take hold, sparking continued heavy selling.
April 7
Markets opened the week in disarray as traders looked for direction following last week's tariff-induced rout. The Dow swung wildly before closing down 349 points. The S&P dipped 0.23%, while the Nasdaq managed to edge out a 0.19% gain. Hope flickered as investors weighed the potential for trade negotiations to ease tensions with the White House.
April 8
An early rally quickly faded as the absence of any progress on the tariff front sent stocks sliding again. The Dow dropped 320 points, the S&P declined 1.57%, and the Nasdaq lost 1.95%. Volatility was front and center, with the S&P swinging nearly 6% intraday—a stark reminder of investor jitters.
April 9
Wall Street roared back after President Trump announced a 90-day pause on tariffs and lowered the baseline rate to 10%, excluding China. The Dow surged nearly 3,000 points, the S&P 500 soared 9.51%, and the Nasdaq rocketed up 12.02%—one of its best single-day gains in years. The move helped revive risk appetite and encouraged a burst of buying across the board.
April 10
Markets pulled back sharply as euphoria from Trump’s tariff pause began to fade. The Dow lost 1,014 points, the S&P fell 3.46%, and the Nasdaq dropped 4.19%. Concerns over lingering tariffs, weak earnings, and skepticism over trade talks reignited a wave of selling, trimming roughly half of the previous day’s gains.
April 11
Wall Street ended the week on a positive note, buoyed by strength in large-cap tech stocks. The Dow rose 619 points, the S&P climbed 1.81%, and the Nasdaq advanced 1.89%. Still, consumer sentiment remained fragile, as tariff concerns lingered in the background.
April 14
Markets treaded cautiously to start the new week, with the major indexes posting modest gains. The Dow added 312 points, the S&P rose 0.79%, and the Nasdaq gained 0.57%. Optimism stemmed from Trump’s announcement that smartphones, computers, and other key electronics would be temporarily exempt from reciprocal tariffs—though investors remained wary that the reprieve could be short-lived.
April 15
Momentum cooled on Wall Street as early gains faded into a muted finish. The Dow slipped 155 points, the S&P edged down 0.17%, while the Nasdaq closed slightly higher, up 0.18%. While volatility eased—welcomed news for jittery traders—banking earnings came in strong, offering a mixed backdrop for investors.
April 16
Stocks fell sharply after Federal Reserve Chair Jerome Powell signaled the central bank would adopt a “wait-and-see” approach to interest rates amid ongoing tariff uncertainty. The Dow slid nearly 700 points, the S&P lost 2.24%, and the Nasdaq declined 3.04%. Powell’s cautionary stance dented confidence and stirred fresh concerns about the economic outlook.
April 17
Markets struggled for direction as disappointing earnings from UnitedHealthcare and Nvidia weighed on sentiment. The Dow dropped 527 points, while the S&P managed a narrow 0.13% gain and the Nasdaq closed flat. Eli Lilly shares spiked 16% after the company unveiled a new weight loss pill, offering a bright spot in an otherwise gloomy session.
April 21
Uncertainty gripped Wall Street again as investors grappled with mixed signals and few catalysts. The Dow sank 970 points, while the S&P and Nasdaq lost 2.36% and 2.46%, respectively. President Trump’s renewed attacks on Fed Chair Powell and a sharp drop in the U.S. dollar to a three-year low deepened market anxieties.
April 22
A wave of optimism lifted stocks as investors seized on positive earnings and a market ripe for a rebound. The Dow rallied 1,016 points, the S&P jumped 2.51%, and the Nasdaq climbed 2.63%. Every stock in the Dow ended in the green, with 3M leading the way after issuing guidance that met expectations—though the company cautioned on tariff-related headwinds.
April 23
Tensions between Trump and Powell eased, helping stocks to notch another day of solid gains. The Dow advanced 419 points, the S&P added 1.67%, and the Nasdaq surged 2.28%. A shift in tone from Tesla CEO Elon Musk—vowing to focus on business over politics—further boosted sentiment and lifted Tesla shares.
April 24
Markets extended their winning streak to three days as trade tensions appeared to cool. The Dow gained 486 points, the S&P rose 2.03%, and the Nasdaq added 2.79%. While no formal trade deal has been reached, officials signaled a growing willingness to engage in negotiations—enough to keep the bulls in charge.
April 25
Stocks capped off the week on a steady note, continuing to recover losses from earlier in the month. The Dow inched up 20 points, the S&P climbed 0.74%, and the Nasdaq added 1.14%. With the market in oversold territory and talk of de-escalation swirling, investor confidence appeared to be on the mend.
April 28
Wall Street edged higher in a quiet session, as the absence of negative headlines gave bulls some breathing room. The Dow gained 114 points, the S&P ticked up 0.06%, and the Nasdaq slipped a modest 0.03%. Breadth remained positive, with more stocks rising than falling, as investors welcomed the relative calm.
April 29
Stocks got a modest lift from potential trade deal hints that would blunt the impact of Trump’s tariff policies in time to maintain a decent economy. Although markets are now up 15% from their April low, this rise comes against another batch of negative consumer confidence data.
April 30
Stocks pulled back following a surprise contraction in first-quarter GDP. The Dow fell 281 points, or 0.7%, while the S&P 500 dropped 1% and the Nasdaq lost 1.4%. The economy shrank at a 0.3% annualized rate, reversing Q4’s 2.4% growth, with economists citing a 41% surge in imports—companies rushing to front-run Trump’s tariffs—as a key distortion. However, the report also revealed weakening consumer spending and a drop in government outlays tied to Elon Musk’s DOGE-related budget cuts.
|