January 9 , 2025


Mortgage Rates Back in The 5's. Here's Why

⚡TL;DR — Quick Takeaways:


Mortgage Rates: National averages have dropped to a two-year low of 5.99%. Weak employment data has further pushed prime borrower rates into the 5.5% range.


Institutional Investor Ban: A proposed federal ban targets corporations with over $500 million in assets to prevent them from buying single-family homes. The move is designed to protect individual homeownership and affordability.


2026 Purchase Strategy: January is currently the most affordable month to buy, with prices significantly lower than the spring peak. Buyers are increasingly using ARMs and shared appreciation loans to secure housing.


Income Qualification: The 1099-Only program qualifies borrowers using 90% of gross income. This method bypasses tax write-offs and net losses that typically disqualify self-employed earners.


Financing Flexibility: Primary residence purchases allow for as little as 10% down with a 660+ FICO. The program supports 1–4 unit properties and non-warrantable condos without requiring any tax returns.

🗓️ Click here to view the full economic calendar 

Welcome back, everyone. I hope you all had a great holiday season and a chance to unplug, reset, and think about what you want this year to look like. It always feels like all the markets of the world ease into December... and then January hits, and we’re right back into it into new breaking headlines and economic data!


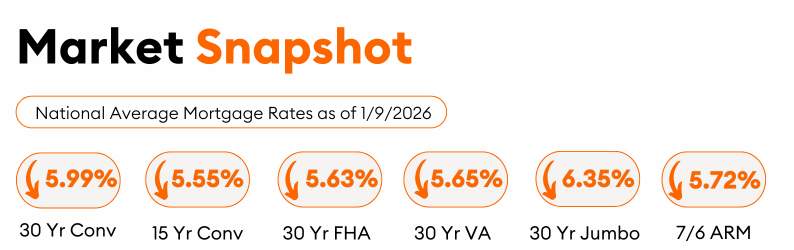
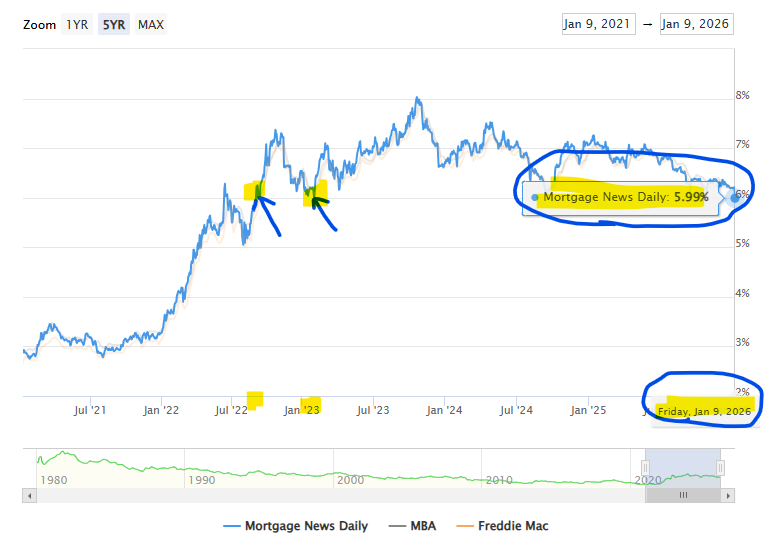
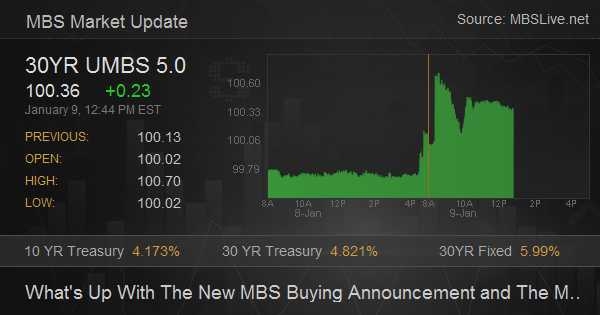
Mortgage rates are currently sitting at a national average of 5.99% (Mortgage News Daily). This is the lowest level since early 2023. For prime borrowers, rates are now landing in the 5.5% range.


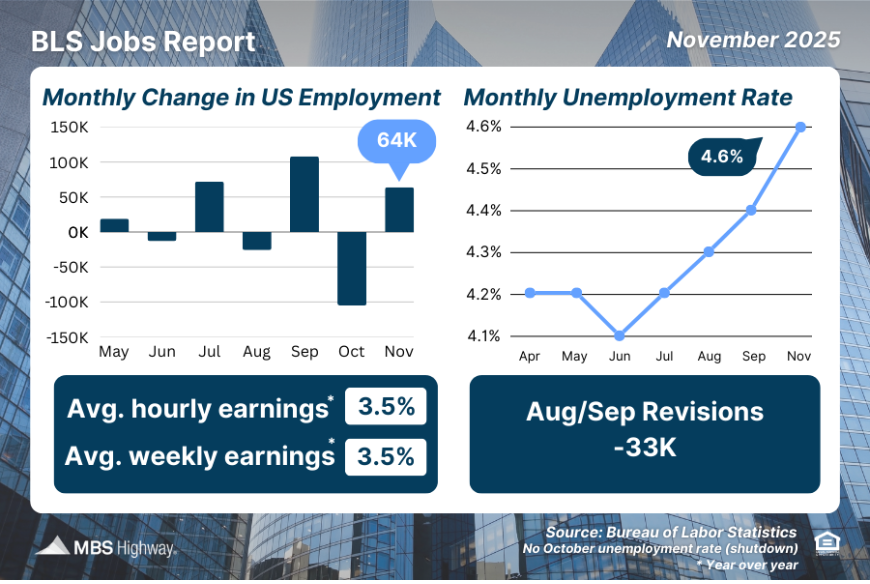
What’s interesting is that today’s jobs report didn’t come in weak enough to normally spark a rally in bonds, yet rates still moved lower. That points to a bigger theme at play: the market is reacting to a shift in the liquidity cycle, including renewed discussions around Fannie Mae’s capacity to support the market by purchasing up to $200 billion in mortgage-backed securities. This added demand helps support rates at a level meaningful to both buyers and homeowners. It is a very positive backdrop for the start of the year. There is also a lot of


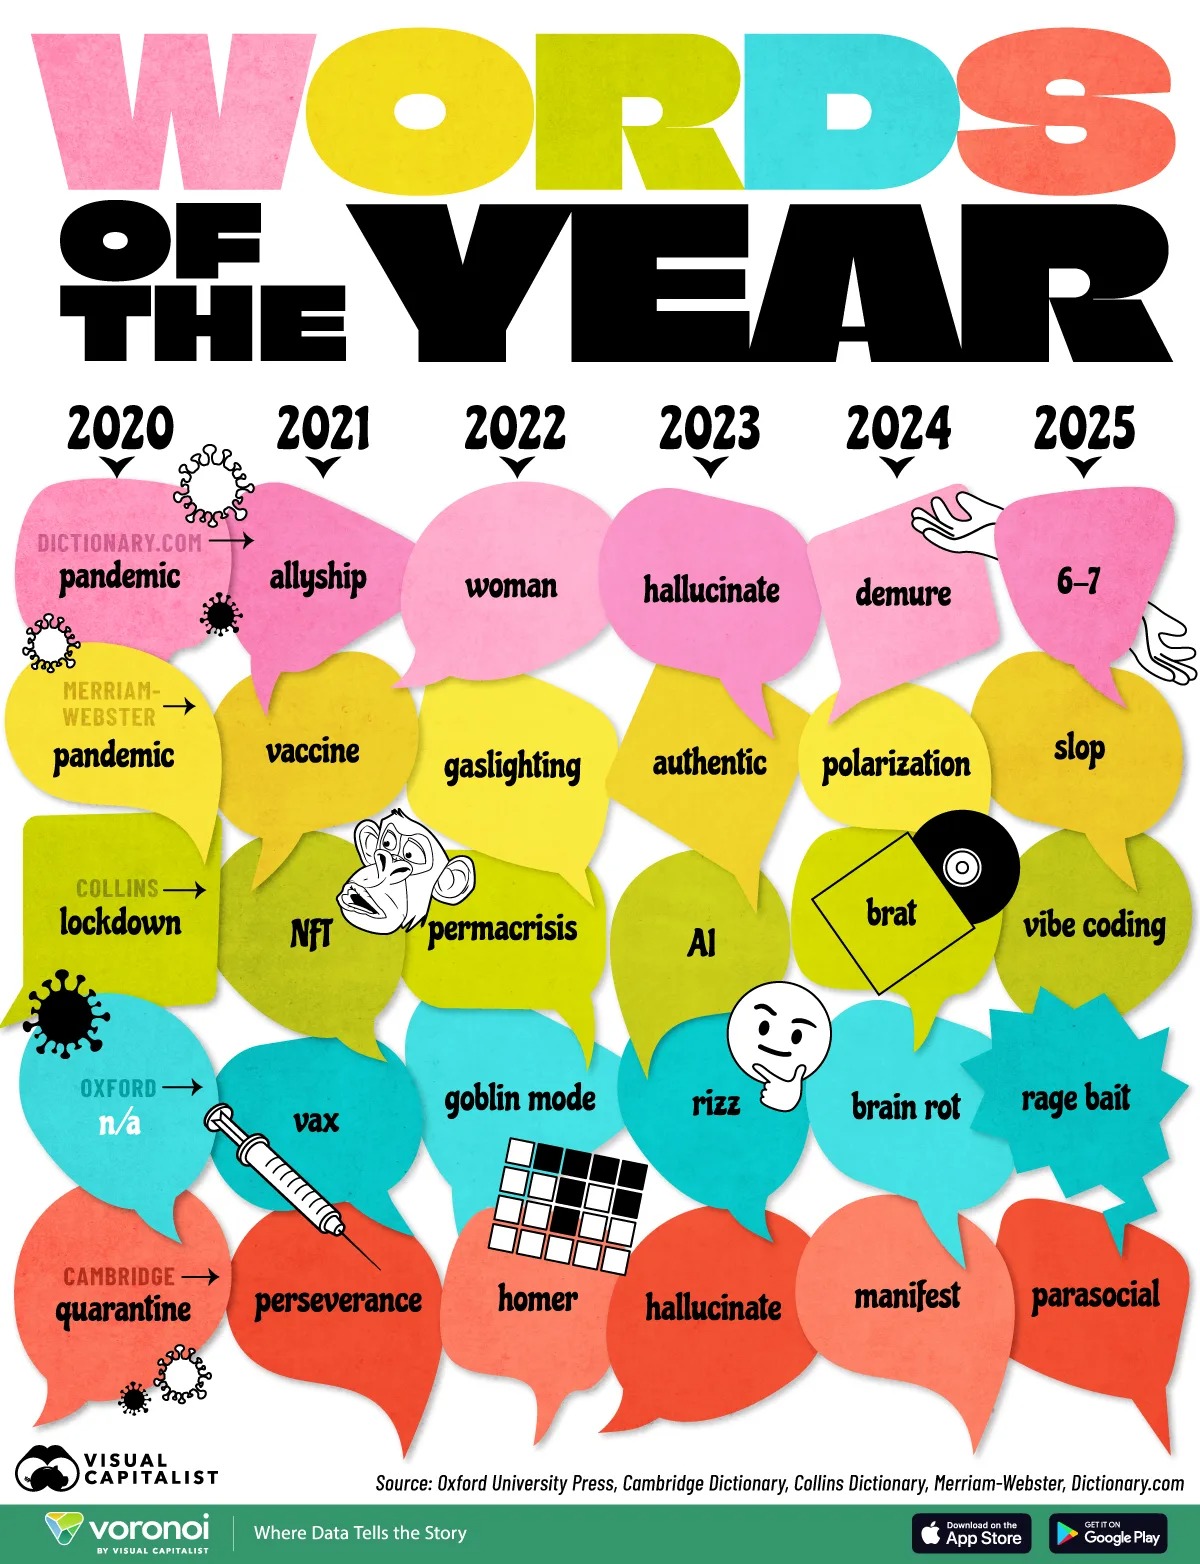
Word of the Year

With all that noise, I am focusing on a single word for 2026: Presence.

I am prioritizing intention over distraction and presence over performance. It is a simple philosophy that works. I look forward to bringing that focus to our partnership this year.

📉 Rates: Stability Amid Economic Softness


Mortgage rates are showing a surprising resilience and are currently hovering near their lowest levels in over two years.


Why?

  • The national 30 year fixed rate average is sitting at approximately 5.99%.
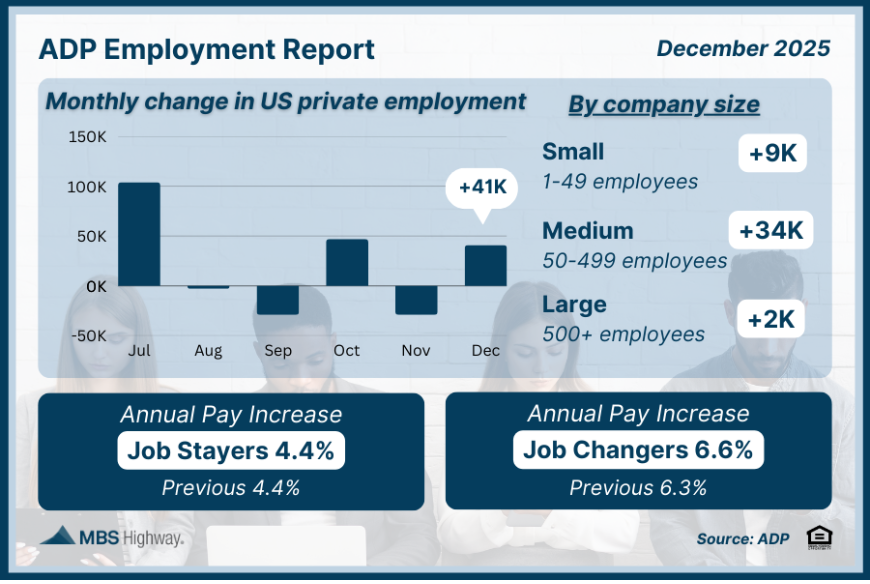
  • Weak ADP employment data recently pushed long term bond yields lower which directly benefits mortgage pricing.
  • Markets are reacting more to labor market cooling than to direct Federal Reserve actions.

🏛️ Market Support: The Institutional Investor Ban


The administration is moving to bar large corporations from purchasing single-family homes to protect the American Dream.


Key Drivers

  • The proposed ban targets companies with assets under management of 500 million dollars or more.
  • While institutional investors own less than 2 percent of single family homes nationwide, the move is a symbolic effort to address affordability.
  • Experts are divided on the impact because these investors often rehabilitate properties that they eventually offload back to individual buyers.

🥂 2026 Strategy: Creative Paths to Ownership


Buyers and investors are adapting to the current environment by using sophisticated financial tools and intentional planning.


The Strategy

  • Investors are leveraging permanent 100 percent bonus depreciation and cost segregation to maximize cash flow.
  • First-time buyers are increasingly utilizing ARMs and state programs like the California Dream For All shared appreciation loan.
  • January remains the least expensive month to purchase a home with prices often thousands of dollars lower than the spring peak.

Quote to Ponder


"Be not afraid of growing slowly; be afraid only of standing still."


 - Chinese Proverb

Featured Financing Solution

1099-Only Advantage: Qualifying Income Without Tax Returns


✅ Qualify on Gross, Not Net: Qualifies borrowers using 90% of gross 1099 earnings, bypassing tax write-offs and net losses.


✅ Low Down Payment Entry: Supports up to 90% LTV for primary residences with a 660+ FICO score.


✅ Versatile Property Options: Covers 1–4 unit properties, townhomes, and non-warrantable condos for primary or investment use.


✅ Simple, Fast Documentation: No tax returns required—just last year’s 1099s and proof of current year-to-date earnings.


Important Reports

Recent Real Estate and Economic News

What's Up With The New MBS Buying Announcement and The Massive Reaction in The Market?

On Thursday afternoon with less than an hour left to trade, Trump announced he would be directing his representatives to buy $200bln in mortgage-backed securities (MBS). No matter what one's personal ...

Trump's proposed ban on large investors draws a predictably divided response

Some analysts say it could help buyers - but others believe it's the wrong approach

Rates plummet into 5s after Trump orders Fannie and Freddie to buy mortgage bonds

30-year rates dropped into the high 5s before rebounding late

Links Worth Saving

📈 Track National Mortgage Rates Real Time

💹 CPI Inflation Calculator

🧮 Mortgage Calculator

📜 Seller Concession Cheat Sheet

🏦 FHA Loan Limits for 2025

🏠 Conventional Loan Limits for 2025

🔍Corelogic Intelligence Insights


Joe Jacobs

Mortgage Broker/Owner

1101 College Ave, Ste 215

Santa Rosa, CA 95404

(707) 696 6937

joe@intentionfinancial.net

NMLS 453314


X Share This Email
LinkedIn Share This Email