|
|
Facing Your Financial Fears: join us in Oct
By Gray
Financial education is one of the things we care most about as a firm. It's a big part of why we write this newsletter, and it's why we're presenting "Facing Your Financial Fears," a free four-part series with The Charlotte Ledger that starts next week. In this case, we're putting our money where our mouth is, as the series' presenting sponsor. Caroline and I will be part of the conversations.
These are candid conversations about money and the decisions most of us are quietly trying to figure out. No jargon-heavy presentations, no pretending everyone's financial life follows the same neat roadmap, and no requirement that you already know what a Roth conversion is. Each Wednesday in October (the 7th, 14th, 21st and 28th), we take on the money questions that show up at different stages of life, from first paychecks and student loans to buying a house, raising kids, helping aging parents, and deciding what happens to everything you've worked so hard to build.
Each night has a generational focus, but you don't have to belong to that generation to come. Show up for the one that fits what you're facing right now, or come to all four, and bring your spouse, your parents, your adult kids, or the friend who texts you every time there's a money decision to make. All four are at the Mint Museum, but at two different locations: October 7 and 14 are at Mint Museum Uptown, and October 21 and 28 are at Mint Museum Randolph. Doors open at 5:30 with beer and wine, the conversation starts at 6, and when you register you can send in the question you'd most like the panel to tackle.
It's free, but you do need to register. Save your seat here.
| |
Tax Loss Harvesting
By Gray
Bull markets are great. But they come with the occasional tax headache. If you buy a stock at $100, it grows to $130 and you sell it, you owe capital gains taxes on the $30 of gains. That's absurd, you say. Is there no way to offset this taxable gain, you ask? Perhaps tax loss harvesting can help.
In the example above, you're sitting on a $30 gain headed into year-end. You comb through your portfolio and notice that dog we recommended (hypothetically, of course). We paid $85 per share for that particular investment, and today it's only worth $74. We could sell it for the express purpose of harvesting the $11 loss. You can offset your $30 gain with that $11 loss, and now you only owe taxes on $19 worth of capital gains. Like anything, there are some rules and nuance (the wash-sale rule, for one, says you can't buy the same investment back within 30 days of the sale).
But now is the time to think about year-end tax strategies like this. We even came up with a list of questions to ask your accountant between now and December 31. Let us know if you find it helpful.
| |
The Boring Section
Unlike a Traditional IRA, a Roth IRA has no required minimum distribution for the original owner. Ever. The money can sit and compound for the rest of your life if you don't need it. Boring
| |
Compute: A new asset class?
By Caroline
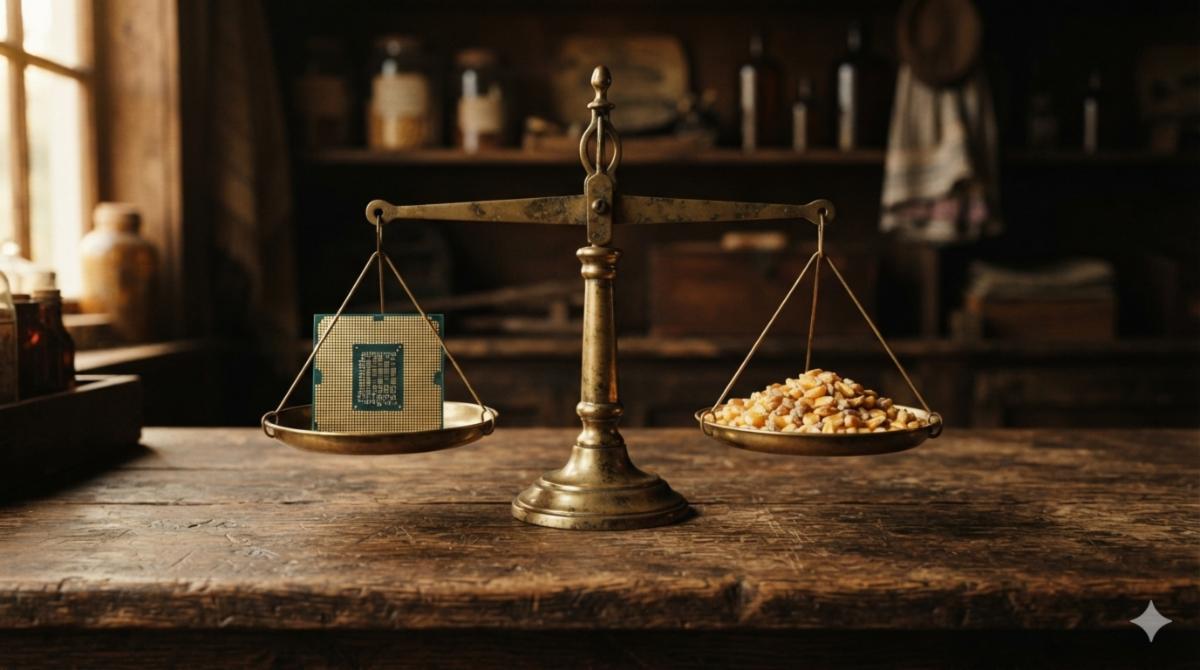
Every AI tool you've used, from chatbots to image generators, runs on specialized computer chips doing enormous amounts of math, all day, in giant warehouses called data centers. That processing power is called "compute." For years it was just a cost of doing business, the same way a factory pays for electricity. That's starting to change. These chips have become scarce, and their price has become volatile, which is the same thing we saw happen to oil, turning it into something people invest in, not just burn.
A clear sign that compute may be following oil's path toward becoming an asset class came this spring, when a firm called FalconX completed the first trade where two parties bet on which direction the price of renting one of these chips would move. It's the same basic idea as a farmer locking in this year's corn price ahead of harvest. A real financial market for buying and selling access to computing power now exists.
It has since gone a step further. In August, Nvidia teamed up with some of the biggest names in investing, Apollo, Blackstone, Brookfield, KKR, BlackRock and Goldman Sachs, to raise more than $500 billion to finance the data centers that run AI. Several of these firms are better known for owning office buildings and toll roads. Now they're betting that renting out computing power can be as reliably profitable as renting out real estate.
Whether this becomes a lasting new corner of the investment world, or turns out to be a passing trend, is genuinely up for debate. What's clear is that something previously invisible, the computer processing behind your everyday AI tools, has become valuable enough that Wall Street's biggest names are racing to own a piece of it.
| |
Market Update
By Caroline
The big news this month is that the Fed finally moved. On September 16 the Federal Open Market Committee raised its benchmark rate by a quarter point to a range of 3.75% to 4%, its first increase since 2023. The Fed also signaled it is not done. Its updated projections point to at least one more increase before year-end, and as of this writing, markets put the odds of another hike at the next meeting in late October at roughly two in three. After holding steady all year, this marks a real shift in posture from a central bank that now sees inflation as the problem it most needs to address.
Inflation is what drove the decision. August's CPI, released September 11, rose 0.4% for the month and held at 3.4% annually, with higher gasoline prices a major factor. Core inflation, which strips out food and energy, came in at 2.4%, its lowest reading since early 2021, but the headline number stalling well above the Fed's 2% goal, along with a firmer-than-expected monthly core reading, was enough to tip the committee toward action.
Markets had largely priced the hike in, so the bigger story since has been the bond market. Treasury yields have climbed sharply, with the 10-year note reaching about 5.25%, its highest since 2007, and the 30-year pushing to roughly 5.55%, a level last seen in 2004. Sticky inflation, the Fed's turn toward tightening, and still-elevated oil prices have all pushed in the same direction. Stocks have been choppy through the back half of the month, and a selloff to start this week has left the S&P 500 about 2% below the record high it reached in August, as of this writing.
A first rate hike in three years and yields at levels not seen in nearly two decades make for unsettling headlines, but higher rates are not inherently bad news. They mean more income from bonds and cash than savers have seen in a long time. What matters is not reacting to any single Fed meeting. As always, we are here if you want to talk through what any of it means for you.
| |
A word on AI, Schwab, and you
By Gray
You may have seen the news: Charles Schwab and Anthropic have teamed up to bring an AI tool called Claude for Financial Advisors to independent advisors like us. Since Schwab is our custodian, I want to get ahead of a question some of you may already be asking: what does this mean for my money, and for my privacy?.
The short version: nothing changes. We're unlikely to use the tool at all. Only Anthropic's Enterprise plan offers the audit and compliance controls we'd want to see before we'd even consider it, and Enterprise requires at least 20 users. (We wonder how many firms our size are positioned to use these tools in the first place. Remind me to ask Claude.)
We do have a Claude Team account, but our strict AI policy forbids us from sharing any of your personally identifiable information (PII) with a large language model like Claude or ChatGPT.
We're always happy to talk through any of this.
| |
The Hidden Cost of Little Luxuries and why it might be worth it (or not)
By Caroline
For many people, the highlight of their morning routine is a cup of coffee from their favorite coffee shop. For some families, ordering dinner every week is a great way to share time together without needing to cook or get dressed up to go out.
Small luxuries like daily coffee stops and weekly Uber Eats can be costly, but they often hold value beyond just the item itself.
If you were to buy a $7 coffee 300 days a year, that is $2,100 extra that could be invested annually. If you invested that amount for 20 years, your savings would grow to around $86,000, assuming a 7% return. Similarly, a family of four that orders Uber Eats once a week spends roughly $25–40 more each week than it would dining in at the same restaurant. By going out instead of ordering in, that family could invest an extra $1,300–$2,000 a year, which could grow to $53,000–$82,000 in 20 years with a 7% return.
None of this is an argument for giving up your coffee or your Friday order-in. A little luxury earns its cost when you can actually feel it. The purchases worth a second look are the ones you've stopped noticing, because a habit you don't even register isn't buying you anything at all.
| |
Book Club Update
By Caroline
We mentioned last month that our book club was working through The Psychology of Money by Morgan Housel. Over Labor Day weekend, someone in my family, unprompted and with no idea we'd been reading it, told me it was one of the best books she'd read all year. Small world, or maybe just a sign the book travels well beyond the finance crowd. It's a quick read, and one of the few in the genre that holds up outside a boardroom. If you haven't picked it up, consider this an extra nudge. We even have free copies here we will give you.
| That's September. We'll be at the Mint every Wednesday night in October (Uptown for the first two, Randolph for the last two), so if there's a question you've been meaning to ask us in person, now's your chance. Stay after for a free walk through the museum while you're there. Otherwise, you know where to find us. | |
Thank you for reading. If you liked this content, please share with a friend. You can always reach us by replying to this email or at 704-323-6872.
The foregoing content reflects the opinions of Dyer & Co. and is subject to change at any
time without notice. Content provided herein is for informational purposes only and should
not be used or construed as investment advice or a recommendation regarding the
purchase or sale of any security. There is no guarantee that the statements, opinions or
forecasts provided herein will prove to be correct.
Past performance may not be indicative of future results. Indices are not available for direct
investment. Any investor who attempts to mimic the performance of an index would incur
fees and expenses which would reduce returns.
Securities investing involves risk, including the potential for loss of principal. There is no
assurance that any investment plan or strategy will be successful.
|
| | | |