There was a shift in the winds of monetary policy.
Last week, it became clear the Federal Reserve (Fed) had softened its hawkish stance. The minutes of the central bank’s November policy meeting indicated the Fed was likely to slow the pace of rate hikes soon. There was a caveat, though. The minutes noted:
“…with inflation showing little sign thus far of abating, and with supply and demand imbalances in the economy persisting…the ultimate level of the federal funds rate that would be necessary to achieve the Committee’s goals was somewhat higher than [Fed officials] had previously expected.”
In other words, rate hikes are likely to be smaller in the future, but the federal funds rate will probably move higher than previously expected. Last week, the CME FedWatch Tool suggested that the federal funds target range will:
- Increase 0.50 percent in December to 4.25 to 4.50 percent.
- Rise to 5.0 percent to 5.25 percent during 2023.
- Fall to 4.5 percent to 4.75 percent by the end of next year.
Weaker economic data seemed to support the Fed’s pivot. Molly Smith of Bloomberg reported, “Fresh evidence Wednesday pointed to a slowing U.S. economy and a cooling labor market that suggests steep interest-rate hikes by the Federal Reserve are starting to have a broader impact. Business activity contracted for a fifth month in November and applications for unemployment benefits rose last week to a three-month high. While consumer sentiment and new-home sales improved, both remain depressed and indicate a weaker spending appetite and subdued housing demand.”
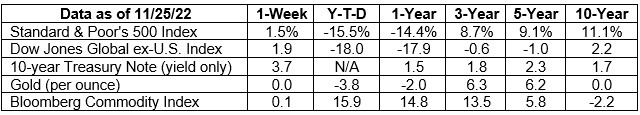
Investors celebrated the Fed’s stance adjustment, and major U.S. stock indices pushed higher last week. Yields on U.S. Treasuries with maturities of one year or less moved higher last week, while yields on longer maturities moved lower.