RBGWA - Logo - Full Color.png
 

RBG Wealth Weekly

March 24, 2023


Ladies and gentlemen, the weekend! In this space each week, Greg and I share some of our favorite articles, notes, and graphics from the past week along with our commentary. Please feel free to provide feedback and forward along to others if you enjoy. We appreciate you taking the time to read. 


If you are a client, we truly appreciate your business. If you are not a client, please click below to learn more about our firm and contact us.

Visit our Website
 

On-Demand Webinar

Securing Your Retirement: Exploring the Benefits of the SECURE Act 2.0


In its first iteration in 2019, the SECURE Act, or Setting Every Community Up for Retirement Enhancement, set the stage for substantial changes to the way Americans save for their post-career lives. The “sequel” of sorts that was passed late last year, known as SECURE Act 2.0, will impact just about everybody. With more than 90 provisions in the Act, it will have a sweeping effect on retirement savers.


More flexibility and time are among the benefits across the board in investors’ favor as they prepare for retirement. But the Act’s provisions, many of which will go into effect rather quickly, are worth discussing with your financial advisor as soon as possible, to ensure that you can maximize the benefits according to your specific circumstances.

Download the Slide Deck
 

Articles of the Week

Another Fed Rate Hike Keeps Policy Modestly Tight


“[Wednesday’s 0.25%] rate hike by the Federal Reserve was expected, although there’s debate about whether another round of policy tightening is wise in the wake of recent bank turmoil following the collapse of Silicon Valley Bank (SVB).


Fed Chair Jerome Powell partly rationalized the hike by saying that SVB’s implosion was an 'outlier' while the banking system overall remains 'sound.' At a press conference following Wednesday’s rate increase announcement he told reporters: 'This was a bank that was an outlier,' advising that the combination of a high percentage of uninsured depositors (accounts above $250,000) and mismanaging the bank’s duration risk felled SVB. ‘These are not weaknesses that are there at all broadly through the banking system.’…


A new set of economic projections published by the Fed yesterday – the so-called dot plot — point to interest rates peaking at 5.1% this year, which implies one more rate hike.


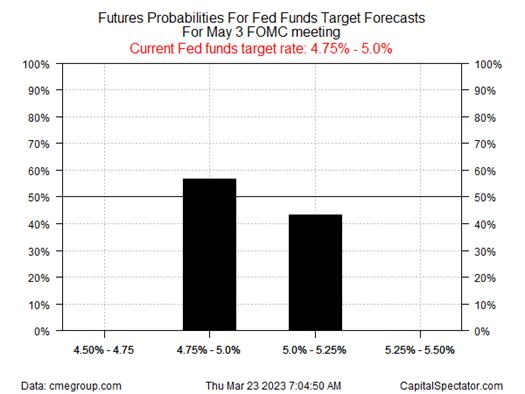
Fed funds futures, however, are currently estimating a mixed outlook for the next FOMC meeting on May 3. The implied probabilities for the rate outlook are more or less a tossup between putting rate hikes on pause vs. another ¼-point increase.

Even without additional rate hikes Powell advised that the bank turmoil of late will create new headwinds for the economy. In effect, the SVB-related blowback is a defacto rate hike, he suggested, explaining:


‘Financial conditions seem to have tightened, and probably by more than the traditional indexes say. … The question for us though is how significant will that be — what will be the extent of it, and what will be the duration of it. We’ll be looking to see how serious is this and does it look like it’s going to be sustained. And if it is, it could easily have a significant macroeconomic effect, and we would factor that into our policy decisions.'"


The Fed stayed on course with another 0.25% fed funds rate hike. Had it not been for the banking turmoil over the last two weeks, it would have been 0.50%. But, it’s still remarkable when you consider that they just had to create a new Bank Term Funding Program for bank liquidity as a consequence of their tightening policies.


The language in the FOMC statement changed from “ongoing increases” to “policy firming may be appropriate”, which gives them wiggle room to cease any further rate hikes. That would be nice.

How the Swiss ‘trinity’ forced UBS to save Credit Suisse


“'For the biggest investor to say I’m not putting another dime in was a huge vote of non-confidence. I could argue that had he not said anything we might have been in a very different situation,' says a person close to Credit Suisse’s top management.


On Wednesday, the so-called “trinity” of the Swiss National Bank, regulator Finma and the minister of finance summoned Credit Suisse chair Axel Lehmann, who was in Saudi Arabia for a conference, and chief executive Ulrich Körner for a call.


In the same meeting where they authorized a SFr50bn [($54bn) liquidity backstop from the Swiss central bank], they also delivered another message: ‘You will merge with UBS and announce Sunday evening before Asia opens. This is not optional,’ a person briefed on the conversation recalls.


[UBS Chairman Colm] Kelleher found out his weekend plans were ruined on Thursday afternoon. The trinity called UBS and ordered the group to find a solution to save its ailing peer from bankruptcy.


‘Resolution [a government-controlled wind-down] would have been a disaster for the financial system and introduced the threat of contagion around the world,’ says another person involved on the UBS side. ‘Our interests were also aligned because a failure is not good for the Swiss wealth-management brand. So we said, on the right terms, we would help.’


The takeover of its local rival could end up being a once-in-a-generation boon for UBS. But in exchange for taking on a bank wracked with litigation issues and billions of toxic assets, UBS was determined to extract the best deal that it could.”


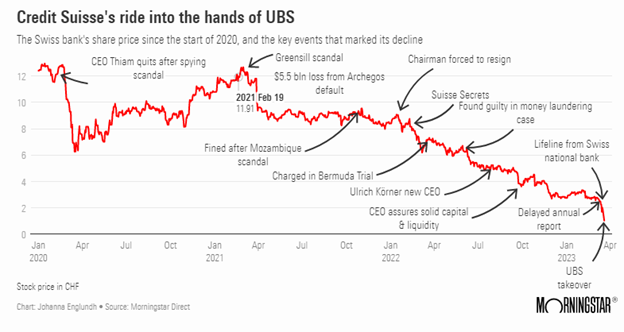
Credit Suisse has been on a slow death march since 2011 that only accelerated over the last 3 years until the forced buyout by rival UBS this past weekend. Internal spying operations on its own executives, the Bill Hwang family office blowup, fines for bribery in Mozambique, other scandals, and accounting issues never allowed the bank to fully recover from the Great Financial Crisis. The 166-year-old bank will fold into UBS before year-end.

Read More
 

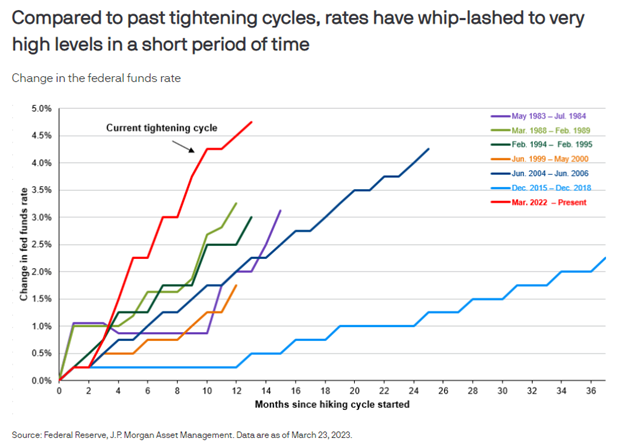
Graph of the Week

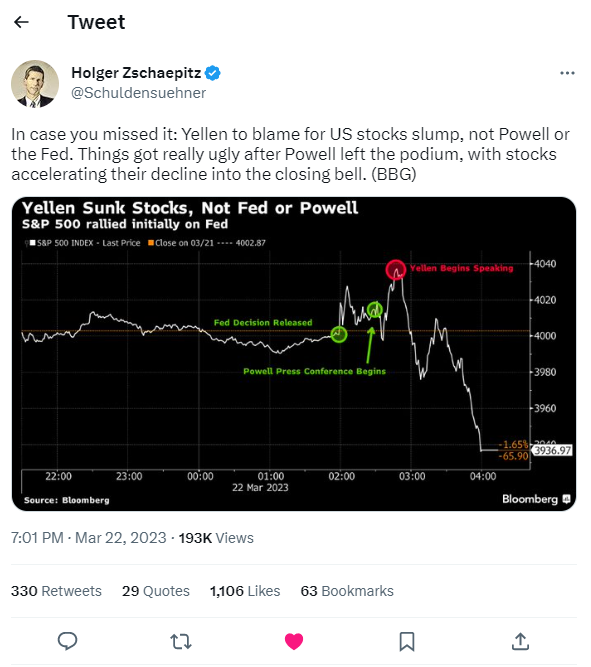
Tweet of the Week

Thanks for reading. Have a great weekend!


Guidance for today. Growth for tomorrow.


RBGWA - Logo - Full Color.jpg

Tim Ellis, CPA/PFS, CFP®

CIO and Wealth Advisor

RBG Wealth Advisors

M: 901.682.2431 | C: 662.444.1415

E:  tellis@rbgwa.com

A:  5100 Wheelis Dr., Ste. 300, Memphis, TN 38117

W: rbgwa.com

LinkedIn  Twitter  Facebook

RBG Wealth Advisors LLC is a registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Investments involve risk and, unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Past performance is not indicative of future performance.