RBGWA - Logo - Full Color.png
 

RBG Wealth Weekly

May 5, 2023


Ladies and gentlemen, the weekend! In this space each week, Greg and I share some of our favorite articles, notes, and graphics from the past week along with our commentary. Please feel free to provide feedback and forward along to others if you enjoy. We appreciate you taking the time to read. 


If you are a client, we truly appreciate your business. If you are not a client, please click below to learn more about our firm and contact us.

Visit our Website
 

Articles of the Week

Markets Consider a Path for Fed Pause and Cut on Rates


“The Federal Reserve raised interest rates for a 10th straight time on Wednesday, lifting its target by a ¼-point to a 5.0%-to-5.25% range, the highest since 2007. But there are hints that the central bank may be set to pause at the next policy meeting in June and start cutting later in the year. Much depends on how the economic and inflation data compare in the updates during the weeks and months ahead. But for now, the crowd thinks the rate-hiking cycle may have peaked.


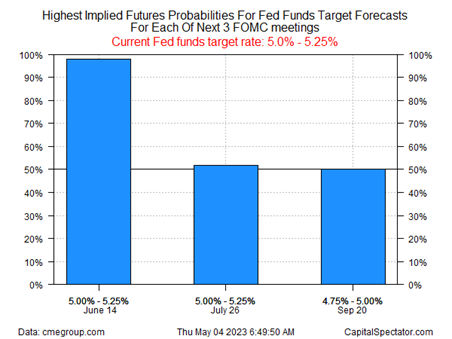
Consider the outlook via Fed funds futures this morning. A pause is currently priced in as a near certainty at the June 14 meeting, based on CME data. Another pause and a cut are expected to be the most likely scenarios at the two FOMC meetings that follow, although in those cases the implied probabilities are roughly a coin toss at this point.

The two-year Treasury yield, considered the most policy-sensitive rate, continues to trade well below the Fed funds rate, offering another market-based forecast that the central bank will soon pause and then cut.


Officially, the Fed is taking a wait-and-see position. Answering a question at yesterday’s press conference on whether the policy statement indicates a pause is likely at the June FOMC meeting, Fed Chair Jerome Powell said: ‘That’s a meaningful change that we’re no longer saying that we ‘anticipate’. So we’ll be driven by incoming data, meeting by meeting, and we’ll approach that question at the June meeting.’”


Another 0.25% increase in rates had been priced in for a while; however, First Republic Bank's failure on Monday gave the Fed an opportunity to put the weapon down and back away. They didn’t.


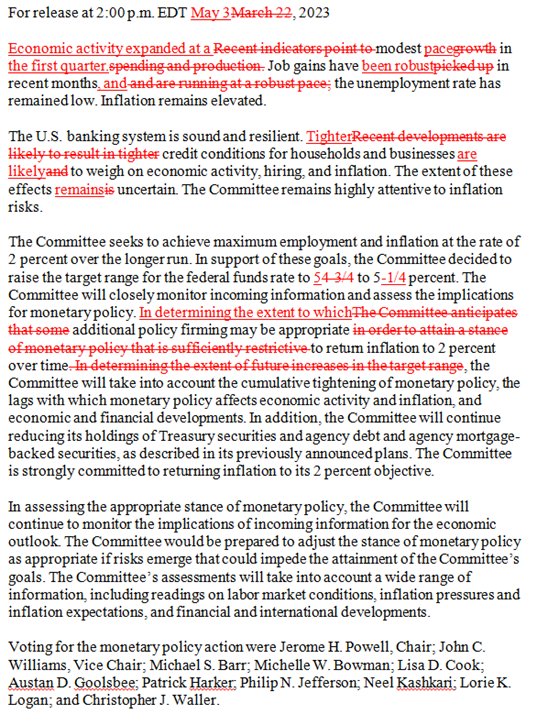
On the optimistic side, the language in the release hints that this may be the last rate increase, and Powell reiterated that in his press conference. You can see the updates from March to May in red below. The focus is on the removal of “The committee anticipates that some additional policy firming”.


TD Bank Scraps Purchase of First Horizon Amid Regional Bank Crisis


“When TD Bank (TD) announced the deal in February 2022, the Canadian bank said it would pay First Horizon shareholders $25 for each common share of First Horizon outstanding in an all-cash transaction. It was mainly a play to add hundreds of branches in the Southern U.S.


But a lot has changed since then. The Federal Reserve has hiked rates at a fast clip, rendering long-term loans issued at lower rates less valuable while also prompting many depositors to take advantage of higher yielding opportunities outside of bank savings accounts. In recent weeks, several regional banks have collapsed, most notably First Republic Bank. The SPDR S&P Regional Banking ETF (KRE) is down 35% this year.


TD didn’t reference the industry woes in calling off the deal, explaining only that it did not have a timetable for necessary regulatory approvals for reasons unrelated to First Horizon…


Analysts at Jefferies said in a May 4 research note that the TD announcement “implies the regulatory hangup is on the TD side.”


As part of the termination of the agreement, the company will make a $200 million cash payment to First Horizon. TD said it will also pay a $25 million reimbursement fee to First Horizon pursuant to the merger agreement…


The bank had deposits of $62.2 billion at the end of the first quarter, down $2.7 billion, or 4%, from the fourth quarter of 2022, according to the company. Other regional banks also reported deposit declines during the quarter. First Horizon said 63% of its deposits were secured or collateralized. Over a third of its deposits, 38%, were in Tennessee. Another 19% were in Florida…


Economic uncertainty is weighing on M&A deal making activity, according to a new report from S&P Global Market Intelligence. The value of global first-quarter M&A plummeted 45% year-over-year to $428.38 billion, according to S&P. That’s 62% lower than the first quarter of 2021 when M&A activity topped $1 trillion.”


Memphis-based First Horizon’s takeover deal with TD Bank fell through this week. Regulatory issues had strung out the acquisition since its February 2022 announcement. That regulatory uncertainty combined with bank industry turmoil and a reduced appetite for large-scale M&A ultimately led to a break with TD paying a sizable breakup fee to FHN.


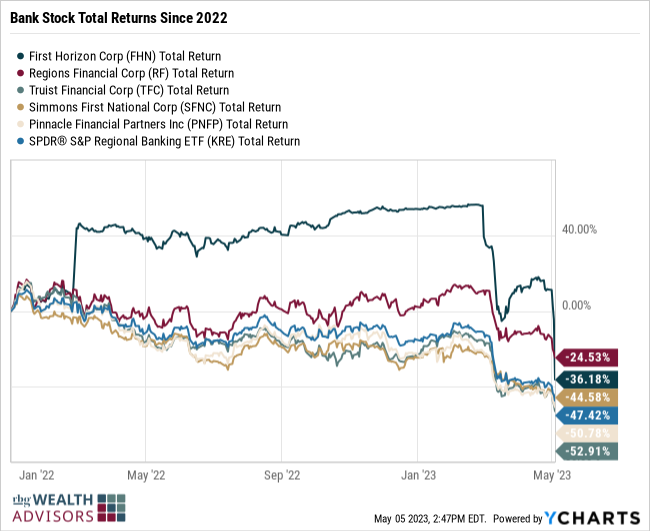
Since mid-March, First Horizon’s stock price had been trading between $15 - $18, well below the $25 announced deal price. Regional banks have been repriced across the board due to falling deposits and anticipated pressures from the economic cycle and commercial real estate loans. Even after the deal termination fallout, First Horizon’s performance is still in line with regional lenders since the start of 2022.

April 2023 Market Summary


“April was another positive month for stocks, with the exception of the small-cap Russell 2000 index. The Dow Jones Industrial Average rose 2.6%, the S&P 500 added 1.6%, and the NASDAQ eked out a 0.1% gain. The global equity picture was mixed; Developed Markets notched 2.9% higher, while Emerging Markets fell 1.1%. The Russell 2000 slipped 1.8%, marking its third consecutive monthly decline.


Signs pointed to tamer inflation in April as the [year-over-year] US Producer Price Index fell all the way to 2.75%. US Inflation broke below 5% as US Core Inflation hovered around 5.5%. The price of WTI crude oil rose 3.9% to $78.64 per barrel and Brent shot up 6.4% to $84.23. This caused the average price of regular gas to increase almost a quarter per gallon, to $3.77 at the end of April.


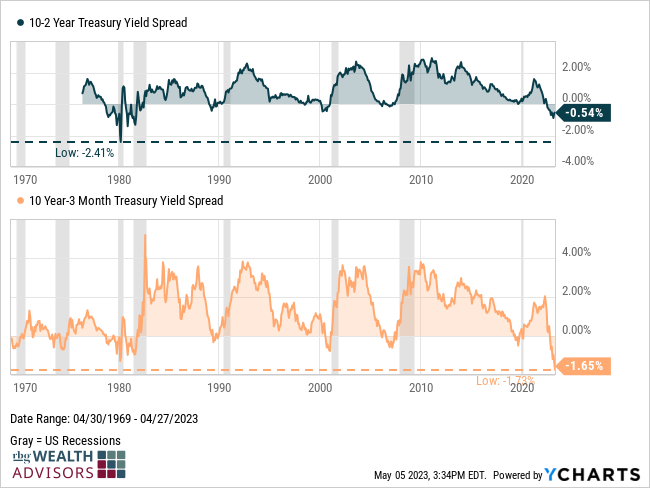
US Treasury yields broke 5% once again. The 3-Month and 6-Month Treasury Bills were the two durations to surpass 5% in April, at 5.18% and 5.06% respectively. April marked the 3-Month’s highest level for the since February 2007. The 5-Year’s yield of 3.51% was the lowest on the curve. Lastly, the 10 Year-3 Month Treasury Yield spread sunk to -1.65%, marking the spread’s largest inversion in history.”

Read More
 

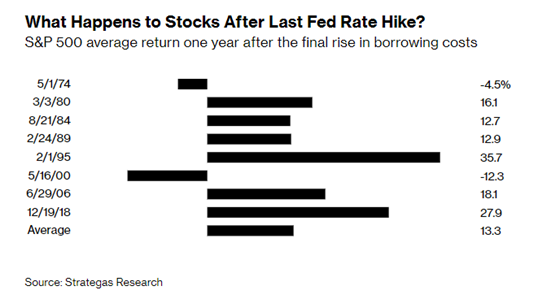
Graph of the Week

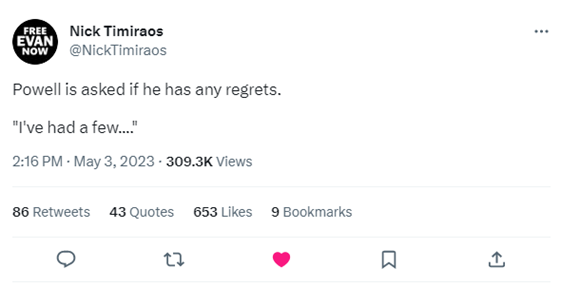
Tweet of the Week

Thanks for reading. Have a great weekend!


Guidance for today. Growth for tomorrow.


RBGWA - Logo - Full Color.jpg

Tim Ellis, CPA/PFS, CFP®

CIO and Wealth Advisor

RBG Wealth Advisors

M: 901.682.2431 | C: 662.444.1415

E:  tellis@rbgwa.com

A:  5100 Wheelis Dr., Ste. 300, Memphis, TN 38117

W: rbgwa.com

LinkedIn  Twitter  Facebook

RBG Wealth Advisors LLC is a registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Investments involve risk and, unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Past performance is not indicative of future performance.