|
“The Fed is done.
It’s unimaginable that they will do anything at the September FOMC meeting, and barring any radical change in the data, it’s unlikely they will be doing anything in November.
I have been saying since June 2022 that inflation had peaked; the data has been leaning that way since May 2022. If you were watching the video instead of the still pic, it was apparent that the biggest risk to the economy then was less rising prices than a tardy FOMC over-tightening.
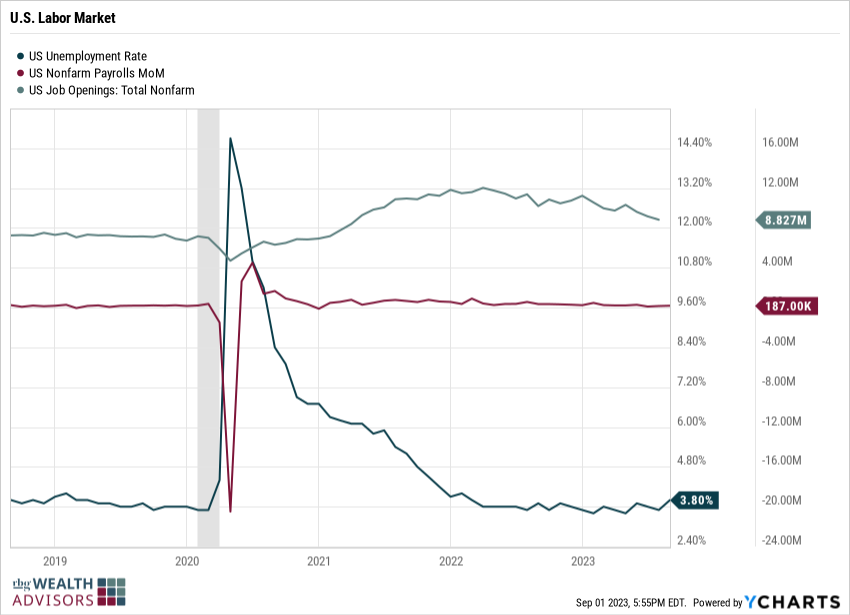
Not only did U3 unemployment tick up 0.3%, wage data continued to decelerate and revisions were downwards. Perhaps most intriguing is total employment: After collapsing during the pandemic, and then spiking upwards as we re-opened, this report shows it has returned to its long-term trend.”
Tuesday’s Jobs Opening and Labor Turnover Survey (JOLTS) report was a harbinger of some softening in the labor market. That report showed job openings dropped to the lowest level in 2 ½ years and workers quitting their jobs also decreased.
Friday’s jobs report showed +187,000 jobs, which was at expectations, but the prior two months were revised downward by 110,000. That plus an increase in the participation rate made the headline unemployment rate rise to 3.8%.
Fine, but softening. That should give the Fed something to think about. The stock market reaction was mixed-to-mildly positive.
|