|
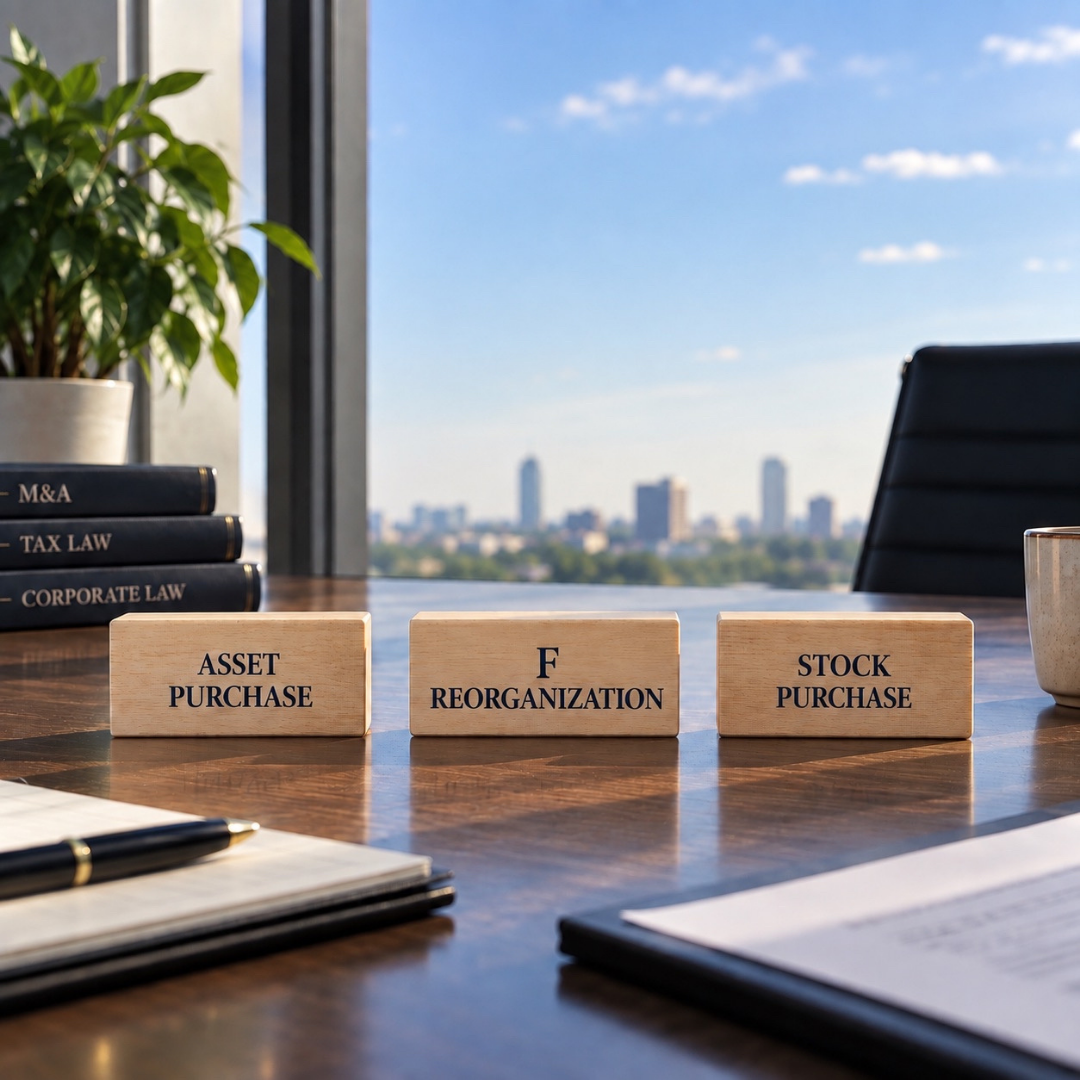
When buying or selling a business, one of the most important negotiations often involves the structure of the transaction. Buyers frequently prefer an asset purchase because it can provide valuable tax benefits. Sellers, on the other hand, prefer to sell stock because it can be simpler and may produce a more favorable capital gains tax treatment.
An F reorganization can help bridge that gap.
Under Section 368(a)(1)(F) of the Internal Revenue Code, an F reorganization is a tax-free restructuring involving a change in the identity, form, or place of organization of a single corporation...
|