What Is A Seller-Paid Rate Buydown?
Lenders allow the seller of a home to “credit” a portion of their proceeds to the home buyer. This is called a seller concession. Seller concessions can be used to pay a buyer’s closing costs only, and cannot be used to help with the down payment.
What experienced mortgage and real estate professionals know is that seller concessions can also be used to pay mortgage points and buy down the interest rate.
The whole idea for the seller-paid rate buydown is to get money back from the seller to permanently buy down the interest rate. The majority of agents and mortgage professionals will distribute the seller funds to underwriting costs, escrow fees, and loan fees…not many of them think to permanently buy down the interest rate on the loan which significantly reduces the monthly mortgage payment.
Who Benefits From A Seller-Paid Rate Buydown?
At first thought, it may seem like a seller-paid rate buydown only benefits the buyer and not the seller.
In a typical seller’s market, where there are always multiple offers on homes and bidding wars are the norm, this may be true. But as we mentioned above, rising interest rates are throttling affordability and leading to fewer mortgage applications – especially for higher-priced homes.
When this is the case, the go-to solution is for the seller to reduce the asking price of the home. But this is actually not the best way to go. A seller-paid rate buydown will actually result in more profit for both the buyer AND the seller.
Let’s take a look at how that’s possible.
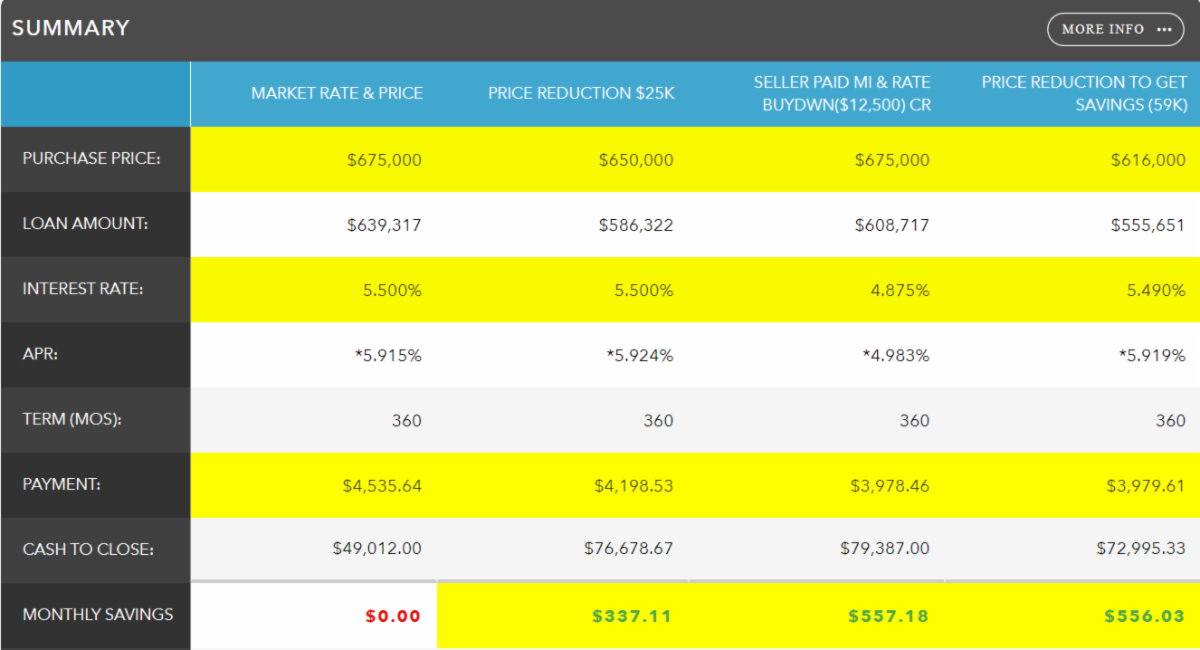
Below is a sample of a loan comparison showing options for purchasing a $675,000 home using a 30-year fixed-rate mortgage at a 5.5% interest rate.
???https://mcedge.tv/30yeez???
|