|
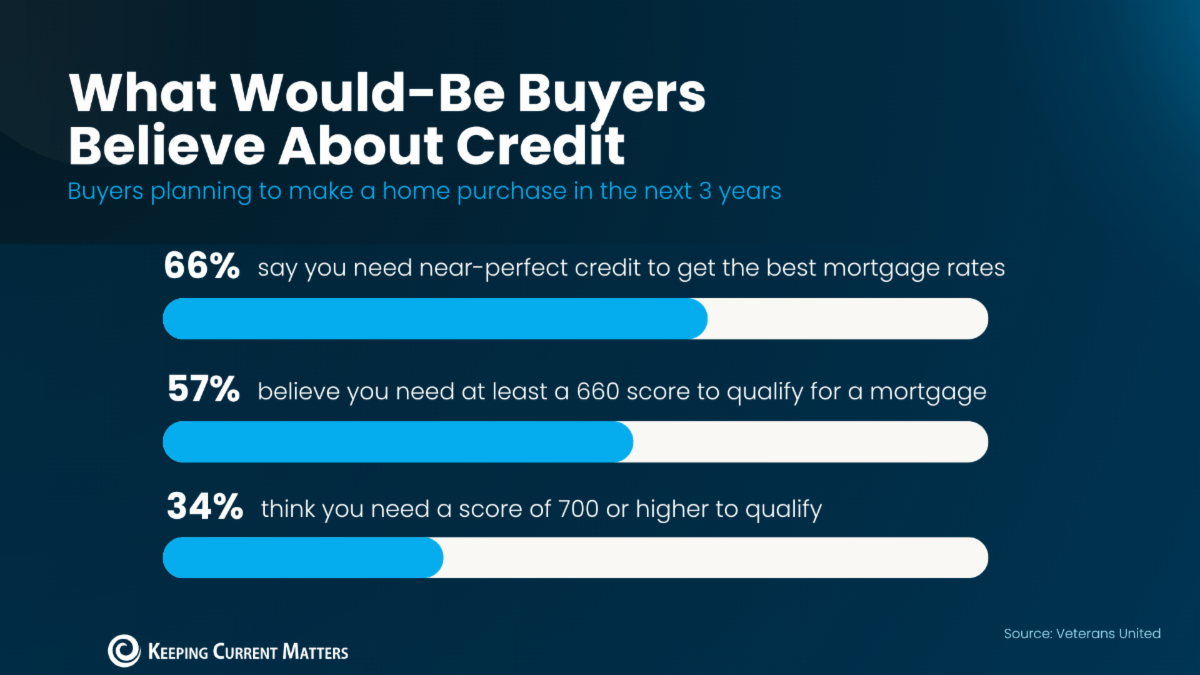
Quick test. Without Googling, what credit score do you need to buy a home?
If a number popped into your head, there is a good chance it is too high. Fannie Mae has been surveying consumers about this since 2015, and people keep overestimating the minimum score lenders want. As recently as 2023, the average guess was 652. The long-standing benchmark for Fannie Mae and Freddie Mac loans is 620, and these days even that is not a hard rule on every loan they back.
I run into this constantly. A renter in Metro Detroit decides their score is “probably not good enough,” so they never talk to a lender. Two years later they are still renting, and when they finally check, they were closer than they thought. Guessing wrong does not just feel bad. It costs time, and in Michigan, where good homes under $500K can still pull multiple offers in the right pockets, time matters.
Here is the other thing that has changed. For decades, mortgage lending ran on one set of scores, Classic FICO. The Federal Housing Finance Agency has now approved newer models, including FICO 10T and VantageScore 4.0. VantageScore says its model can score about 33 million adults that Classic FICO cannot. A different model can spit out a different number for the same person, so the score on your banking app last month may not be the one a lender pulls.
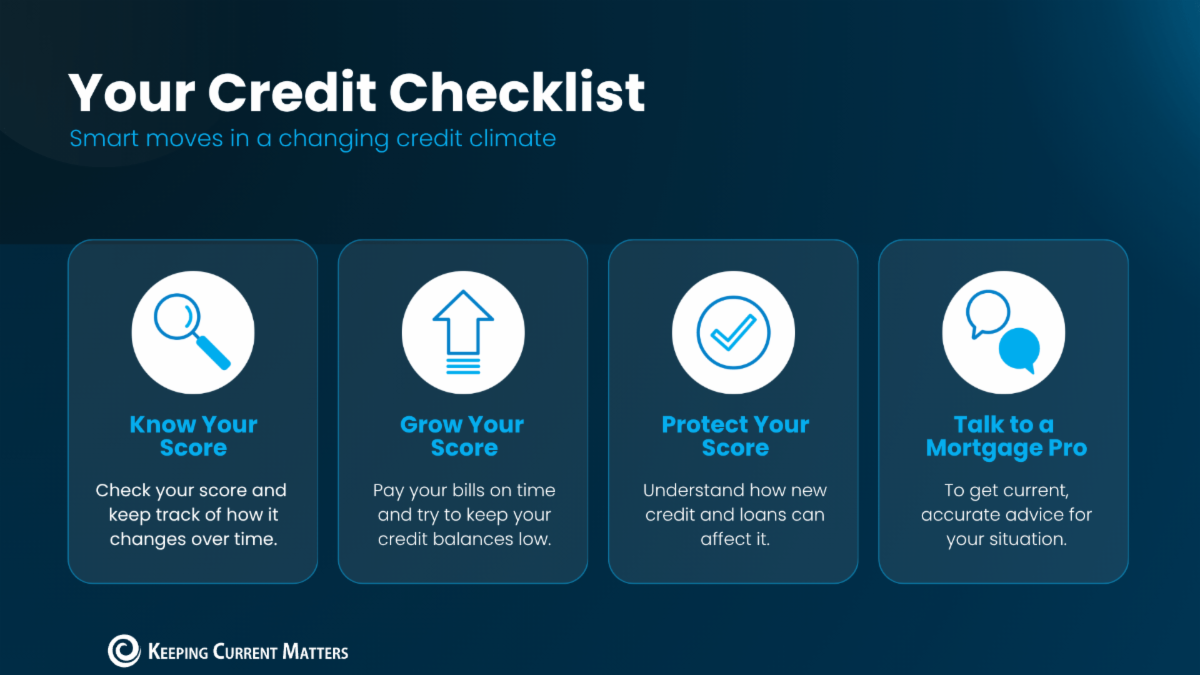
The good news is that the basics did not change. Pay on time, keep card balances low, do not open new debt right before you apply, and do not close old accounts for fun. Same playbook, new scorecards.
My takeaway: do not make a homebuying decision based on a chart, an app, or your cousin’s advice. A conversation with a loan officer is free, and it replaces guessing with a real answer.
If you are thinking about moving to Michigan and are in need of a good lender, I have several recommendations that I can provide.
|