RETIREMENT SECURITY MATTERS
A forum for retirement innovation information sharing focused on
states, supporters, and service providers.
Vol 38 | September 9, 2021
|
|
Greetings! welcome! to Retirement Security Matters – where we talk about retirement readiness innovation by states, supporters, and service providers.
|
Happy September! Have you had your first pumpkin spice latte yet? It’s hotter than the dickens out here, so our drink of choice is a nice, clean iced coffee. Grab something delicious and settle in for a good read:
-
Does ESG Attract Younger Savers? Newton’s Andrew Parry and Kevin Sullivan!
-
Fresh state metrics - *ding ding ding* assets have crossed a new mark
-
Breaking news from the Feds
-
State updates from Connecticut, New Mexico, California and New York
-
Columnist Joel Metlen says: Let’s all innovate together
- Hot Sauce! We got you some Social Security, Millennials, Women of Color + more
-
And, and bonanza of PIX. Just a bonanza.
ALERT – WE’RE TAKING OUR SUMMER VACATION LATE THIS YEAR SO YOU’LL SEE US AGAIN NEXT ON OCTOBER 7 WITH PIX OF GREEK ISLES. NEED AN RSM FIX? YOU CAN BROWSE ALL OF OUR BACK EDITIONS HERE.
|
|
ESG: Is Values-Aligned Investing Attracting Younger Savers?
|
|
We first met Kevin Sullivan and Andrew Parry in connection with California – a ways from home for both of them, and yet very close to home. Kevin is a New Englander with – dare we say it – a charming Boston-area accent. Andrew currently hails from near London, attended University in one of our favorite seaside towns – St. Andrews, and is also a pleasure to talk with. In California Kevin was part of the team sharing insights into Newton’s Environmental, Social and Governance strategies for the program that is likely to become the country’s largest Auto IRA, CalSavers (Andrew joined shortly after this). Here we go a little deeper into the thinking around ESG and why you may care about it going forward. |
|
Kevin Sullivan, CFA, CAIA and Andrew Parry, Newton Investment Management
|
|
Kevin Sullivan and Andrew Parry, tell us about your roles and teams at Newton Investment Management. Kevin let’s start with you.
KS: Newton was founded in 1978 and Responsible Investment has been part of the work that we do going back to our inception. While the approach has evolved, and will continue to develop with new learning, it's very much part of the fabric of who we are.
Awesome. How about you, Andrew?
AP: Righty-o. I'm a member of the Newton executive team and I'm responsible for the sustainable strategies at Newton, as well as the overall approach to responsible investing, which is a significant and long standing area at Newton. I work internally and externally on advocating with our clients and prospects for a more sustainable investment approach.
Newton’s is the first ESG investment offering in a state facilitated retirement savings program. Why do you think ESG is important to the savers in these programs?
AP: Let's remind people what ESG is. It's not a label. It's the environmental, social and governance influences that affect all businesses to a greater or lesser extent. It is simply good investing practice. It's about getting that complete insight into the nuanced, complex, and ever changing influences on a company's long-term profitability and success.
We like to think of it as helping us to navigate our clients through a world in flux. Helping to understand better those big thematic forces reshaping future business and economic opportunities, as well as revealing emerging risks that they might have to face. For us, it's just naturally Finance 101. It's what we should be doing to understand where the world is going in order to take our clients successfully on that journey.
We can think of two current influences -- COVID and how hot it's been in the west this summer.
AP: When you think about COVID crisis, it is essentially a human crisis -- with human cost, and social consequences. We also think of COVID from an economic perspective. This includes the response to COVID through slashing of interest rates, and all the liquidity pumped into the system. (Do not miss the great stuff that follows, HERE in the full article.)
Thank you Kevin and Andrew! We feel enlightened and we appreciate the insights you’ve shared here. Want to engage? You can connect directly by email with both Andrew and Kevin. You can follow their work at Newton Investment Management here and on Twitter.. You can also connect on social: Andrew and Kevin.
|
|
*Fresh!* State Auto IRA Program Metrics |
|
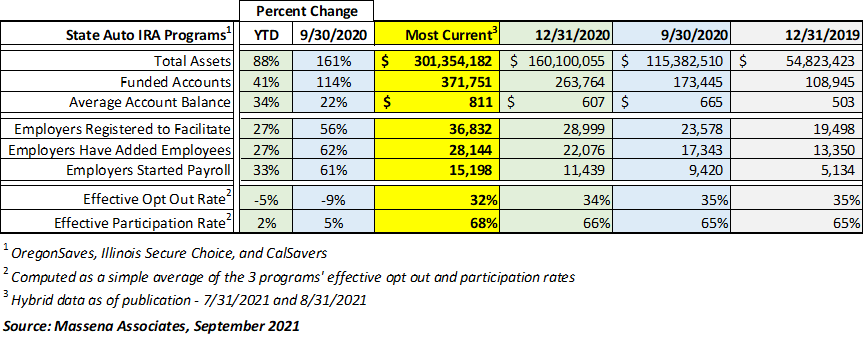
We love reading charts! *ding ding ding* Consolidated program assets have just crossed the $300 million mark, with the benefit of swift August 31 reporting from Illinois. Funded accounts are at 371,751 – up 41% year to date and up about 200,000 accounts from September of 2020.
Average account balances have climbed to $811. Does this seem low to you? Note that this is the average across all accounts with a balance, including brand new accounts. Longer term savers have balances that much higher, and in line with an average savings rate of $1,200 to $1,500 a year. We also recognize that for many workers covered by these programs, $800 that you saved, in an account with your name on it, is in fact a very big deal. Opt out rates are trending lower – down 5% this year and 9% since September last year.
Employer perspective: The number of employers registered to facilitate continues to rise. Expect to see a significant bump in this number when CalSavers reports their August 31 figures, shortly. It also takes time for employers to move from registration to facilitation. Here we see that the significant savings achieved above has been accomplished through the early 15,000 employers who have begun to facilitate these programs. Another 21,000 were in the pipeline as of this snapshot, with more pending registration in line with current program deadlines.
|
|
BUILD BACK BETTER – will Federal legislation goose the number of auto-enrolled workers by “requiring employers without employer-sponsored retirement plans to automatically enroll their employees in IRAs or 401(k)-type plans”? Maybe! If this one gets through budget recon as is, it will cover employees age 21+ working 500 hours a year for an employer with 5 or more employees. Check out Subtitle B of this proposed act for more details. (State programs enacted under legislation preceding this act would be part of the solution set; in this version, new state programs would not be.) The bill is currently scheduled for markup this week.
|
|
State Facilitated Retirement Programs - Fresh Highlights |
|
Connecticut (workforce 1.6 million) – Last week, the Republican American ran an informational piece about MyCTSavings written by the president and CEO of the Waterbury, Connecticut Regional Chamber, Lynn Ward. The article provided background and details about the program as well as timeline for implementation and information for employers. Ward quoted State Comptroller Lembo who said, “small businesses in Connecticut often struggle to recruit and maintain top-quality talent. MyCTSavings will provide a mechanism for these businesses to not only recruit but retain their employees by being able to offer retirement benefits similar to larger competitors.”
|
|
New Mexico (workforce 1 million) – At its board meeting on August 26 New Mexico Work and $ave reported out its progress, including commissioning of refreshed analytics on employment, under-saving, and related costs to the state. The Board also anticipates taking a fresh look at the financial feasibility of its voluntary Auto IRA program and anticipated usage by employers of its retirement plan marketplace. The Education and Outreach Committee reported on its engagement with a range of state agency stakeholders. The Rules Committee is also active with draft rules potential available for Board review as soon as November of this year. Executive Director Claudia Armijo reported on the programs’ fiscal year 2022-23 proposed expenditure and budget request related to launch and early operation.
|
|
California (workforce 17.9 million) – We haven’t asked what’s afoot in the Golden State, but like everyone else, they are hiring! Applications are due of these three positions by September 24:
|
|
New York State (workforce 9.3 million) – No new news on AB 3213, which passed the legislature on June 7 and is pending Gubernatorial signature. This bill is a legislative proposal to ensure employees are automatically enrolled into the authorized-but-not-yet-implemented New York Secure Choice Savings Program.
|
|
C O M I N G U P
-
Oregon (workforce 1.9 million) – The next meeting of the OregonSaves Board is scheduled for November 9, 2021.
-
New Mexico (workforce 1 million) – The next meeting of the New Mexico Work & $ave Board is scheduled for Nov. 4, 2021. For more information, please visit the Board’s website here.
|
|
Let's All Innovate Together! |
|
We have seen a lot of important and impactful innovation in the area of retirement savings over the last few years, especially in multiple employer plans, state-sponsored retirement plans, and the increased use of automatic enrollment. These innovations are helping us start to address the retirement savings gap in this country, but gains in just the retirement space aren’t enough if we really want to improve people’s overall financial wellbeing. Saving more for your future retirement doesn’t really help, for example, if that leads you to increase high-interest credit card debt in the short-term just to meet your basic needs.
We need to think about helping people holistically. Let’s not just get more people to save for retirement. That’s just one piece of the puzzle. Let’s simultaneously help folks get their first bank account, pay down their credit card debt, secure affordable housing, manage student debt, find affordable health care, land higher paying jobs, diversify revenue sources, access cheap, healthy food, pay for transportation needs, and get affordable child care.
In policy circles, we tend to focus on our areas of interest and expertise. We innovate in our specialized space or help people with one specific need and then send them on their way. That’s not enough.
|
|
Behavioral economics has taught us the value of designing systems around default human behavior. We need to figure out how to actually connect those services and create a seamless system of support for folks, to help them with all of their current and future needs, so that they can in turn maximize their own potential.
Stay tuned! / Joel
|
|
Columnist and Senior Associate Joel Metlen is based in Oregon. Joel is a pioneer of the state facilitated retirement savings space, woven into a career of public service and innovation. At OregonSaves, Joel’s responsibilities ranged from marketing and employer engagement to operations and data analysis. You’ll see his insights from that experience, and more, here.
|
|
Factors contributing to financial well-being among Black and Hispanic women – new research by Robert Clark, Annamaria Lusardi, Olivia S. Mitchell and Hallie Davis in DCIIA’s Journal of Retirement – probably requires a subscription for the very detailed view. You data scientists are going to want to see this one. TIAA also published a version of this work, here. and we’ll share a few key points with you. “Black and Hispanic women are less likely than White women to own assets.” Contributing factors may include that “Black and Hispanic women are more likely to be unmarried parents, making saving and homeownership more difficult. They also tend to have lower-wage employment with fewer benefits, including employer-sponsored retirement accounts, again making saving and asset accumulation more problematic” What works to change the financial wellness dynamic? This research concludes that a one size fits all approach doesn’t fit here, and makes suggestions for targeted programming. We’ll also suggest that employment with benefits, such as access to automated savings, can be part of the solution set.
And, it looks like Millennials are increasingly turning to financial advisors, according to a new survey by Broadridge. Why? “Of the millennial investors who do not work with a financial advisor, but plan to, 53% state that they are likely to work with an advisor due to the concern of not being on track to meet financial goals. Further, almost half (46%) of all investors who do not work with a financial advisor, but plan to, state that they are likely to work with an advisor to reduce financial stress.” More info here; regrettably we weren’t able to track down the original survey itself.
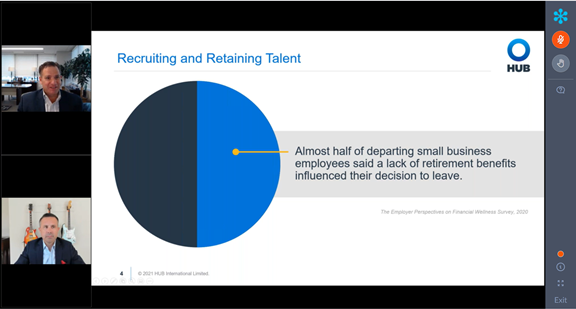
From a current webinar by HUB International: Employee Retirement Benefits for Small Businesses: Challenges and Solutions. Good perspectives by Joe DeNoyior and Rich Cawthorne on the small employer marketplace and an interesting discussion on state programs vs. 401(k) plans.
|
|
Eyeballs on: From the world of presidential reading, we are deep in to #23, Benjamin Harrison. From the midsection of Benjamin Harrison: Hoosier Warrior we take this excerpt from a letter written to the young prosecutor by his father and we dedicate it to our loved ones: “… my experience tells me that life is very much of a mixed draught – in which the bitter and the sweet are pretty fairly – or at least equally contributed – afflictions sometimes bring joys and again, joys afflictions, and so we are all never perfectly happy, -- and again never so miserable, that hope does not spread a small ray on the surrounding darkness.”
Need some Zen? Here’s a new kind, achieved while driving the streets of London.
|
|
… We've got a PIX of the week Bonanza you won't believe! |
|
|
|
|
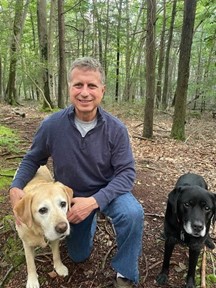
Let’s start with our friends from Newton Investments. We can tell Kevin Sullivan likes to get his walk on. Here he is hiking in Vermont, and a little closer to home in Wompatuck State Park with his best friends, Gus and Kona.
|
|
We suspect he had some other human company on those walks, taking the snappies.
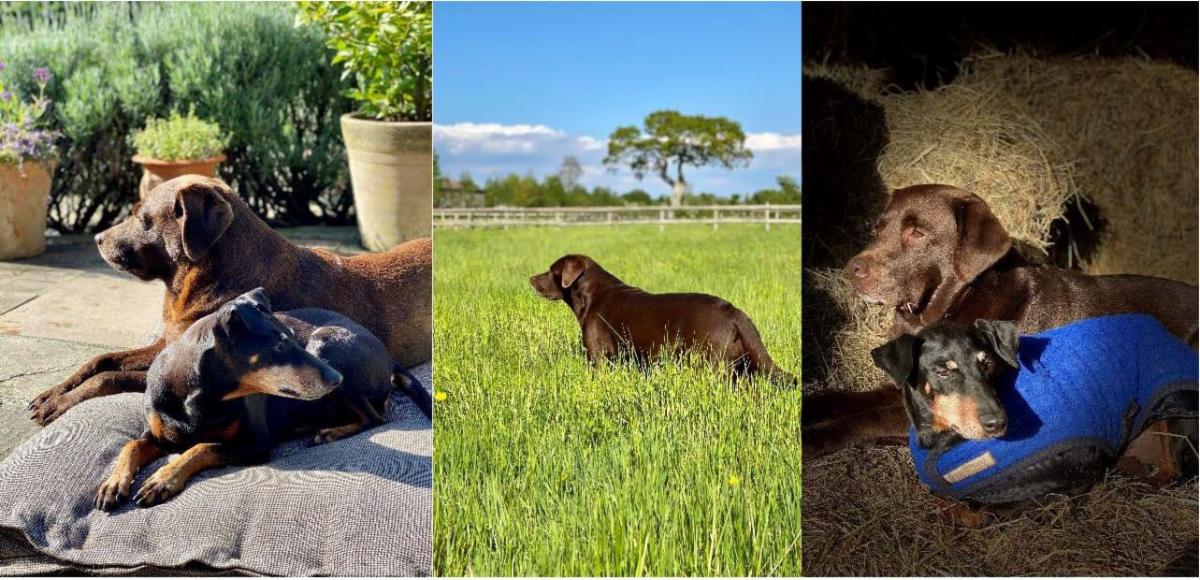
Not to be out-done, Andrew Parry’s got a couple of pups to show off as well. Meet Chocolate Lab Rosie and Manchester Terrier Maggie. Excellent companions, and hardworking, too.
|
|
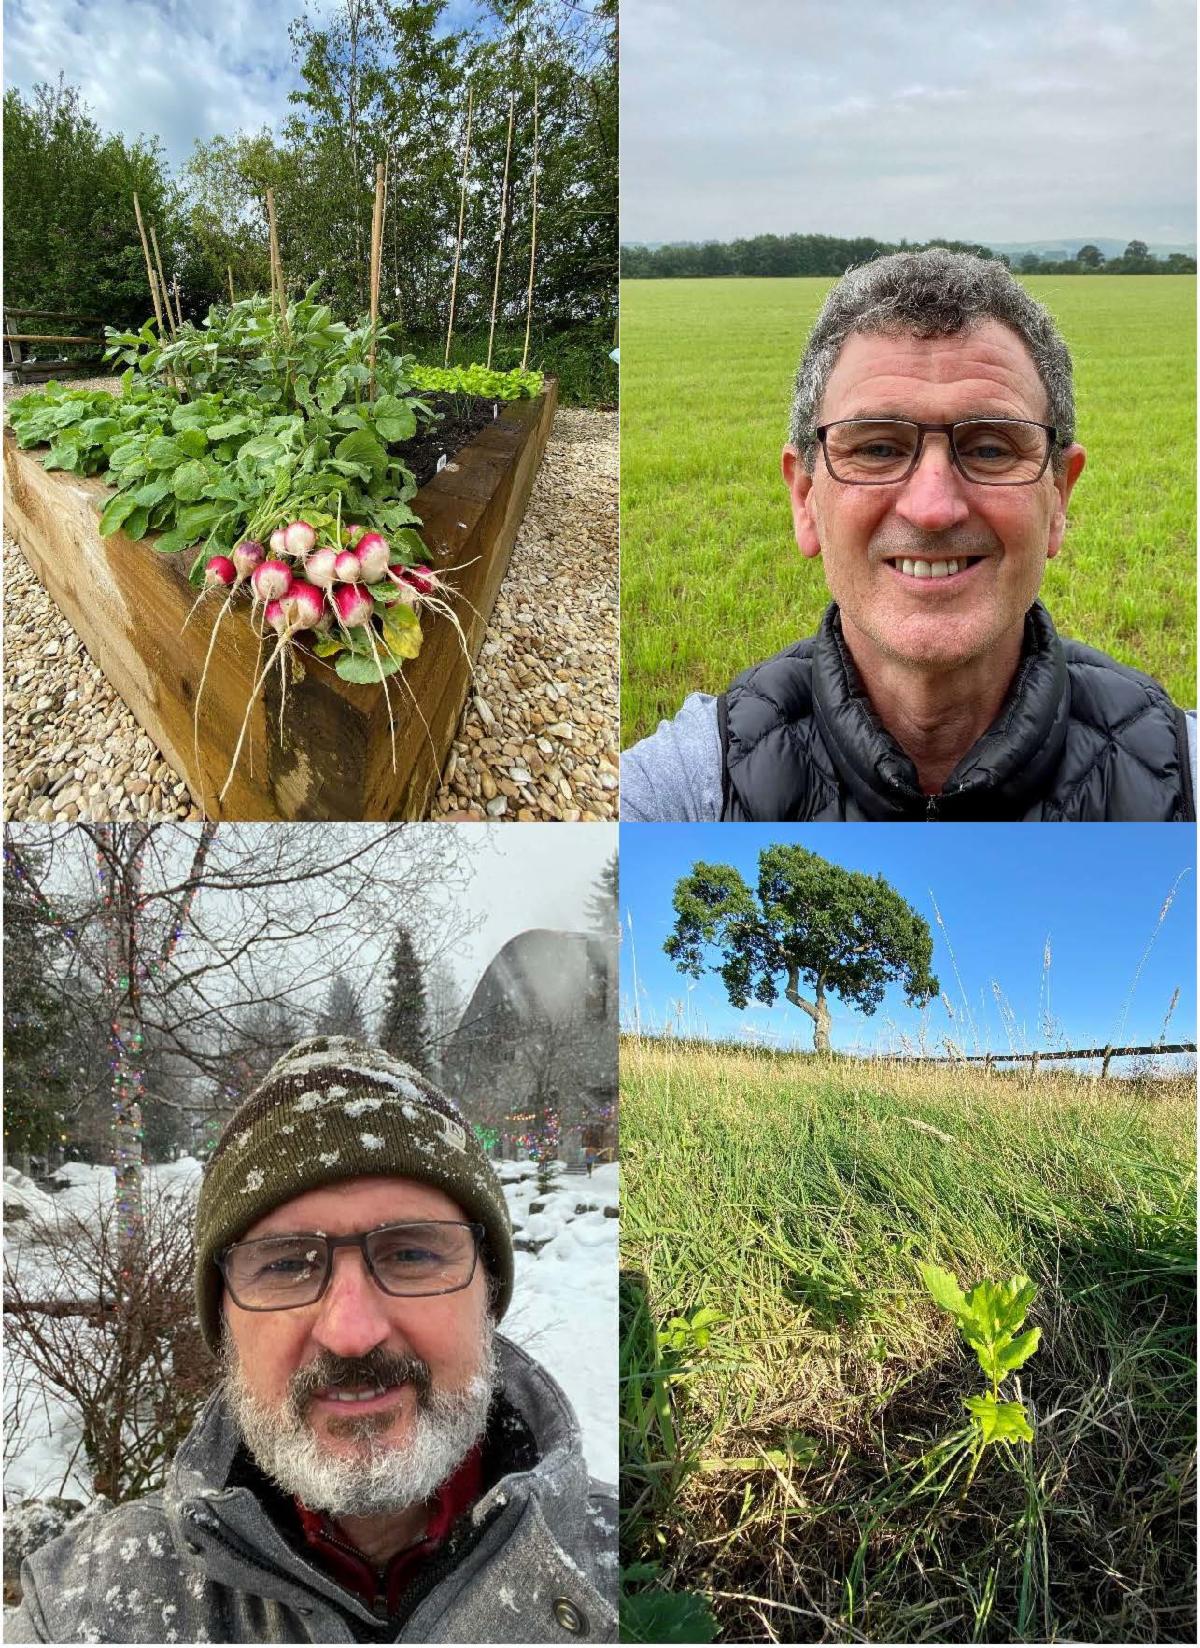
You might expect a guy that’s focused on ESG to be very interested in the natural world. Here’s that fabled raised vegetable bed, home to a bumper crop of courgettes and some nice-looking radishes. Over Andrew’s shoulder “somewhere in southwest Oxfordshire” if you looked very hard you might see a chalk horse carved in the hills above the house and a Neolithic fort.
|
|
And this little sapling is part of the mast event we talked about – seeded into the field by a neighbor’s oak tree. Finally, working remotely has some benefits … including sometimes an early autumn sunrise from the home office that might just distract one from the efforts at hand. |
|
Amazing. Thank you Andrew and Kevin!
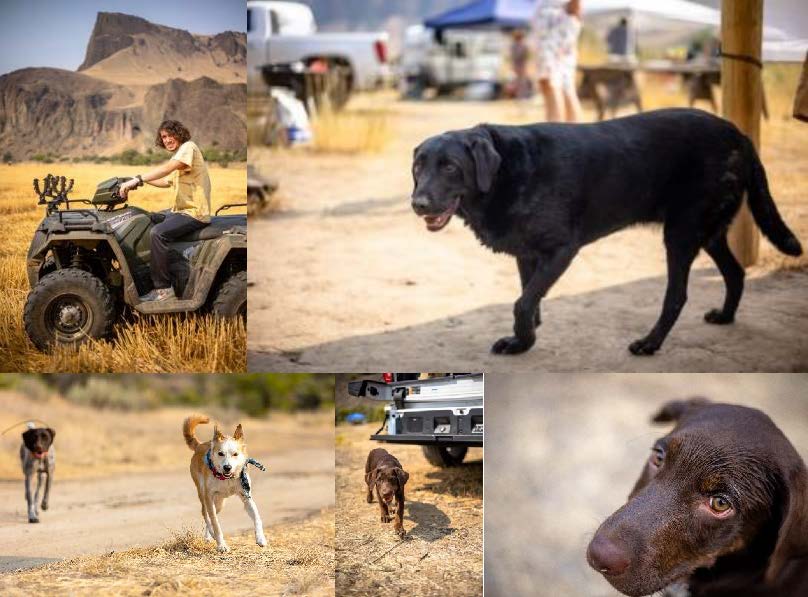
We can’t compete with these cute pups, but we can share scenes of Labor Day in Clarno, Oregon, population #notverymany. |
|
In the evening, stars peek through the smoke of many remote fires. And without internet, plenty of adventures for bright young lads and lassies. |
|
That’s it for this edition! ❤ Hug your people and change the world.
If you like this piece, please stick with us. We’ll be back in about two weeks. If you don’t like it, please unsubscribe below. Comments for us? Please let us know. Want your own subscription? Request one here. All information shared is from public sources or used with express permission.
|
|
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes states, governments, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684. |
|
Looking for a great retirement savings innovation resource? Led by Dr. Alicia Munnell, the Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
|
|
|
|
|
|
|