|
RETIREMENT SECURITY MATTERS
A forum for retirement savings innovation, together.
Vol 104 | July 16 2026
| | |
Greetings! Greetings! welcome to Retirement Security Matters—where we talk about retirement readiness innovation across public and private spaces. | |
HAPPY 250TH MONTH! We hope your celebrations have been amazing. It’s the heart of summer this week—warm and sunny where we are, and we hope the same for you. Our drink of choice is Wilds Now Craft Instant Coffee—Voyager Blend. Do not laugh at us. It is delicious, especially over ice with a splash of cream. Now snag one for yourself and catch your breath for a moment.
IN THIS EDITION WE'VE GOT:
-
Our friend and yours, Paul Revere—on Pensions
- State Auto IRAs by the numbers
- States (and a City) in Action: AK, MI, NY and Philly
- Hot Sauce, Cool Stuff—A 530A by any other name, and MUCH MORE, and
-
PIX 📸 of the Week, travel edition
| | View as Webpage Comments or content suggestions? We welcome both. Have something about your program or work you’d like to share? We are all ears. | Paul Revere's Pension: 250 Years of Retirement in America | | We've turned 250! Don't we look great for our age? The anniversary got us thinking about retirement through the years. The pilgrims didn't have pensions … right. But we do, and we need them. What's changed! Grab a pony and walk with us through a fanciful review of retirement in the USA. | | |
1776: I'm not old, you're old.
In 1776, most Americans—19 out of 20—lived in the countryside. Folks lived on farms, in small villages, surrounded by people they'd known all their lives. Growing old didn't mean stepping away from that world. It meant becoming its senior member: the person whose judgment on planting, matchmaking, or town disputes carried more weight.
Formal retirement wasn’t a thing—with some interesting notes. In 1776, just weeks after the Declaration of Independence was signed, the new Continental Congress authorized pensions for soldiers disabled in the Revolutionary War. It's one of the first formal national level retirement benefits in American history, though it only covered soldiers hurt in the fight. [more—here!]
1826: Country Mouse and City Mouse
Fifty years later, America was still mostly rural. More than 9 in 10 Americans lived outside cities. The multigenerational household was still the backbone of old-age security. But this wasn't just children taking pity on aging parents. It was often a real agreement, worked out by both sides. Call it a private pension arrangement, if you dare. [and what else?]
1876: We’re closer together
By the mid-1870s, roughly one in four Americans lived in a town or city. The country was still mostly rural, but the times, they were a-changing. Factories and industry pulled younger workers toward cities and away from the family farm. In this shift communities found new ways to fill the gap once covered by extended family. [more]
This isn’t really a country/city story … it’s a retirement story! if you want the rest of the story, [join us here]
-
So, what really happened to Paul Revere’s pension? Oh, Paul.
-
Meet the country mouse and the city mouse of 1826. Farmhouse. Almshouse. Other?
-
1876: a third of American men joined the same kind of club. (A THIRD.) Find out what it was.
-
The 1920s invented leisure for the middle class. And a waterfront hideaway for maritimers.
-
One law, signed in 1935, changed everything. We love it. ❤️ Do you?
-
1976: two systems, one safety net—and a very colorful side trend involving Arizona.
-
2026: we made a list. Seven proven ingredients for our modern retirement system.
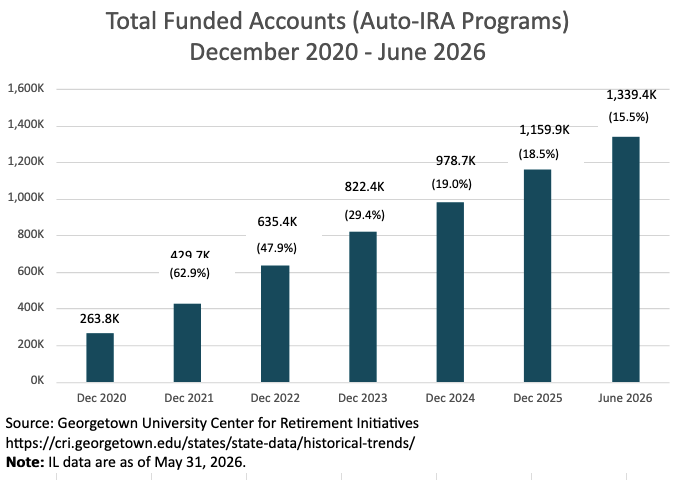
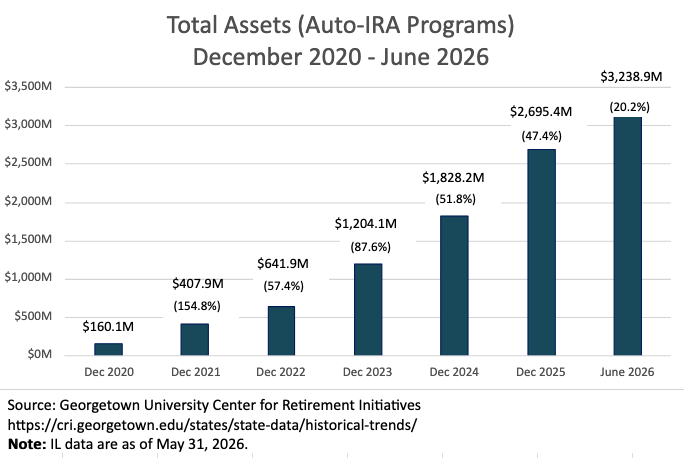
| | State Auto IRAs: The Score | | Welcome to the fold, Minnesota! We are now at 1.33 million funded accounts across the Auto IRA programs currently reporting, which now includes our friends in Minnesota. This represents an increase in accounts of more than 15% since the start of the year, and 37% in the 18 months from start of 2025 to now. NOTE that our friends in Illinois are undergoing a program manager change and their data is as of May 31. The balance of this data is from June 30. | | Accumulated assets across the programs are up 20% year to date—both from funds contributed and market action—and now stand at $3.2 billion invested through Auto IRA accounts. This is an increase of 77% over asset levels at the start of 2025. #welldone, Auto IRA savers! | | States in Action—And One City. AK, MI, NY and Philly. | | |
Four states, four very different summers. One veto, one deadline, one Senate vote, and one program quietly doing its homework. Here's where things stand.
Alaska: So Close But Not Yet
Alaska's Work and Save program made it all the way to the Governor's desk—and then no further. Gov. Mike Dunleavy vetoed the bill in June, objecting to the automatic-enrollment mandate even with its opt-out clause. Lawmakers tried to override him. They fell short by one vote. What we think of this: a great deal of groundwork has been done. Alaska now has a bill, a coalition, and a floor vote on record. Good legislation does take time.
Michigan: The Senate Says Yes. The House Says...We'll See.
On June 17, the Michigan Senate passed a two-bill package creating the Michigan Secure Retirement Savings Program—a straight party-line 20–18 vote that sends the measure to a Republican-controlled House. About 1.5 million Michigan workers currently have no way to save for retirement through their job. The Senate just made its case for why that should change. Now it's the House's turn to decide if it can agree.
New York: Last Call for Employers
New York's Secure Choice rollout wraps up its staggered deadline schedule this week—employers with 10 to 14 employees had until July 15 to register or certify an exemption. Combined with the March and May deadlines for larger employers, this closes the loop on one of the more ambitious rollouts in the country. We have predicted significant increases in Auto IRA funded accounts based on New York’s size. All good things take time. Join us as we watch and applaud.
Philadelphia: Quietly Doing Its Homework
No fireworks here—and that's fine. PhillySaves, expected to be the nation's first city-run Auto IRA to achieve launch, is in prep phases after May's ballot approval. Contributions aren't required to start until July 2027, so this summer is about foundation-laying: establishing the program’s board and setting milestones and timing. Stay tuned.
| | Hot Sauce—Woohoo! It’s the Summer Break edition | |
Let’s jump straight to the fun stuff. Like a curated summer read taken oceanside, we are going to give you a few places to lay your eyes.
1 – Trump Accounts are live – with a lot of fanfare and a shared-exchange bell ringing in the Oval Office. Under the hoopla lies some really good news. More than 6 million kids’ accounts have been established, many of them through tax-time check boxes and the efforts of tax support organizations like H&R Block. We are hearing that families of all incomes are signing up at near-equivalent rates. We. Like. This. Especially from a voluntary process. Kudos to all for finding early easy buttons. With these 530As launched, watch for focus coming to TrumpIRAs soon. [We’ve talked about this a bit lately -- with Theresa Ghilarducci, with KC Boas and Karen Andres, and with the inimitable Michael Kreps.]
2 – Research Corner.
A. We always like Vanguard’s How America Saves – this is the 25th edition, and yes, it is 110 pages long. Interested in how your plan stacks up against industry peers? Vanguard has that. We like to look at the impact of design features, like automatic enrollment. We’ll pull one nugget out for you: for savers earning between $15,000 and $30,000, plan participation jumps from 26% to 89% when savers are auto-enrolled. IT MORE THAN TRIPLES. These are our Saver’s Match savers, gang. Design matters. You’ll enjoy the rest of the report, but check out pages 35 and 36.
B. Our friends at the Georgetown Center for Retirement Initiatives have a thorough new piece focused on Pooled Employer Plans – looking specifically at the recent five years of history (where does the time go), status of the space, and opportunities for improvement. From zero to $30 billion in five years—we’re impressed. As Georgetown notes, most new PEP assets originated in single employer plans and are a shift in product type, not new assets to the retirement savings space. Excellent work.
C. This is interesting. Check out DCIIA’s Defined Contribution Data Dashboard – developed in partnership with Manifest. Scroll over the Money IN / Money OUT data for a peek into some retirement security drivers.
3 – Sheer fun. Summer read style. Our relationship with Libby the Library App has taken us deep into the past and we’ve been finding new things there.
A. in Daphne Du Maurier’s Rebecca as narrated by Alexandra O’Karma, a new kind of ghost story. Almost every character in the tale is a ghost of one sort or another. We’ve never seen the movie, so we had to circle back and re-read the start of the book to put all the pieces together. Recommended.
B. Another dip into the past – Louisa May Alcott’s Little Women, as narrated by CM Hebert. We didn’t recall that this book had over 45 chapters and would be 19 hours long. We did laugh, and we did cry. Was it chapters 35 and 36? Our takeaway—Marmee’s voice in our head saying the 1860’s equivalent of “do the right thing.”
C. We picked up and discarded a few stories we just couldn’t get our minds around. Now we’re reading Griffin Dunne’s bio-piece, The Friday Afternoon Club.
| | |
For reasons that are hard to describe, we found ourselves in five different countries over the months of May, June and July. It’s delightful to see the world, and we also found lots of reasons to love the one we’re with—meaning the USA, Silly!
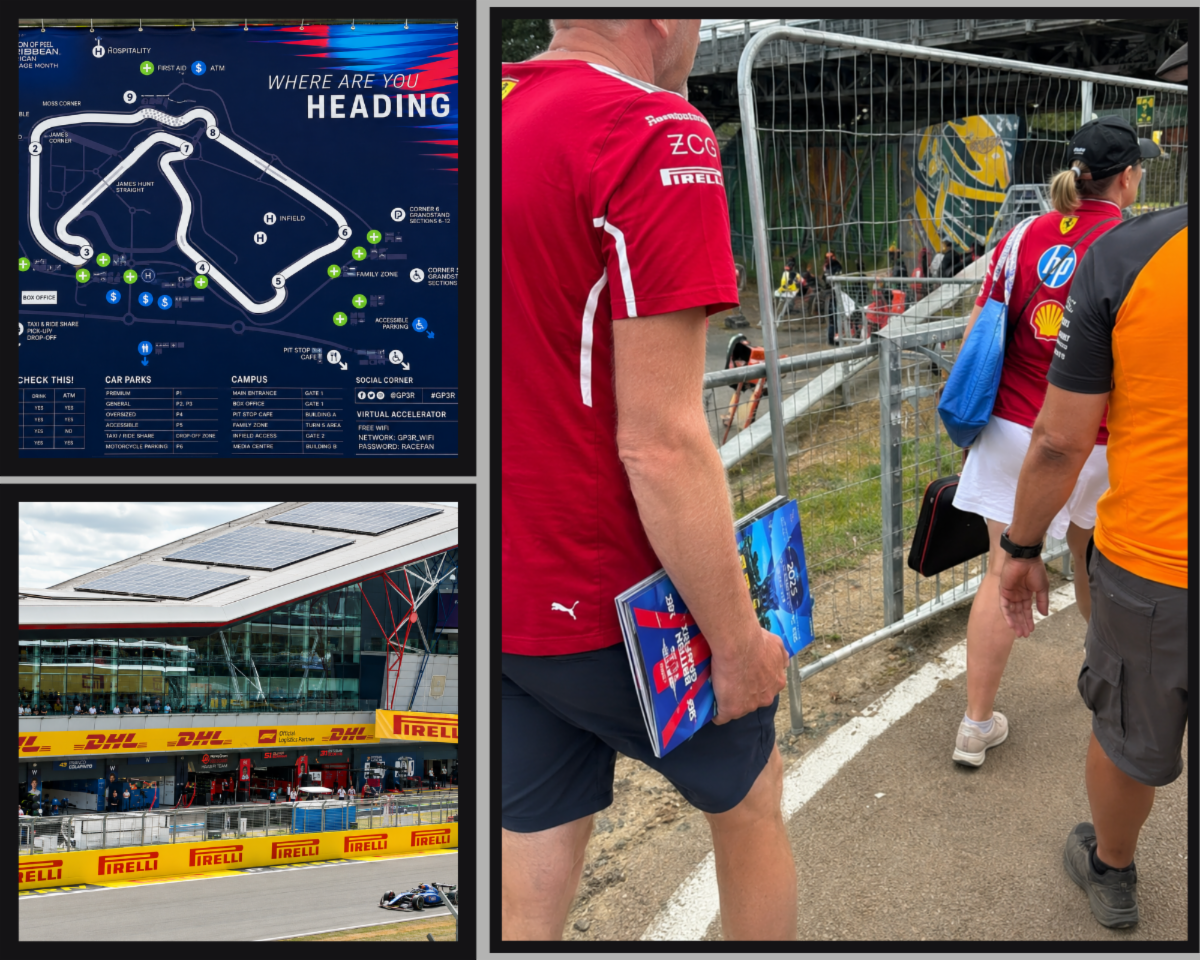
If you find yourself in London with a chance to attend Formula 1 at Silverstone, watching the race while staring into Lewis Hamilton’s pit bay for signs of action, do it. You will not regret it. Do not stay in an overpriced Airbnb in Northampton. You will regret that. Stay in Euston.
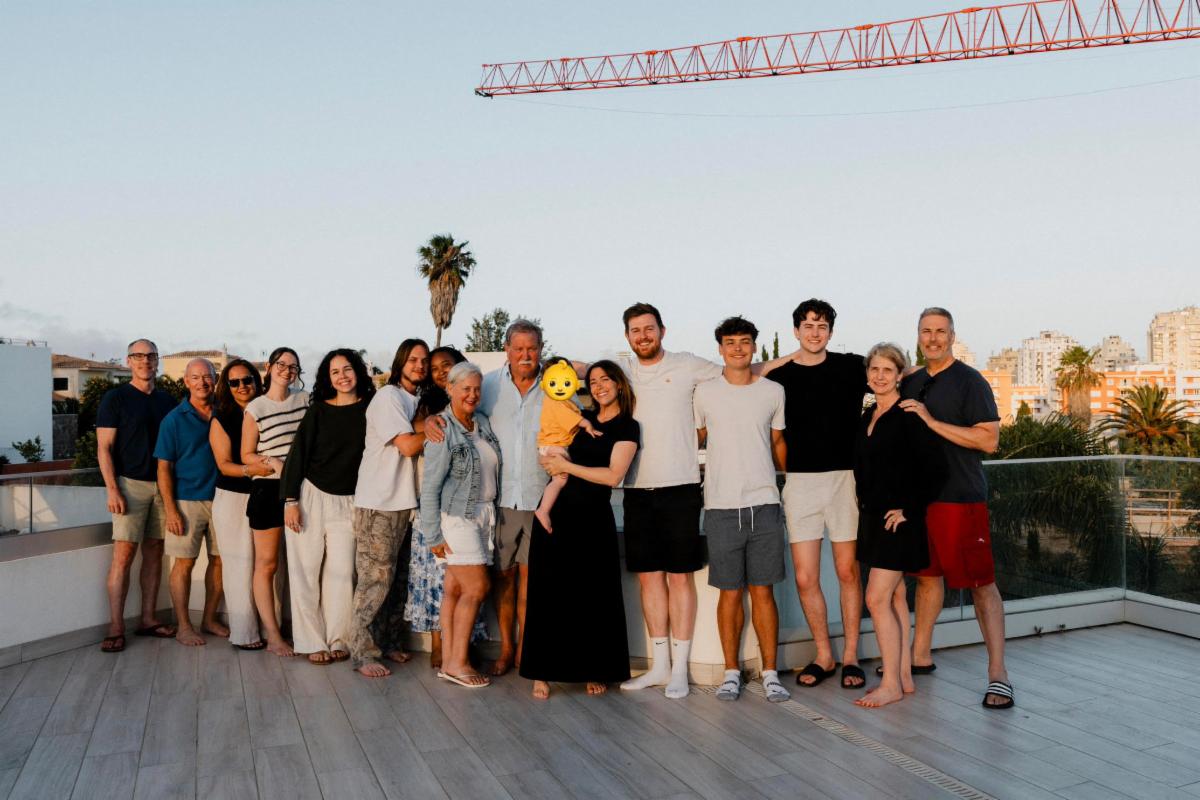
| | If you have a chance to visit Sintra in Portugal, that’s a Yes. If while you are there and one of these blossoms falls to the ground, do not pick it up and attempt to press it in a plastic folio alongside important papers. It is wet. You will regret that. | | If you have a chance to hang with a good chunk of your family in a town called Armacao de Pera in the Algarve of Portugal, that’s a Yes. Do not spend very much time looking at the crane directly in front of your Airbnb. You will regret that. Do take a day trip to Seville. That will be delightful, even if the drive is long. Do not try to cram in a cultural shortcut by taking the Hop On Hop Off bus. That will not be delightful at all, even if the drive is short. That’s a wrap, Gang—Love the Ones You Are With. | | |
That’s it for this edition. ❤ Hug your people and change the world.
| | |
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.
| | |
Looking for a great retirement savings innovation resource? The Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.
The Georgetown Center for Retirement Initiatives, Led by Angela Antonelli, GCRI provides excellent information on state-based and other retirement security innovation and policy.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.
| | | | |