|
RETIREMENT SECURITY MATTERS
A forum for retirement innovation information sharing
focused on states, supporters, and service providers.
Vol 82 | July 20, 2023
| | |
Greetings! Lisa, welcome to Retirement Security Matters – where we talk about retirement readiness innovation by states, supporters, and service providers. | |
We love summer! As the days grow more casual, we hope you're finding time to soak up the sun (or avoid it, if you’re in a heat dome) and enjoy this vibrant season. So, grab a lemonade or your iced coffee, sit back, and let us catch you up on the latest financially resilient retirement security news. (PS we’re on our summer holidays and schedule, putting in the final touches from our AirBNB in LeMans. Stay tuned for a pic or two at the end).
| Comments or content suggestions? We welcome both. Have something about your program you’d like to share? We are all ears. | |
|
RSM wants your support! Be seen.
Click to grab this space for your brand.
| |
4 Rules: Wharton’s Professor Keith Weigelt on Investing in the Neighborhoods | |
|
Good friends introduce you to good people. This week, we chat with Professor Keith Weigelt, thanks to an introduction from DCIIA’s Dominika Turkcan. Sometimes when you’re walking to work, you see something you can do something about. In this case, it involves money – and intergenerational wealth. Not all of us would start a financial empowerment program if we saw racial wealth inequality, but one man did. Here’s how it’s going.
This is an excerpt. The full piece can be found here.
| |
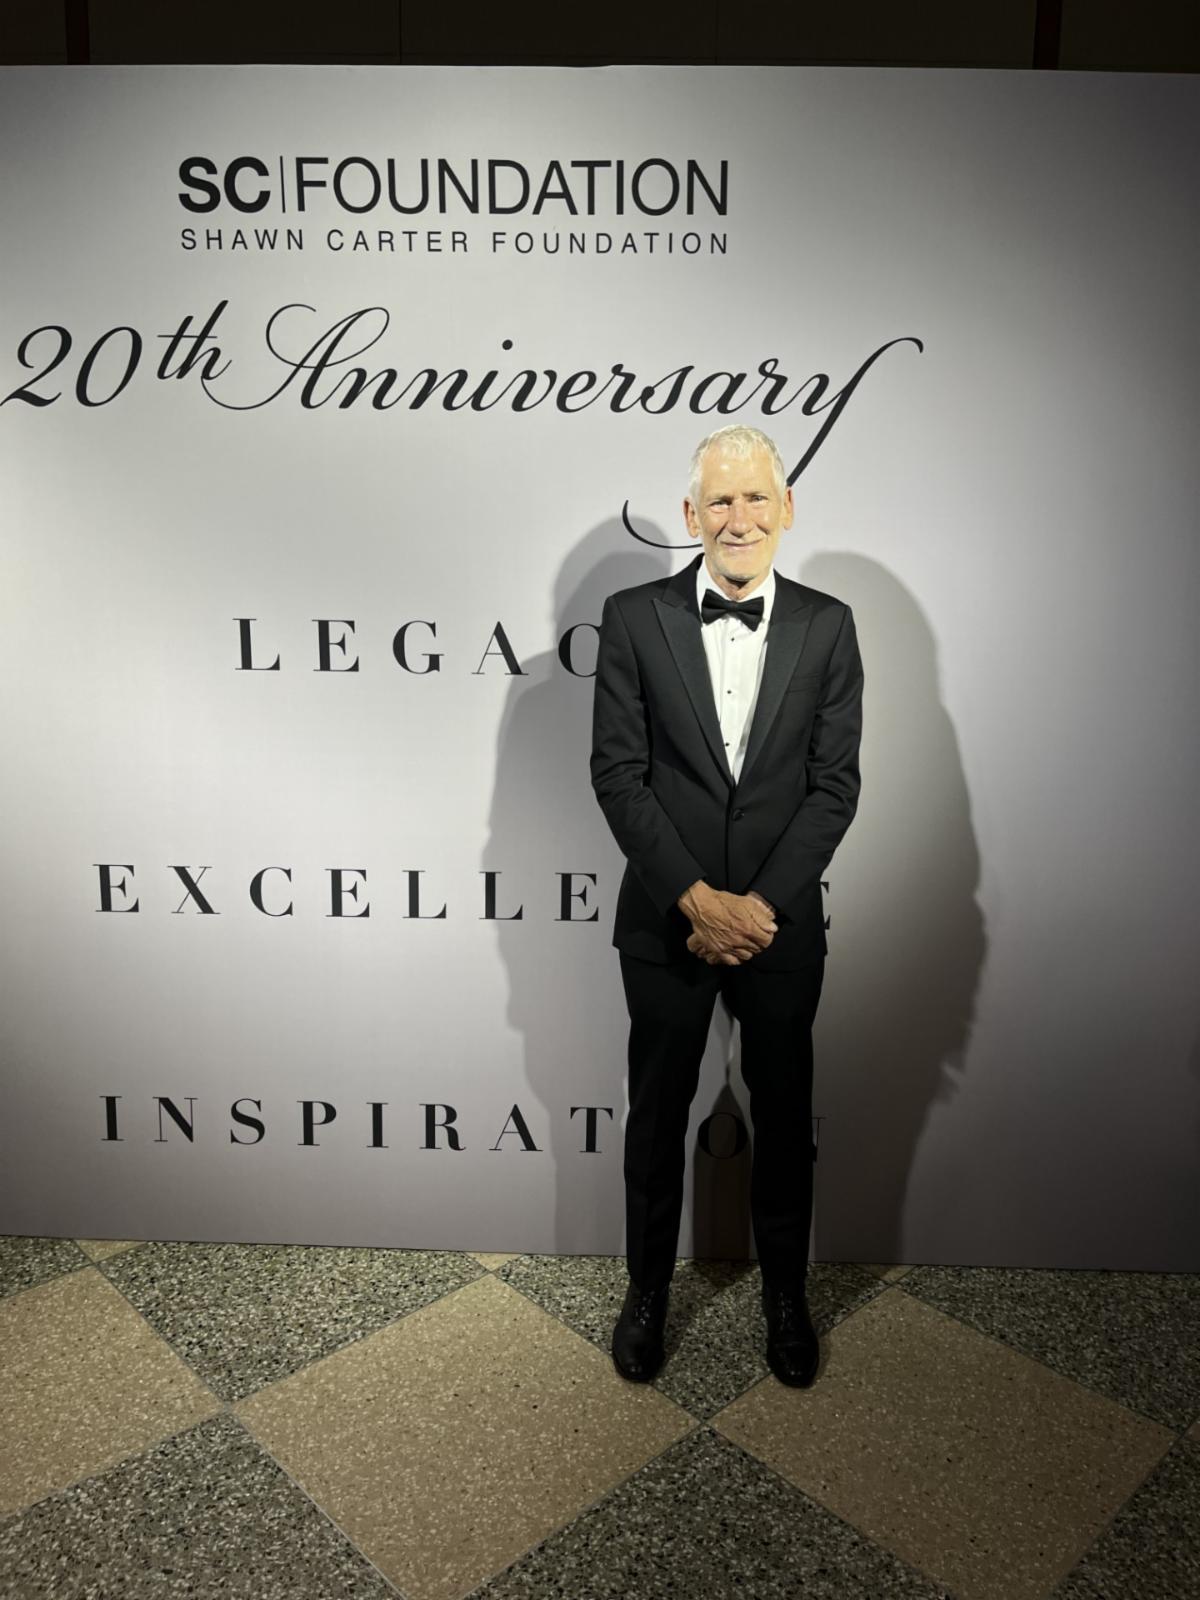
Dr. Keith Weigelt, Marks-Darivoff Family Professor of Strategy
The Wharton School, University of Pennsylvania
| |
|
Professor Weigelt, what got you into this?
I have been a professor at the Wharton School for about 30 years now. My training is in game theory. About 10 years ago, I thought maybe the university should do more for the community, so I thought, “Well, what could I do?” Financial empowerment seemed like a natural subject.
I went to churches in the neighborhood to recruit my first financial empowerment cohort. From that initial cohort, we created an organization, Bridges to Wealth. Bridges to Wealth has taught financial empowerment to over 7,500 participants, including both high school students and adults. Over 95% of our participants come from historically underserved households.
Our courses are different in two ways: One, we are more focused on showing participants how to invest while controlling risk. Two, we build in long-term engagement.
Let’s talk about the kids. Who are they?
Most of our teaching is in high schools; we are currently in about 15 Philadelphia high schools. I also have a community service class at Wharton where we train our students in financial empowerment and entrepreneurship, and we send them out to high schools to help the high school instructors teach. More than 150 UPenn undergraduates have mentored over 1,200 Philadelphia high school student participants.
We think wealth is intergenerational, so we felt it was important to get parents involved. We started a parent group at each high school, and that’s how we've built up our adult program.
We also have programs at several middle schools. In Brooklyn, we partner with the Shawn Carter Foundation for both an adult and student program. Encouragingly, we've had students who started with us in high school and then joined us as adults.
What are some common challenges participants face?
70% of our participants are women, most of them are single mothers and the head of the household. We try to build investing confidence and competence in women, and we work towards debunking the myth that investing is only for the wealthy. We also address the issue of scattered retirement savings resulting from frequent job changes. We prioritize educating participants about fees and focus on low-cost investments, such as index funds, aligning with our four rules of investing.
Oh! What are your Four Rules of Investing?
We try to simplify investing by telling participants they need to follow four simple rules.
- Increase efficiency
- Start early
- Use low-cost investments
- Diversify your portfolio
(Want to get the full details on these rules and more? Get the rest of the scoop from Professor Weigelt here).
Keith and Dominika – thank you for sharing your experience with this work in an important space. Information in action, making a difference – we couldn’t ask for more.
Want more? You can connect with Prof. Weigelt directly by email
Professor Keith W. Weigelt is a renowned management expert at the Wharton School, University of Pennsylvania, where he holds the Marks-Darivoff Family Professorship. With a background in economics and decision sciences, he specializes in strategic management, negotiations, game theory, and behavioral decision-making. Throughout his impressive career, Professor Weigelt has made significant contributions to the field through his impactful research and exceptional teaching. His studies delve into decision-making and competitive strategy, examining the complex dynamics between firms, markets, and individuals. He is widely recognized as a leading scholar, with his work published in top-tier academic journals. His nonprofit, Bridges to Wealth, is part of Wharton’s Coalition for Equity and Opportunity in partnership with the Sean Carter Foundation and Toyota.
| |
*Fresh!* State Auto IRA Program Metrics | |
|
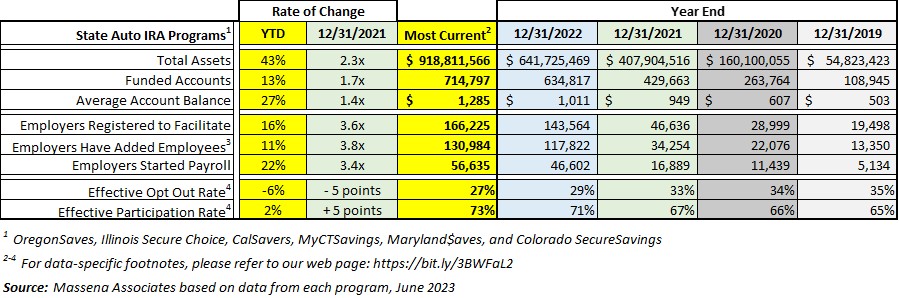
What’s up! closing out the second quarter of 2023 with steady growth!
Assets. Saver assets are up 48% year-to-date and 2.3x since December 2021 to $918 million, as CalSavers remains primed for additional growth throughout 2023 as employers respond to compliance notifications. Average account balances across the programs are over $1,200. Longer term balances are higher.
What’s your guess for the $1 billion mark? Send us a note - closest date wins you a prize. RSM 83 - August 10 // RSM 84 – August 31 // RSM 85 - September 14.
Funded accounts. The six programs shown here now aggregate to over 714,000 funded accounts. For comparison, funded accounts are up 1.7x since December 2021, up about 2.7x since December 2020 and up about 6.6x since December 2019 – and up in 2023.
Facilitating employers. Over 166,000 employers are now registered to facilitate a state Auto IRA. Of that number, more than 56,600 have begun forwarding payroll contributions for savers.
| |
State Facilitated Retirement Programs - Fresh Highlights | |
|
Delaware (workforce 499,000) – The Delaware EARNS Program Board met on July 13, 2023. Key items on the agenda included a market report by AKF Consulting and Office of the State Treasurer updates. The Board authorized the Treasurer’s office to evaluate entry into an interstate partnership or multistate consortium to support the launch and future success of the retirement savings program. “Partnering with other programs would allow for collaborative decision making with industry leaders and benefit the program as it moves towards its launch.” Treasurer Colleen Davis said in an official release (and in local news). View the RFI here. Also, this piece by ASPPA gives a bit more color and a great headline. Finally, during the meeting, the Board also authorized engagement with an investment consultant to assess investment opinions and architectures of the potential partnership; and discussed FY24 EARNS budget.
| |
|
Maine (workforce 674,000) – The Maine Retirement Savings Board met on July 19, 2023. Key items on the agenda included a summary report from Executive Director Beth Bordowitz, financial report, discussion of the Service Promise and Message Pillars as well as conversation with Vestwell.
In other news, Gov. Janet Mills on June 12 signed into law legislation that adjusts the program. This comes almost exactly two years after enactment of the Act To Promote Individual Retirement Savings through a Public-Private Partnership. Key changes the new law makes include: phased implantation, employer size of five employees or fewer, December 31, 2024 employer deadline, employer penalties, and intergovernmental collaboration and cooperation.
For an interesting summary of the fine-tuning of the program, check out NAPA's recent post here.
| |
|
Vermont (workforce 336,000) *Executive Director Opportunity* VTSaves opens search for Program Executive Director. View position description here. For a great highlight check out the ASPPA post here.
| |
|
C O M I N G U P
-
Hawaii (workforce 676,000) - The next meeting is tentatively scheduled on August 1, 2023.
-
Oregon (workforce 2.2 million) – The next meeting of the OregonSaves Board is tentatively scheduled for August 15, 2023.
-
Virginia (workforce 4.3 million) – The next meeting is tentatively scheduled for August 23, 2023.
-
Massachusetts (workforce 3.6 million) - The next meeting is tentatively scheduled for August 28, 2023.
-
Maryland (workforce 3.2 million) – The next meeting of the Maryland$aves Board is scheduled for September 11, 2023.
| |
|
Were we in Paris recently, having dinner with a telecomms exec who is ready to retire? Yes, yes we were. Our friend, let’s call him Alain, is 57 and recently missed a voluntary separation package by one month. Meaning: if he’d had one more month of tenure he would have been offered a separation package that included a fully vested retirement.
Would he have taken it? His Monday evening rumpled hair and slightly harassed demeanor indicate that yes, he would have. “I have six more years to go,” he says, and we sense him counting the weeks.
Is Alain happy about the shift in normal retirement age from 62 to 64? No, not at all. He tells us, “They could have figured it out. There was a way not to do this.” Perhaps to make himself feel better, he asks what the normal retirement age is in the US. 67, we say, for Social Security and 65 in most corporate retirement plans. It’s definitely not as low as the new French level.
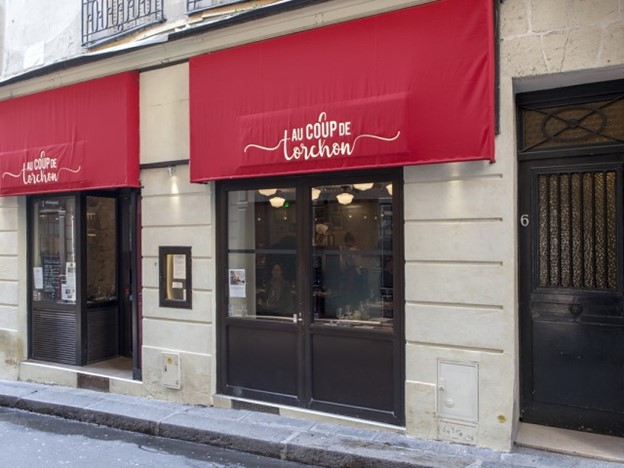
We talk about Defined Contribution, because who wouldn’t when they are in mixed company enjoying a delicious bit of cod over petits pois and fennel at Au Coup de Torchon. We have a 19-year-old with us who’s got an IRA with his first $3,000 in it. Alain and his wife have two kids that could also have these accounts, we say, if the French adopted more Defined Contribution (DC).
In this light, DC becomes more palatable. For himself he can’t see anything but defined benefit, but for his children, Alain can see how this would make sense. We ask - how many people stay with a company for most of their career? “Only me,” he says, laughing ruefully. “Kids today jump around,” and for this reason, a growing pot of tax advantaged retirement savings, socked away starting at a young age, really makes sense.
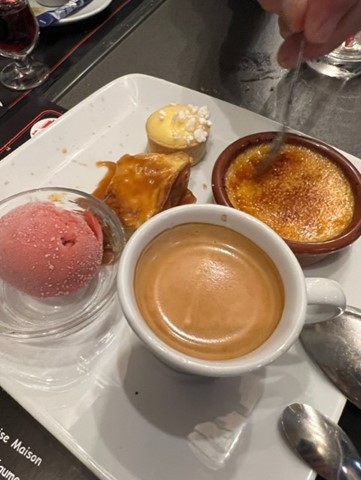
Did we win one person over? Maybe. Our technical French is questionable. What was unquestionable was the amazing creamy vanilla ice cream and the crunchy-topped creme brulee that circulated with our coffees. #recommend and we wish Alain a quick six years to his next chapter.
| |
|
A quick curation of a few things you won’t want to miss this week.
One. Interested in seeding capital for life? check out Aspen FSP's latest report, "The New Wealth Agenda: A Blueprint for Building a Future of Inclusive Wealth.” This great resource offers practical solutions to address America's growing generational wealth gap, emphasizing the need to invest in children from birth to create financial assets for young adulthood. The report's first Future of Wealth event will explore the potential impact of providing every 18-year-old with access to substantial "startup capital for life." This is happening July 26 - register here and don’t miss the fireside chat with U.S. Senators Cory Booker and Bob Casey!
Two. As a follow up to today’s piece on retirement age changes in France, unlock the insights and dive into Transamerica’s latest research on how the first 401(k) generation (i.e., Gen X) is the least prepared for retirement.
Three. Craving more content? A New Report Rings Alarm Bell on Generation X’s Retirement Realty. The National Institute on Retirement Security (NIRS) reveals a concerning retirement outlook for Generation X, the first generation to face the shift from pensions to 401(k)-style accounts. The report shows that the bottom half of Generation X earners have only a few thousand dollars saved for retirement, and the typical household has just $40,000 in retirement savings, with savings heavily concentrated among the highest earners, leading to potential elder poverty and financial pressure on families for support.
Four. Discover the Sizzling Summer Scoop on Retirement! Dive into the Center for Retirement Research at Boston College Newsletter with questions such as: do people know if they’re retirement ready?; should we offer 401(k)s credit cards?; what’s the latest on Medicare’s finances? and much more!
Five. Unveiling the Career Game-Changer! Delve into the impact of raising retirement age on career trajectories and earnings growth through this must-read paper. The difference-in-differences identification strategy of the analysis takes advantage of cohort-specific variation in pension eligibility rules caused by the 2007 reform of the German public pension system. Findings suggest that an increase in the expected work horizon increases upward occupational mobility and job promotion rates, but no shift in wage dynamics.
For some final inspiration:
From State to Success: unveiling the potential of workplace retirement with state-facilitated programs, a must-read guide for businesses from Paycheck online resource center.
According to a recent study from The Pew Charitable Trust in partnership with Econsult Solutions, states face a $334.3 billion shortfall over 20 years due to insufficient retirement savings, and automated savings programs for private sector workers can reduce the strain on government budgets. Want to learn how? Check out the analysis here.
Non related but super awesome - this year’s spelling bee champion was 14-year-old Dev Shah of Largo, FL. The final word? just a simple term with an indirect association with the summer beach season.
| |
...And some pix from our Parisian adventure | |
The joy of overnight seating in steerage. | |
From Welches, Oregon, to the bright lights of Paris. | |
Headed up the Eiffel Tower with 24,997 of our best friends. | |
Free Wall-e! He's trapped somewhere in Le Mans. | |
|
That’s it for this edition. ❤️ Hug your people and change the world.
If you like this piece, please stick with us. We’ll be back in about two weeks. If you don’t like it, please unsubscribe below. Comments for us? Please let us know. Want your own subscription? Request one here. All information shared is from public sources or used with express permission.
| |
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.
| |
|
Looking for a great retirement savings innovation resource? Led by Dr. Alicia Munnell, the Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.
The Georgetown Center for Retirement Initiatives, Exec Angela Antonelli, provides excellent information on state-based and other retirement security innovation and policy.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.
| | | | |