|
RETIREMENT SECURITY MATTERS
A forum for retirement innovation information sharing
focused on states, supporters, and service providers.
Vol 78 | May 18, 2023
| | |
Greetings! Lisa, welcome to Retirement Security Matters – where we talk about retirement readiness innovation by states, supporters, and service providers. | |
It's the end of May, and Auto IRA initiatives are racing the calendar as the 2023 legislative session ends. Grab a cool beverage and get your news on:
-
Advancing retirement savings: Minnesota, Missouri, and Vermont Get Busy
-
State metrics - over 50,000 employers facilitating, and more
-
Key updates from Delaware, Hawaii, Illinois, New Jersey, and Oregon – and a host of legislatively active states
-
Eyes on the Big Picture: Top Trends
-
Hot Sauce and Cool Stuff
-
… and Pix of the week!
| Comments or content suggestions? We welcome both. Have something about your program you’d like to share? We are all ears. | |
|
RSM wants your support! Be seen.
Click to grab this space for your brand.
| |
Advancing Retirement Savings: Minnesota, Missouri and Vermont Get Busy | |
(Art credit: DALL-E 2 with a little inspiration from us.) | |
|
It’s a big week for states. 🎉
Three new states are in the process of authorizing retirement savings coverage at work based on activity coming out of this year’s legislative sessions.
Minnesota, Vermont, and Missouri are the latest to join the coverage trend, having recently enrolled legislation to establish state-facilitated retirement savings programs. Two of the programs – Minnesota and Vermont – are Auto IRAs. Missouri’s legislation would establish a state Multiple Employer Plan, or MEP.
If the two Auto IRA state bills are signed into law, they bring the US Auto-IRA-covered population from zero to about 21 million when authorized programs are fully implemented. If the voluntary states were auto-coverage, they would add another 3.8 million workers. (Those states are MA, MO, NM, and WA.)
That’s not trivial compared to a starting gap of about 57 million working Americans.
Let’s take a look.
The Minnesota Approach: Minnesota Secure Choice 1.9 Retirement Program Act
Minnesota's Auto IRA initiative, the Minnesota Secure Choice Retirement Program (HF 782), is governed by a board with assistance from named state agencies. This program targets (... more detail on all three programs HERE)
On Trend
The progress in these three states fits the state coverage trend. Most years since 2015 have seen 1-3 states passing retirement coverage legislation. As a lead up to this, each year a small number of states also legislate for or otherwise conduct studies to understand the level and impact of under-coverage within the state. And with a short pause for headwinds (including the pandemic), every year a few more states get their legislated programs off the ground and into operating mode, with growing numbers of saver-funded accounts. The most recent additions to this list include Connecticut and Maryland in 2022, and Colorado and Virginia in 2023. New Jersey and New York are hot on their heels, with program launches anticipated for 2024.
And in Context
While these state-led initiatives are significant, it is important to understand them within the broader context of retirement savings in the US. Looking at the national picture, recent data suggests that the implementation of state-facilitated retirement savings plans for private sector workers may be having a positive impact on the creation and retention of private plans. This is particularly evident in states like California, Illinois, and Oregon, which have had such programs in place for at least four years and where new plan formation is flourishing at new, higher levels.
Hats Off to You Minnesota, Vermont and Missouri for expanding work-based access to retirement savings, and creating the opportunity for improved family financials that comes with it.
| |
*Fresh!* State Auto IRA Program Metrics | |
|
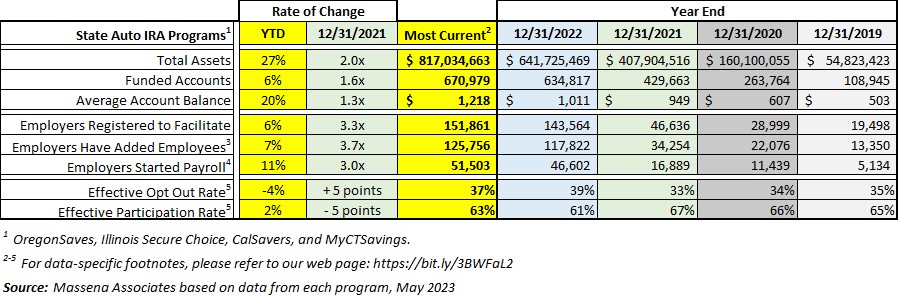
What’s up! We’ve got a full set of April data for the three long term Auto IRA states.
Assets. Saver assets are up 27% year-to-date and 2x since December 2021 to $817 million. Average account balances across the programs are over $1,200. Longer term balances are higher.
Funded accounts. The four programs shown here now aggregate to over 670,000 funded accounts. For comparison, funded accounts are up 1.6x since December 2021, up about 2.5x since December 2020 and up about 6.2x since December 2019 – and up in 2023.
Facilitating employers. Over 125,000 employers are now registered to facilitate a state Auto IRA. Of that number, more than 51,500 have begun forwarding payroll contributions for savers.
| |
State Facilitated Retirement Programs - Fresh Highlights | |
|
Delaware (workforce 499,000) – The Delaware EARNS Program Board welcomes Ted Griffith as the new Executive Director of the Program. Ted, we welcome you!
| |
|
Hawaii (workforce 676,000) - The Hawaii State Senate confirms Jessie Dean as part of the Hawaii Retirement Savings Board. The next board meeting is scheduled for May 25, 2023. You can get your copy of the agenda here.
| |
|
Illinois (workforce 6.4 million) - The Illinois Secure Choice Board is meeting on May 18, 2023. Key items on the agenda include program implementation, enforcement and legislative updates, and highlights of the program’s quarterly report, including outreach, and marketing. As for action items, the Board will discuss recommendations of investment changes, investment policy statements, and Board insurance policy renewal. Materials can be requested directly from the Illinois team.
| |
|
New Jersey (workforce 4.6 million) – The New Jersey Secure Choice Savings Program Board met on May 5, 2023. Key items on the agenda included program updates from the Executive Director. As for action items, the Board discussed the award of a contact for a marketing services firm.
| |
|
Oregon (workforce 2.2 million) - The OregonSaves Board met on May 17, 2023. The agenda included a summary report from Executive Director Michael Parker, a brief update from program administrator Vestwell, quarterly program update from Deputy Director David Bell, and investment performance report from Sellwood Consulting. Materials can be requested directly from the Oregon team.
| |
|
A C T I V E
Minnesota (workforce 3.1 million) The Senate approved SF413 in a 34-33 vote. Sen. Sandra L. Pappas (DFL-St. Paul) introduced the Senate version of the bill on Jan. 19, 2023. The House had passed HF782 in a 71-60 vote on May 1. The measure now goes to the desk of Gov. Tim Walz (D) where signature is expected. For more see coverage by ASPPA.
Missouri (workforce 3 million) retirement savings legislation HB155, The Show-Me MyRetirement Savings Administrative Plan is a multiple-employer retirement saving plan. On April 17, 2023, the bill was voted out of the House unanimously (141-0). On May 10, 2023, it was voted and reported Do Pass out of the Senate.
Nevada (workforce 1.5 million) reintroduced a bill creating a state-supported retirement plan for workers who do not have access to one at their workplace on March 16, 2023. SB305 has been referenced to the Committee of Finances and will be heard on May 18, 2023. The bill would create the Nevada Employee Savings Trust, which would be directed by a board of trustees with the power to establish a retirement savings program and automatically enroll private employees. The program would be targeted to go live July 1, 2025.
North Carolina (workforce 5.1 million) introduced HB496 on March 29, 2023. The bill has been referenced to the Committee on Pensions and Retirement. The program, known as the North Carolina Small Business Retirement Savings Program, or North Carolina Work and Save, would offer voluntary enrollment for employers, employees or self-employed individuals who do not currently offer or have a retirement plan. The program would be targeted to go live July 1, 2025.
Rhode Island (workforce 577,000) The Rhode Island Secure Choice Retirement Savings Program Act, S0545, would create the Rhode Island Secure Choice retirement savings program. The Senate Finance Hearing was held on May 11, 2023. The Committee recommended measures be held for further study.
Tennessee (workforce 3.4 million) Introduced in December and January, HB0013/SB0113, the Tennessee Retirement Savings Plan Act would create a Tennessee retirement savings board empowered to develop an Auto IRA program for the state’s private sector workers whose employers do not offer plans. On the House side, the bill was taken off notice for the Public Service Subcommittee of State Government Committee on March 21, 2023.
Vermont (workforce 336,000) On May 9, 2023, the Vermont House and Senate passed S0135, also known as VTSaves Retirement Program. According to AARP, the VTSaves will be “life-changing for the over 88,0000, hardworking private-sector Vermont employees without a workplace plan”.
See also the states we highlighted in RSM77 for a complete current view.
| |
|
C O M I N G U P
-
Virginia (workforce 4.3 million) – The next meeting of Virginia’s Retirement Program Advisory Committee is tentatively scheduled for May 24, 2023.
-
Hawaii (workforce 676,000) - The next meeting of the Hawaii Retirement Savings Board is scheduled for May 25, 2023.
-
Oregon (workforce 2.2 million) – The next meeting of the OregonSaves Board is scheduled for August 15, 2023.
-
Maryland (workforce 3.2 million) – The next meeting of the Maryland$aves Board is scheduled for September 11, 2023.
| |
|
We talk a lot about states in this space. Let’s telescope out for a moment to consider some of the top trends in US retirement savings coverage and access, according to research from Zippia. Each of these is likely material to some of the work you are doing today. #headsup
-
Increasing Age of Retirement: The average retirement age for men is 64.7 and for women is 62.1. Some trends indicate that people are retiring later than they used to, and this could be due to a variety of factors, including longer life expectancies, financial needs, and changes in employment patterns. Interestingly, 95% of retirees stay in the state they live in. The rest of us go to Florida.
-
Significant Disparities in Savings: On average, the retirement account savings in the United States is $73,100 as of 2021, but there is considerable disparity. 25% of Americans have no retirement savings at all, while 25% believe they need over $1 million to retire comfortably. This indicates a large gap between the amount people have saved and what they believe they will need.
-
Impact of COVID-19 on Retirement Savings: The COVID-19 pandemic has significantly impacted retirement savings, particularly for seniors. Since the start of the pandemic, only 57% of seniors aged 60 or older have at least $100,000 in retirement savings, compared to 74% who had this amount before the pandemic.
-
Gender and Racial Disparities: Women on average have 40% less in retirement savings than men and retire about two years earlier. Meanwhile, there are significant racial disparities as well. Around 30% more Black and Latino households do not own assets in a retirement account compared to White households. Furthermore, Asian, Black, and Latino workers are less likely to have access to private-sector retirement plans compared to their White counterparts.
We at RSM want to say we haven’t independently fact-checked these statistics, but the trends seem right on. We hear daily from professionals in industry who are working on specific initiatives to support increasing equity in retirement savings access and outcomes, and increasing personalization in retirement readiness planning and investing, both of which will be material to helping US workers meet their own retirement needs in coming years.
| |
|
Here’s a quick curation of a few things you won’t want to miss this week.
Very important if you want to save taxpayer money. Research shows that state auto IRA programs would reduce taxpayer burden from insufficient saving. A new study by The Pew Charitable Trusts finds that Americans’ insufficient retirement savings will significantly affect every state and the federal government over the next 20 years, resulting in an estimated $1.3 trillion burden from increased public assistance costs, reduced tax revenue, decreased household spending and standards of living, and lower employment.
ICYMI - DCIIA Innovation Forum edition - if you weren’t with us this March, here’s a quick recap of some of the top sessions, as reported by attendess Michael Andeberhan, Sara Shean, and Steve Ferber.
Anddddd … The Stanford Center on Longevity has just published the winners of its 10th Annual Design Challenge, Optimizing Health Span. This is a big topic at our house. Eight finalists are bringing us a range of ideas, from a new tool to monitor dental health (important to longevity) to an informational and hormone-testing kit for menopause. Menopause is hard to talk about! But a proactive approach extends health span for sure, for a good 50% of us.
In our ears. We finally finished reading Hoover: An Extraordinary Life In Extraordinary Times – by Kenneth Whyte, and via Audible. A crispy, critical analysis of the 31st president that shows off his genius and his flaws. As we slide into the highly-praised but less critical biography of FDR by Jean Edward Smith, we see Roosevelt and his supporters taking credit for the exact things Hoover said they would. An interesting transition from one biographer’s view to the next.
For the eyes. Some inspiration … “Routine seen through Wes Anderson’s eyes is always prettier,” And we agree! The viral TikTok trend under the hashtag #WesAnderson has already racked up a billion views. A few favorites: everyday moments, a guide to surviving a global pandemic, a guide to surviving a global pandemic and AI as a way of looking at day-to-day life.
| |
Would you like a Pic of the Week? | |
The kid is back from college and all is well. | |
|
That’s it for this edition. ❤️ Hug your people and change the world.
If you like this piece, please stick with us. We’ll be back in about two weeks. If you don’t like it, please unsubscribe below. Comments for us? Please let us know. Want your own subscription? Request one here. All information shared is from public sources or used with express permission.
| |
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.
| |
|
Looking for a great retirement savings innovation resource? Led by Dr. Alicia Munnell, the Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.
The Georgetown Center for Retirement Initiatives, Exec Angela Antonelli, provides excellent information on state-based and other retirement security innovation and policy.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.
| | | | |