|
RETIREMENT SECURITY MATTERS
A forum for retirement innovation information sharing
focused on states, supporters, and service providers.
Vol 83 | August 17, 2023
| | |
Greetings! Lisa, welcome to Retirement Security Matters – where we talk about retirement readiness innovation by states, supporters, and service providers. | |
Are you in a heat dome? We are! It’s time for a break. Find yourself a comfortable spot in front of a fan or the AC, or that special spot in the office that’s always cold, and join us as we dive into the latest in retirement security.
-
Three things you can do now to make 2024 *awesome*
- Frrreshhh state metrics
- Updates from California, Connecticut, Hawaii, Oregon and Maine
- No fries with that please - Best Practices to reduce angst
-
Hot Sauce! and some cooool stuff for the dog days of August 🐕
-
… PIX of the Week!
| Comments or content suggestions? We welcome both. Have something about your program you’d like to share? We are all ears. | |
|
RSM wants your support! Be seen.
Click to grab this space for your brand.
| |
Summer Season: Getting Ready for 2024 | |
Zoom zoom, let’s go! Photo credit: Jairo Anaya | |
|
Have we been taking it easy this summer, enjoying the lazy days of sunshine and vines? Yes, we have. It’s the legislative off season for many in the state and federal systems, and a time of project management and breath-catching for those working in the private sector and policy space.
And it’s also a good time to turn our attention to 2024. Yes, 2024. If you want to think about the future in a relaxed way, it needs to be in the future.
Whichever seat you occupy, we’ve compiled a view of some of the things you can be considering, connected to your role in expanding retirement savings access and use in the coming year. Today we’ll give you the first three.
| | |
|
Legislative Advocacy: Are you in the policy, state, or federal space? If your portfolio includes retirement, you may be getting ready to: | |
- Work with lawmakers to draft and support legislation that encourages our employers to offer retirement savings plans, or requires them to facilitate state-led savings programs. It’s a light lift for a lot of impact.
- Here’s a federal version of this – we prefer a standard that allows employers to use existing state programs across borders over a new federal plan for a few reasons – but all ideas deserve a good look.
- Draft improvements to existing legislation that simplify access and use for more savers – like this one, and this one. Get your conversations and collaboration with lawmakers on – legislation is hard!
- Advocate for state-level tax incentives for individuals and small businesses to contribute to retirement accounts. Did you know states accrue significant taxpayer savings opportunities when retirement readiness levels go up?
| | |
|
Financial Education and Literacy Programs: | |
-
Develop ways to coordinate and integrate comprehensive financial literacy campaigns targeting various demographics, especially underserved communities. Here’s a federal example. And a national one.
-
Support state efforts to expand financial education in schools. These states have been active recently.
-
Link financial education to development of an Auto IRA program, like Colorado has.
-
Partner with schools, community organizations, and employers to offer workshops, seminars, and online resources on retirement planning. #peoplefirst
| | |
|
Technology Integration and Innovation: | |
-
Invest in user-friendly online tools, apps, and platforms that make retirement planning more accessible and understandable. Here’s what else your colleagues are up to.
-
Explore innovative solutions like robo-advisors to provide personalized investment advice at a lower cost. We all have opinions on this. Engine-powered advice supported by human engagement seems optimal.
-
Are you using AI in consumer-facing solutions? We’re having a love-hate relationship with it’s out-of-the-box capabilities, but here’s what some others are up to.
| |
We’ve got more to talk about, but this is plenty for a hot August day.
Get back to sipping that lemonade and plinking through email, right after you schedule yourself some time to cogitate and make your plans for a great 2024.
Lisa
| |
*Fresh!* State Auto IRA Program Metrics | |
|
What’s up! July figures are rolling in …
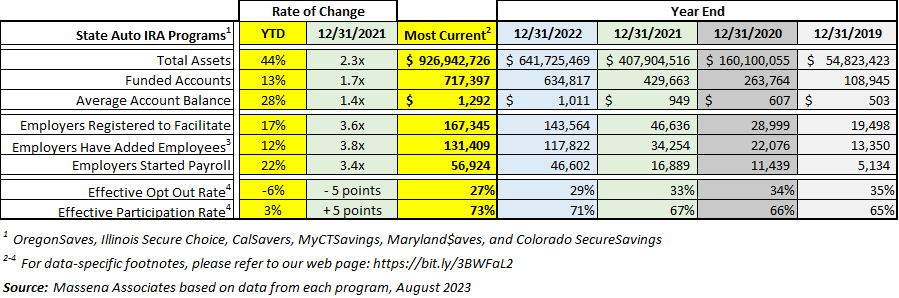
Assets. Saver assets are up 44% year-to-date and 2.3x since December 2021 to $926 million. Average account balances across the programs are over $1,200. Longer term balances are higher.
| | |
|
|
What’s your guess for the $1 billion mark? it wasn’t RSM 83 - August 10 ...
Send us a note - closest date wins you a prize - votes are rolling in.
RSM 84 – August 31 // RSM 85 - September 14 // RSM 86 - September 28
| |
|
Funded accounts. The six programs shown here now aggregate to over 717,000 funded accounts. For comparison, funded accounts are up 1.7x since December 2021, up about 2.7x since December 2020 and up about 6.6x since December 2019 – and up in 2023.
Facilitating employers. Over 167,000 employers are now registered to facilitate a state Auto IRA. Of that number, more than 56,900 have begun forwarding payroll contributions for savers.
| |
State Facilitated Retirement Programs - Fresh Highlights | |
|
California (workforce 19.2 million) – State Treasurer Fiona Ma has named David Teykaerts as CalSavers’ new Executive Director. Teykaerts, recently Interim Chief of Stakeholder Relations at the California Public Employees Retirement System (CalPERS), brings expertise in stakeholder engagement, investment strategy, and policy. Welcome aboard, Friend – we can’t wait to see the impact you will have! Here’s the news release and great coverage from ASPPA, Plansponsor, and Pension & Investment (subscription may be needed to view this piece).
| |
|
Connecticut (workforce 1.9 million) – The Connecticut Retirement Security Program Advisory Board of Directors met July 21, 2023. Key items on the agenda included the Chairman’s report covering interstate partnership and legislative updates. HB 6552 - makes technical changes to the program, and HB 6941 section 115 - changes the payback timeline for the program.
BNY Mellon gave an update on the Q1 investment advisory report. Program administrator Vestwell provided a program status update which included the progress of all three waves, and the beginning of the new wave 2023, with efforts focusing on the August 31, 2023, deadline.
Also included on the agenda were program updates on regulations. On a procurement note, the program noted re-selection of program consultant AKF and investment consultant Segal Marco. The program’s audit RFP is being finalized and expected to be issued shortly.
| |
|
Hawaii (workforce 676,000) - *Program Director Opportunity*: Hawaii’s Department of Labor and Industrial Relations has opened the search for the Retirement Savings Executive Director for the Hawaii Retirement Savings Program. View the position description and information on how to apply here. (check out Plansponsor recent post.)
Special note: in recognition of our friends in and connected to Hawaii, we are providing this link from CivilBeat.org with a locally-curated list of ways to donate and to support families impacted by fire on Maui.
| |
|
Maine (workforce 674,000) – The Maine Retirement Savings Board met August 16, 2023. You can find the agenda, and the freshly-approved July meeting minutes here. Top of the list - Maine and Colorado have formalized their agreement to offer a partnered program to savers. The two states are expected to be the first to partner in this way in the state Auto IRA space, with more states likely to follow soon. (Colorado and New Mexico signed a partnership agreement, but NM is not yet ready to launch.)
In other news Maine is progressing its pilot employer readiness alongside broader outreach and engagement initiatives. Investment consultant Meketa provided an investment options overview and the Board approved a program investment policy statement. Program rules will be provided for a public hearing concurrent with the program’s September board meeting. Program pricing, discussed at this meeting, is likely to be finalized in September as well. Finally, Executive Director, Beth Bordowitz, expects to issue a Marketing Services RFP very shortly.
| |
|
Oregon (workforce 2.2 million) - Good news, and a dose of reality. Mellow headlines don’t get eyeballs, but spicy ones sure do. Six years after it opened its program pilot, Oregon is in the process of completing its rollout to Wave 6 following a July 31 final program deadline. Originally scheduled to roll out over a three year period, the program stretched its timeline to accommodate the pandemic, and possibly an election or two. Wave 6 includes employers with one or more Oregon W-2 employees. The program has achieved more than $200 million saved through about 120,000 funded accounts. It is believed that not much of these assets would have been set aside for retirement without the program’s payroll deduction savings offering.
In Oregon’s Board meeting on August 15, Treasurer Read and new Executive Director, Ryan Mann, recognized and thanked departing founding board members Cory Streisinger and Edward Brewington for their thoughtful and dedicated service to Oregon through this program board.
Observations from the article referenced above. Savers quoted in the piece are pleased to be included and pleased to have balances. Some small employers wish they’d had better communication – and the program notes that its data sources for direct-to-employer outreach, drawn from state databases, have their limits. In all however, and despite the article’s title, the program appears to be operating fairly smoothly for both larger and smaller employers.
| |
|
C O M I N G U P
-
Virginia (workforce 4.3 million) – The next meeting is tentatively scheduled for August 23, 2023.
-
Massachusetts (workforce 3.6 million) - The next meeting is tentatively scheduled for August 28, 2023.
-
Maryland (workforce 3.2 million) – The next meeting of the Maryland$aves Board is scheduled for September 11, 2023.
| |
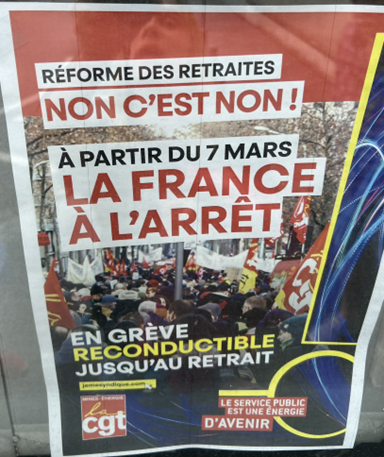
“Pension reform. No, it's a no! Starting March 7, France comes to a halt. A renewable strike until reform is withdrawn. Public service is energy of the future.” | |
People care about their retirement. (When) (will) what’s happening in France migrate to the US?
You could argue we are seeing a bit of it right now. Labor is tight. For a range of reasons employers, especially those whose jobs rank at the lower end of the income spectrum, can’t find enough qualified workers to hire at prevailing wages and with prevailing benefits.
Just ask my friends at the local Dairy Queen, where I’m told they are running the drive-through only, because they can’t staff up for inside dining.
Ask too the more than 300,000 workers who have walked off work and gone on strike this year here in the US this year.
It would be naïve to say that throwing retirement benefits into the compensation package could change that equation dramatically. But it turns out it does help. And it helps in particular for workers in their 30s+ – one of whom served me at DQ – who often have to leave or will decline employment that doesn’t come with retirement access.
You could also argue that we’ll see it in a few years when Social Security pass through benefits to retirees are greater than the Social Security contributions being made by US workers. Like France, we’ll either need to stretch our full retirement dates, or reduce benefits, or – the horror – raise taxes. Or a bit of all three. We’re sure we won’t see action on this until the absolute last minute, because that’s how these things get done. Hopefully we will be armed with a number of good proposals when that day comes.
Now you could also argue that we’ll never see the level of angst witnessed in French cities this year. We have a well-formed defined contribution system. We’ve been using it for years. It covers many. Long-term savers and higher income workers are beginning to retire well out of this system relying on the two legs of Social Security and Defined Contribution with a splash of Defined Benefit here and there.
If we want to stay ahead of the wave, let’s make sure this system continues to get stronger. Let’s work on universal access, broad deployment of best practices like automatic enrollment with escalation, and good retirement income capabilities that make it easier for people to create paycheck replacement and manage risk in retirement.
Baguettes are good. Retirement beefs are not. Let’s avoid!
| |
|
Curated just for you, and lite lite lite this week:
Survey Sparks Optimism. A recent article by The Pew Charitable Trusts reveals that early participants in Illinois Secure Choice have displayed limited engagement, with many not regularly checking their accounts or being aware of their savings amounts. Despite this, the data highlights successful adherence to program goals: participants are consistently saving for retirement, aligning with the program's aim. The survey, conducted in multiple phases by the Rand Corp., sheds light on participants' experiences and trends in engagement over time.
Our friend Geoffrey Sanzenbacher asks, Is the Gender Gap Closing? Surprising results from 2021 … and some pithy thoughts. One callout: caregiving matters.
In the ears. After 54 hours and 11 minutes we have finally wrapped up David McCullough’s Truman. Talking about historic figures feels fraught. For example, is there any way they could have avoided using the Atom Bomb? We’re not war experts but it both seems as if they felt they couldn’t, but that after having done it that sort of action should never be repeated again, ever. Some things we learned about Truman: he was a pretty steady guy – sometimes way up in the polls, sometimes way down, almost always consistent and often praised after the fact for things others thought would never work / were dumb ideas at the time he was championing them. He served in World War I and presided during WWII and the Korean War. His was the tough act of following FDR. In his second term he made the office his own. And, he was the last president to leave office without a pension. That’s a tough transition. His experience put the concept of citizen-president-citizen to the test.
| |
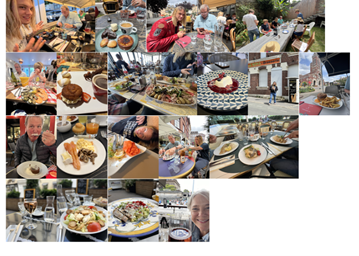
We heard everyone from the US is in Europe this year, and it may be true. We were, briefly, dining our way through Brittany, Normandy, and southern Belge. Clothes still fit though! | |
|
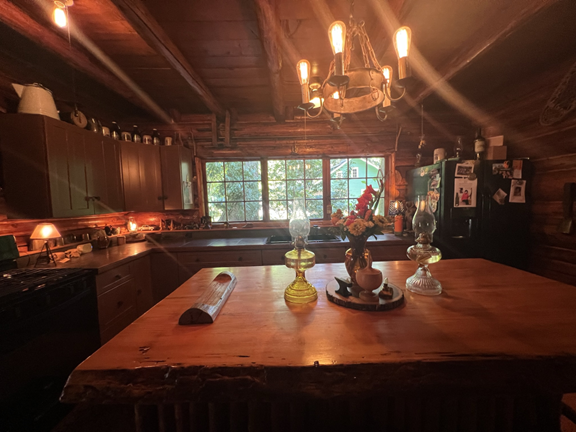
We made it back to Oregon for the 2023 Steiner Cabins Tour - this year 300 lucky attendees beat out 1,300 other hopefuls for tickets to the one-day event. You weren’t there? No worries, you can enjoy a virtual tour here, on the cabins’ Facebook page.
And here’s a little gem for you in the meantime. Happy Trails.
| |
The joy of overnight seating in steerage. | |
|
That’s it for this edition. ❤️ Hug your people and change the world.
If you like this piece, please stick with us. We’ll be back in about two weeks. If you don’t like it, please unsubscribe below. Comments for us? Please let us know. Want your own subscription? Request one here. All information shared is from public sources or used with express permission.
| |
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.
| |
|
Looking for a great retirement savings innovation resource? Led by Dr. Alicia Munnell, the Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.
The Georgetown Center for Retirement Initiatives, Exec Angela Antonelli, provides excellent information on state-based and other retirement security innovation and policy.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.
| | | | |